








Key Takeaways:
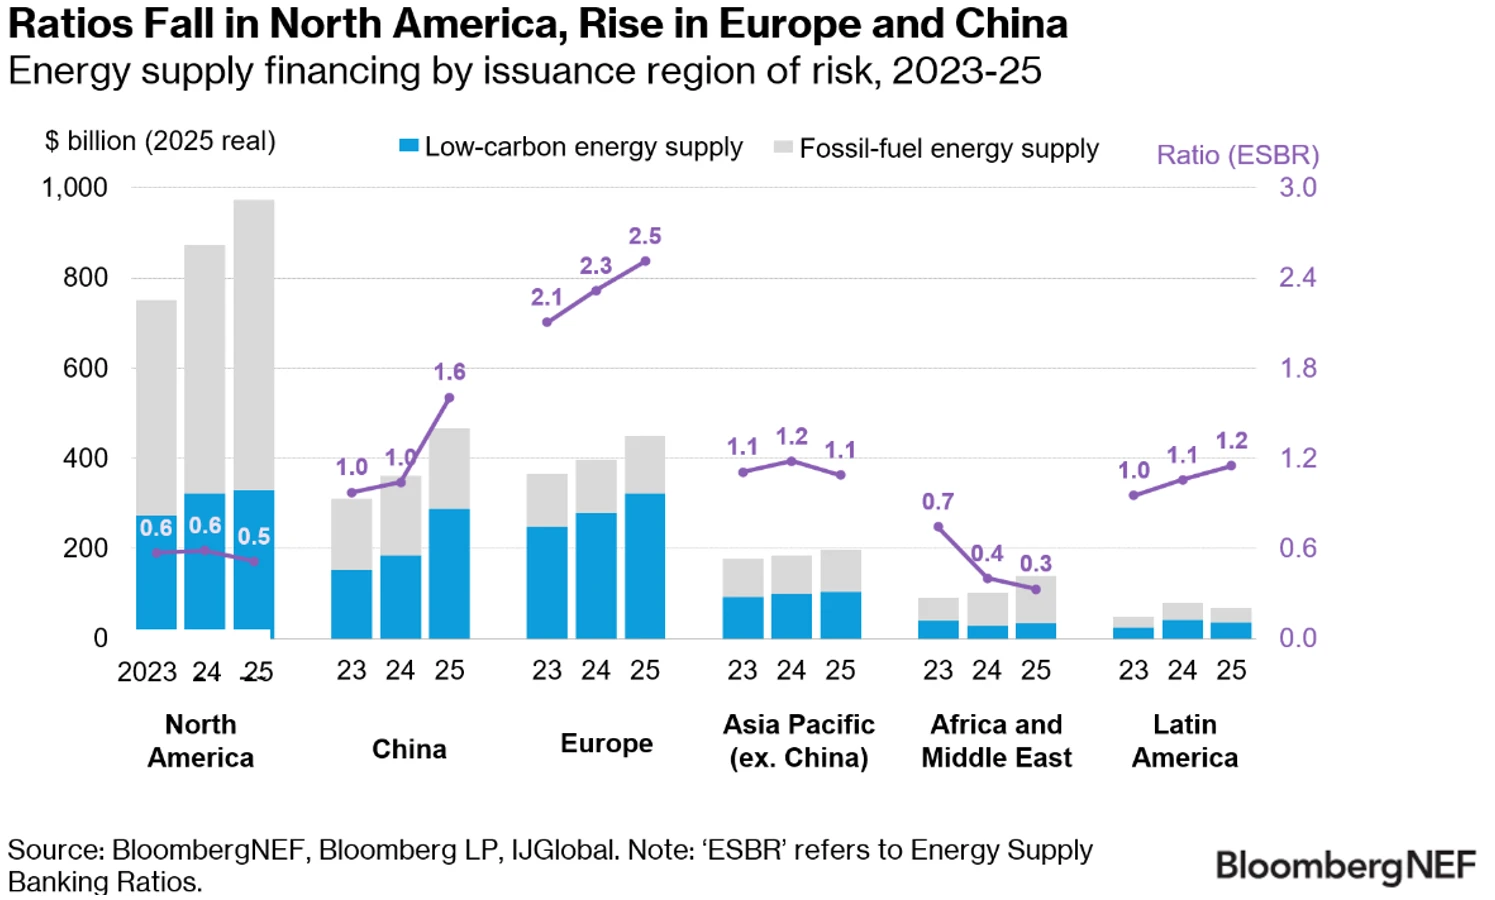
Global banks arranged $0.97 of low-carbon energy supply finance for every dollar of fossil-fuel financing in 2025, according to BloombergNEF’s latest Energy Supply Banking Ratios report. That ratio marks a gradual improvement from 0.95:1 in 2024, but remains far below the average 4:1 Energy Supply Banking Ratio (ESBR) needed this decade to align with climate goals.
Despite a shift toward low-carbon energy, fossil-fuel investment still rose in aggregate terms. Elevated oil and gas financing among the trillions in recourse debt, public equity, project finance and tax equity tracked by BNEF pushed fossil-fuel volumes up to $1.19 trillion. Low-carbon financing grew faster, however, reaching a five-year high of $1.15 trillion, boosted by grid financing.
The ESBR has been adopted by more major North American banks this year, even as their financing has broadly shifted toward fossil fuels. Bank of Nova Scotia and the Royal Bank of Canada joined JPMorgan and Citi in disclosing their own versions of the ratio. The Canadian Imperial Bank of Commerce also published a methodology this year and has yet to publish a ratio. Greater disclosure may be the first step toward further action on the ratios, even as many non-disclosing banks continue to post year-on-year improvements.
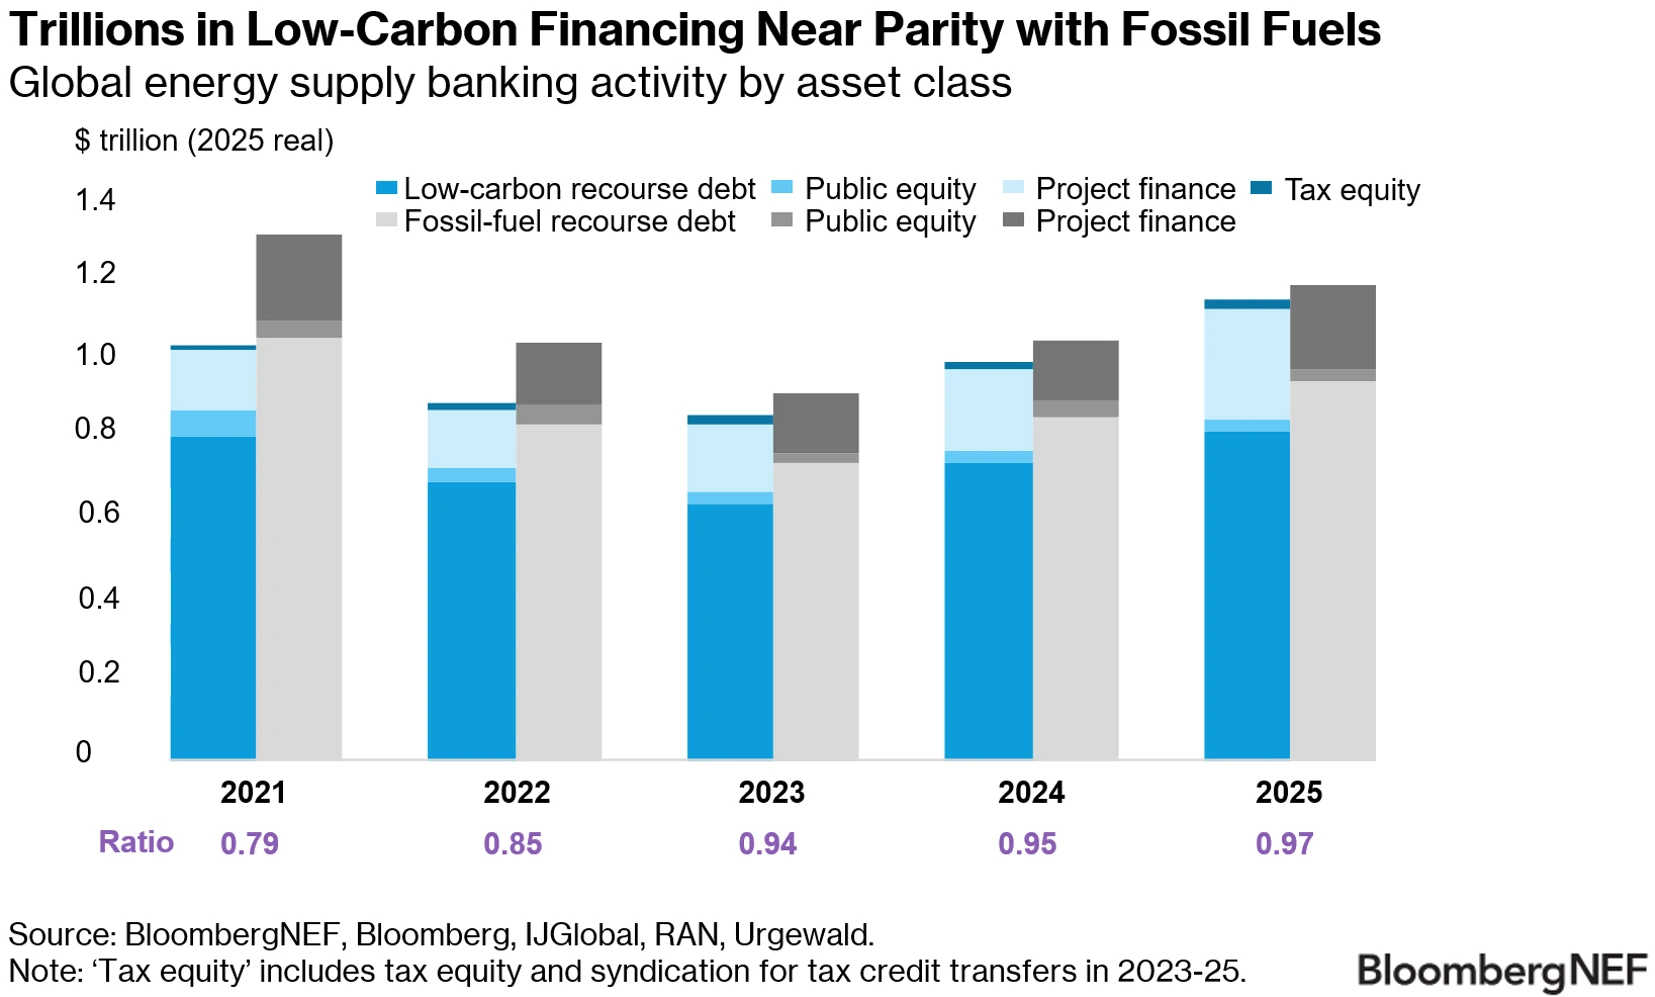
The largest banks by energy-supply financing volume remain predominantly fossil-heavy.
JPMorgan Chase was the largest bank by financing volume with about $100 billion in 2025. Its ratio fell to 0.63:1 due to rising fossil-fuel financing in the US and a slight drop in low-carbon financing. MUFG ranked second with $77 billion. The bank’s ratio also fell following greater fossil-fuel activity, particularly in the US.
Bank of China was the institution with the highest ESBR in 2025 among the list of biggest banks, with a ratio of 1.84:1 – rocketing up from 1.04:1 in 2024. It is also the only top 10 bank that has experienced sustained year-on-year improvements in its ratio, up from just 0.58:1 in 2021. Grid financing has been the main source of the upward momentum and will likely continue to lift its ESBR. China’s largest grid player, State Grid Corporation of China, has already issued an additional $61 billion in debt through the first half of 2026. As a main facilitator of this debt, Bank of China’s involvement should keep its ratio elevated.
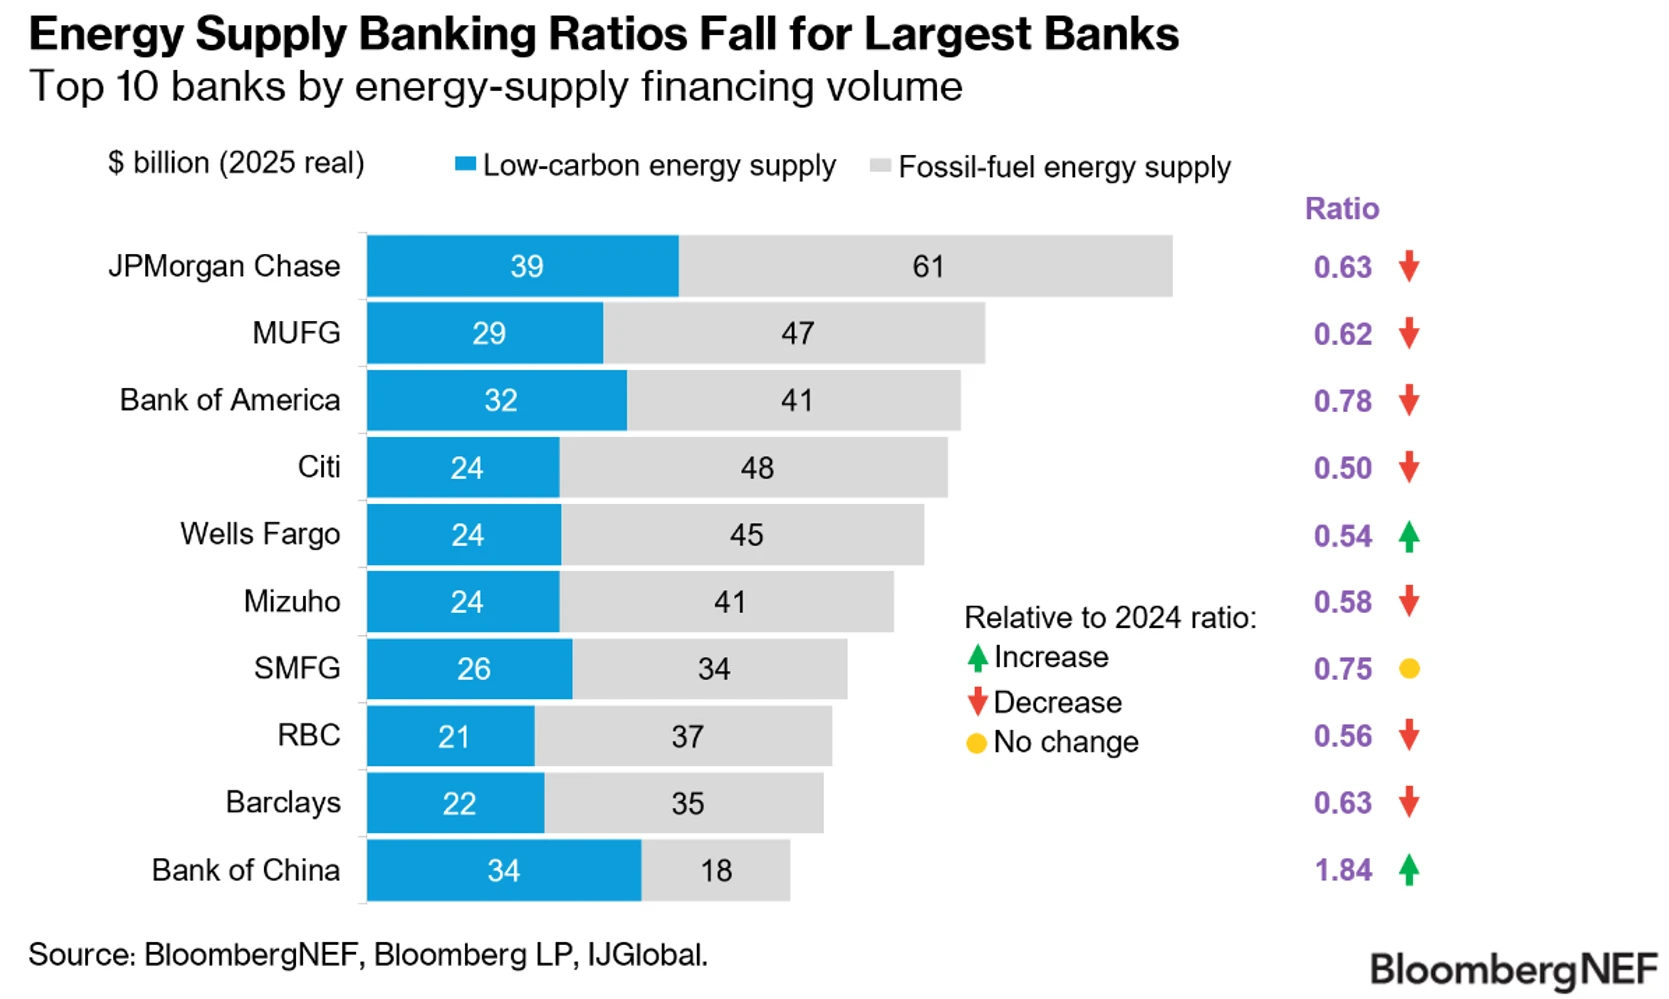
China’s ESBR jumped to 1.6:1 in 2025, as grid financing surged; State Grid Corporation of China issued over $105 billion in grid financing in 2025, up $67 billion from 2024. Oil and gas financing volumes declined, amplifying the ratio’s rise.
Europe retained the highest ESBR of any region, rising to 2.5:1, from 2.3:1. A 75% year-on-year growth in financing for wind projects boosted its ratio, largely from offshore wind project finance.
North America moved in the opposite direction. The region remained the largest market, with financing rising to $973 billion, but most of the increase went to fossil fuels. Fossil-fuel financing increased by $92 billion, compared with only $8 billion for low-carbon financing. This pushed the region’s ratio down to 0.5:1 in 2025, mainly driven by activities in the US. Financing in the US for companies with coal-related revenue exposure increased to record levels, at $42 billion.
When adjusting ESBRs on company capex rather than revenue, bank financing begins to tilt low-carbon. The capex-based ratio sits at 1.32:1 in 2025, higher than the 0.97:1 revenue-based result. Under this view, banks have facilitated more low-carbon than fossil-fuel financing every year since 2022. While revenue reflects past investment decisions, capex highlights business model shifts and investments – reflecting the ongoing energy transition.
Utilities are responsible for a significant portion of this change. The capex-based ratio among deals for utilities issuers reached 3.0:1, compared to a 1.59:1 revenue-based ratio in 2025. The shift is particularly strong for utility issuers in China and Europe, benefiting banks with strong exposure in these markets. Deals for Chinese utilities aggregate to a capex-based ratio of 12.7:1, far above the 4.24:1 under the revenue approach.
© Bloomberg Finance L.P. 2026. This publication is the copyright of Bloomberg Finance L.P. in connection with BloombergNEF. No portion of this document may be photocopied, reproduced, scanned into an electronic system or transmitted, forwarded or distributed in any way without prior consent of BloombergNEF.
Disclaimer
The BloombergNEF (“BNEF”), service/information is derived from selected public sources. Bloomberg Finance L.P. and its affiliates, in providing the service/information, believe that the information it uses comes from reliable sources, but do not guarantee the accuracy or completeness of this information, which is subject to change without notice, and nothing in this document shall be construed as such a guarantee. The statements in this service/document reflect the current judgement of the authors of the relevant articles or features, and do not necessarily reflect the opinion of Bloomberg Finance L.P., Bloomberg L.P. or any of their affiliates (“Bloomberg”). Bloomberg disclaims any liability arising from use of this document, its contents and/or this service. Nothing herein shall constitute or be construed as an offering of financial instruments or as investment advice or recommendations by Bloomberg of an investment or other strategy (e.g., whether or not to “buy”, “sell”, or “hold” an investment). The information available through this service is not based on consideration of a subscriber’s individual circumstances and should not be considered as information sufficient upon which to base an investment decision. You should determine on your own whether you agree with the content. This service should not be construed as tax or accounting advice or as a service designed to facilitate any subscriber’s compliance with its tax, accounting or other legal obligations. Employees involved in this service may hold positions in the companies mentioned in the services/information.
The data included in these materials are for illustrative purposes only. The BLOOMBERG TERMINAL service and Bloomberg data products (the “Services”) are owned and distributed by Bloomberg Finance L.P. (“BFLP”) except (i) in Argentina, Australia and certain jurisdictions in the Pacific islands, Bermuda, China, India, Japan, Korea and New Zealand, where Bloomberg L.P. and its subsidiaries (“BLP”) distribute these products, and (ii) in Singapore and the jurisdictions serviced by Bloomberg’s Singapore office, where a subsidiary of BFLP distributes these products. BLP provides BFLP and its subsidiaries with global marketing and operational support and service. Certain features, functions, products and services are available only to sophisticated investors and only where permitted. BFLP, BLP and their affiliates do not guarantee the accuracy of prices or other information in the Services. Nothing in the Services shall constitute or be construed as an offering of financial instruments by BFLP, BLP or their affiliates, or as investment advice or recommendations by BFLP, BLP or their affiliates of an investment strategy or whether or not to “buy”, “sell” or “hold” an investment. Information available via the Services should not be considered as information sufficient upon which to base an investment decision. Bloomberg makes no claims or representations, or provides any assurances, about the sustainability characteristics, profile or data points of any underlying issuers, products or services, and users should make their own determination on such issues. The following are trademarks and service marks of BFLP, a Delaware limited partnership, or its subsidiaries: BLOOMBERG, BLOOMBERG ANYWHERE, BLOOMBERG MARKETS, BLOOMBERG NEWS, BLOOMBERG PROFESSIONAL, BLOOMBERG TERMINAL and BLOOMBERG.COM. Absence of any trademark or service mark from this list does not waive Bloomberg’s intellectual property rights in that name, mark or logo. All rights reserved. © 2026 Bloomberg.
Sign up for BNEF’s free newsletter.
此内容由惯性聚合(RSS阅读器)自动聚合整理,仅供阅读参考。 原文来自 — 版权归原作者所有。