





👋 Welcome to Climate Drift: your cheat-sheet to climate. Each edition breaks down real solutions, hard numbers, and career moves for operators, founders, and investors who want impact. For more: Community | Accelerator | Open Climate Firesides | Deep Dives
Hey there! 👋
Skander here.
$34.5 billion across 152 deals. June closed the first half of 2026, and for the first time this year the largest transaction of the month wasn’t a venture round. It was a syndicated bank loan.
Jarek’s latest Follow the Money breaks down where the capital actually went, and the regional splits tell you more than any macro forecast could.
🇺🇸 North America: $14.4B across 33 deals, the dollar leader and the sharpest thematic concentration of the month. The Darden project in California’s Central Valley took $4.95B of construction debt for 1.15 GWac solar plus 4.6 GWh storage. Helion raised $465M at ~$15.5B against a Microsoft offtake, Thea closed $100M for its stellarator, Endurance pulled $54M for seafloor geothermal. Then Washington committed up to $17.5B in DOE loans for long-lead components across 10 AP1000 reactors (not counted in the month total).
🇪🇺 Europe: $8.6B across 37 deals, split between very large public packages and the deepest mid-stage deep tech layer anywhere. Stegra closed $1.6B on hydrogen-DRI green steel, a Wallenberg-led equity consortium stacked over a fully approving lender group. The Commission put $1.73B of interest-free ETS-funded loans behind European battery cell manufacturing. ICEYE took $520M past a €10B valuation on all-weather flood radar.
🌏 Asia: $3.3B across 39 deals, the deal-count leader with the smallest average cheque. India ran the renewables long tail, with Avaada closing $950M across three utility-scale projects including a firm-and-dispatchable one in Bikaner. China opened a fusion cluster nobody had on the board: four rounds in a single month, one of them CATL’s first fusion bet.
🌍 Rest of World: $8.1B across 43 deals. Australia alone was $4.6B, almost all federal. Tender 8 of the Capacity Investment Scheme underwrote 15 grid-scale batteries totalling 4,205 MW and 16,074 MWh, the largest storage procurement in the tracker to date. Spiro raised $270M for electric two-wheelers and battery swapping across seven African markets. Ecobank issued the first ICMA-designated Nature Bond from a commercial bank at $450M, 3.9x oversubscribed.
A few patterns worth flagging: public markets reopened for climate after a long IPO drought, with ERock listing on the NYSE at ~$600M and Lime pricing at $167M on Nasdaq, though Deep Fission raised $40M against a $150M target and priced 33% below plan. Open, but picky. Project finance ($10.8B) and government programmes ($6.3B) drove more than half the month while venture supplied just $2.5B, a barbell with a thinning middle. And Western Europe recorded its hottest June ever while adaptation took $825M, 2.4% of the total.
🌊 Jarek breaks it all down below, region by region, theme by theme.
But first: Who is Jarek?
Jarek Dmowski is a global transformation leader who partners with high-growth companies with positive climate impact. He combines industry and climate finance expertise with a strong track record of driving growth—across PE/VC-backed scaleups, ABN AMRO, and BCG.
He scaled a data-driven technology company ~2.5x to ~$25M in revenue and led post-merger integrations that enabled ~6x accelerated growth. At a global financial institution, he spearheaded a $2B capital reallocation toward new energy and mobility. He also developed a comprehensive climate plan that translated the Paris Agreement into actionable targets across sectors and established a $250M program to drive efficiency gains and reduce emissions at an energy utility.
Jarek is passionate about how the climate transition reshapes economies and business models, creating significant opportunities for multi-country growth and impact.
Welcome to the next edition of “Follow the Money” - a monthly briefing on the capital flows shaping the climate transition.
$34.5B in June. America’s $4.95B solar giant. Australia’s $3.9B battery sweep. Climate markets reopen for public investors. And a $17.5B U.S. nuclear commitment.
June closed the first half of 2026 with $34.5 billion across 152 identified climate-related transactions.
The largest transaction of the month was not a venture round, but infrastructure finance: Darden - a 1.15 GWac solar project paired with 4.6 GWh of battery storage in California’s Central Valley - secured a $4.95 billion syndicated bank loan. Australia provided another signal. The federal Capacity Investment Scheme Tender 8 awarded revenue-underwriting support to 15 grid-scale battery projects totalling 4,205 MW / 16,074 MWh - representing roughly $3.9 billion of supported investment and the largest storage procurement captured in the tracker to date.
But June also reinforced another 2026 theme: the U.S. Department of Energy announced up to $17.5 billion in conditional loan commitments to support the development of 10 large nuclear reactors, underlining Washington’s renewed push to expand domestic nuclear capacity.
June also delivered something we had not seen in previous months: public markets reopening for climate. After a prolonged drought for clean-tech IPOs, investors began returning to climate infrastructure. ERock (Enchanted Rock) listed on the NYSE (~$600M), Lime priced its Nasdaq debut (~$167M) and Standard Nuclear filed for a $383M NYSE listing - though Deep Fission’s undersubscribed raise showed the reopening is still careful.
The timing could not be more urgent. Western Europe experienced its hottest June on record, with extreme heat contributing to excess mortality across the continent while wildfires spread across Iberia and southern France. Physical climate impacts are no longer distant scenarios - they are accelerating the need for resilient energy systems, water infrastructure, food security solutions and adaptation finance.
Let’s dive deeper.
Explanation of the approach and source data: The investment list was developed based on disclosures, newsletter monitoring and review of climate news. Although not exhaustive, 152 climate-related investment deals were tracked - amounting to roughly $35 billion (all data in US$), covering all continents and different life stages of companies and development finance programs. Data skew toward early-stage companies and investments, as well as development financing programs. We are continuously working to expand the data sources and coverage of investments.
So, where did the money flow in June 2026?
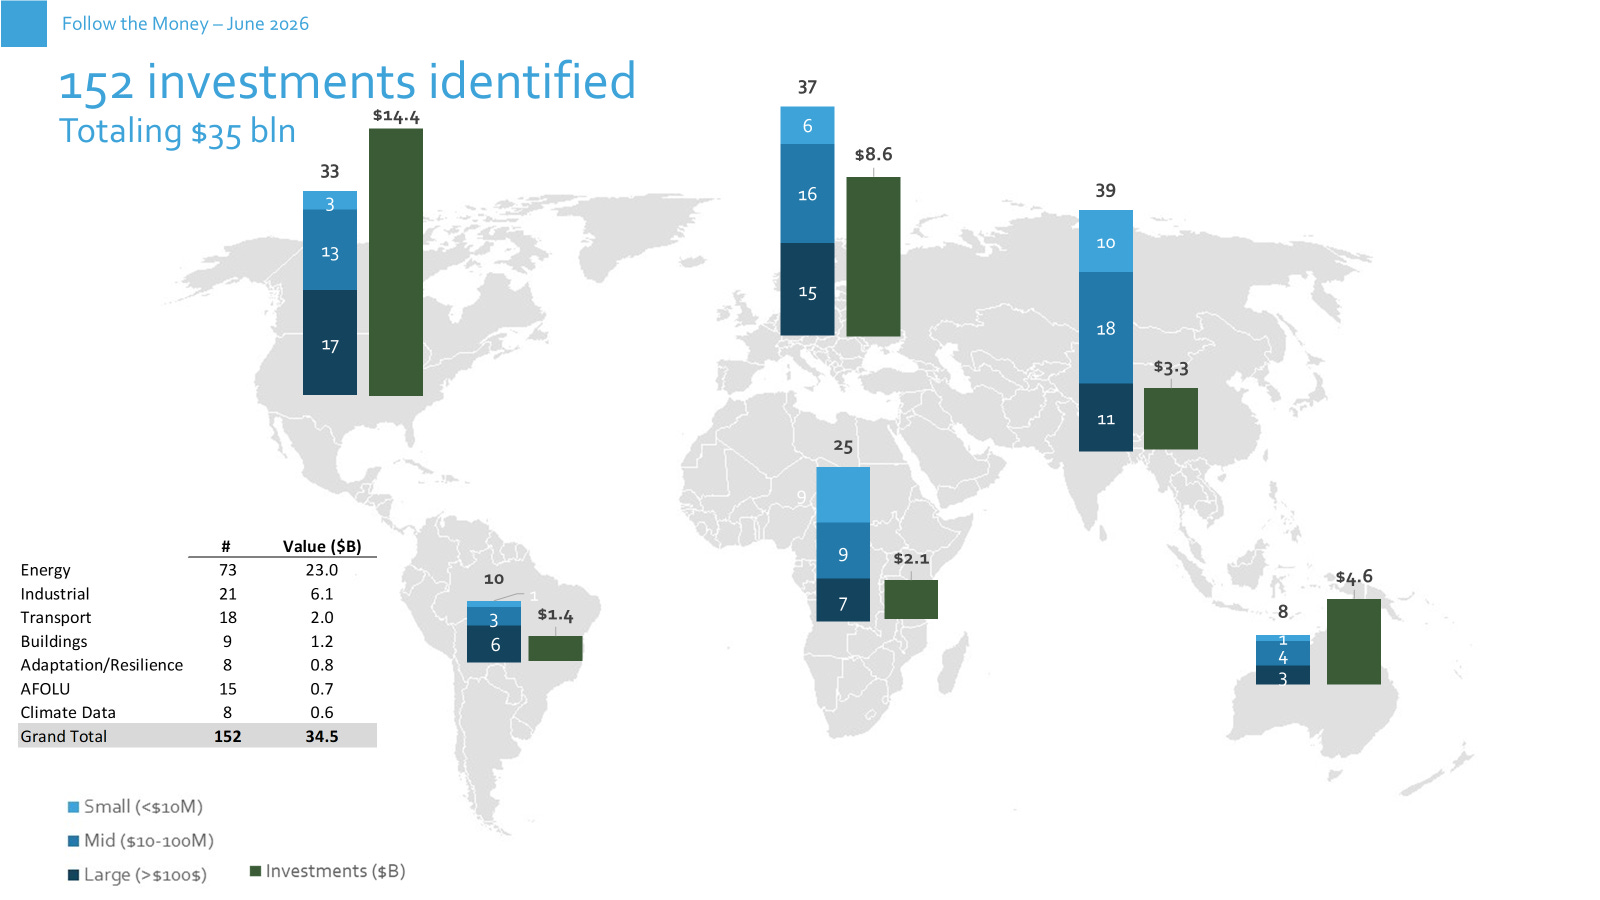
North America led the month with ~$14.4B across 33 deals, followed by Europe (~$8.6B, 37 deals) and Australia (~$4.6B, 8 deals) - the latter swollen by the federal battery tender. Asia (~$3.3B, 39 deals) led on deal count, with Africa (~$2.1B, 25 deals), Latin America & Caribbean (~$1.1B, 9 deals). Unlike May, one region - North America - clearly dominated.
Energy once again dominated, accounting for ~$23.0B across 73 deals - by far the largest category, month after month. Industrial was a clear #2 (~$6.1B, 20 deals), lifted by the EU Battery Booster, Stegra and Hybar, followed by Transport (~$2.0B), Buildings (~$1.2B), Adaptation & Resilience (~$0.8B), AFOLU (~$0.7B) and Climate Data (~$0.6B). Buildings and adaptation remained structurally undercapitalized.
The public markets reopened. After a prolonged clean-tech IPO drought, June saw ERock (Enchanted Rock) (~$600M, NYSE), Lime (~$167M, Nasdaq) and Standard Nuclear (~$383M, filed) reopen the exit window, alongside China’s Zhongke Fuhai (中科富海) (~$139M pre-IPO). The reception was selective - Deep Fission priced below plan and undersubscribed.
Public and development finance anchored the market at scale. Multilateral institutions and government programmes again supported well over $10B - from Australia’s $3.9B battery tender and the EU’s $1.73B battery facility to the UK’s low-carbon-fuels fund, Morocco’s $400M World Bank risk-finance programme and a wide range of MDB/DFI infrastructure, adaptation and on-lending facilities across Africa, Asia and Latin America. Project finance ($10.8B) and government programmes ($6.3B) together drove over 52% of the month; venture capital was just ~$2.5B.
Let’s now dive deeper into 2026 watchlist themes (please refer to our December perspective for more details) and across regions to highlight technologies with real scaling potential over the next 3-5 years.
Which (of our 2026) themes were most strongly visible in June?
In North America, capital concentrated in dispatchable, capital-heavy power for the AI build-out. Fusion led: Helion Energy raised a $465M Series G at a ~$15.5B valuation (Thrive Capital), against a contract to deliver 50 MW to Microsoft by 2028, while Thea Energy closed a $100M Series B for its planar-coil stellarator. On geothermal, Endurance Energy raised $54M (Founders Fund) for subsea baseload. The policy signal was even larger: the DOE’s $17.5B American Nuclear Supply Chain Loans will finance long-lead components for 10 AP1000 reactors (note: this amount is not included in the month total). The rest of the world kept focusing on the cheapest electrons - India’s Avaada Group (3 projects: Bikaner FDRE, Rajasthan, Gujarat) ($950M firm-and-dispatchable solar), Australia’s $3.9B battery tender, and utility-scale solar-plus-storage across every emerging market. Interestingly, June highlighted also strong investments in solar and batteries in the US, incl. Darden Project. One amendment: China has now entered the frontier, with four June fusion/SMR rounds (Xinghe Fusion / Star Nucleus Fusion (星核聚变), Beta Fusion - CATL’s first fusion bet - Juhe Fusion, Weilan Zhidian / Blue Fulcrum.
The “cheap batteries + localized electrification” thesis kept widening across road, rooftop and street. Solar, wind, battery and storage deals were ~$21.9B (64% of the month). The household and mobility layer stood out: NSW’s Home Energy Saver Program (NSW) ($368M) financed residential solar, batteries and heat pumps; SolarSquare ($53M) has served ~50,000 Indian homes; Solar Landscape ($125M) turns U.S. warehouse roofs into community solar; Spiro ($270M) is scaling e-motorbikes and battery swapping across seven African markets; and Lime ($167M) took shared e-bikes public.
June produced the year’s best counterexample and its clearest confirmation at once. Stegra’s $1.6B close - a Wallenberg-led equity consortium stacked over a fully approving lender group - shows first-of-a-kind heavy industry gets financed when the capital stack is engineered, not stretched. Hybar ($1.1B debt+equity) and Hygenco Green Energies ($105M across five blended tranches) echo the pattern. Yet the valley is real: Deep Fission raised only $40M against a $150M target and priced 33% below plan. Venture capital supplied just $2.5B against $11.8B of project finance - a barbell with a thinning middle.
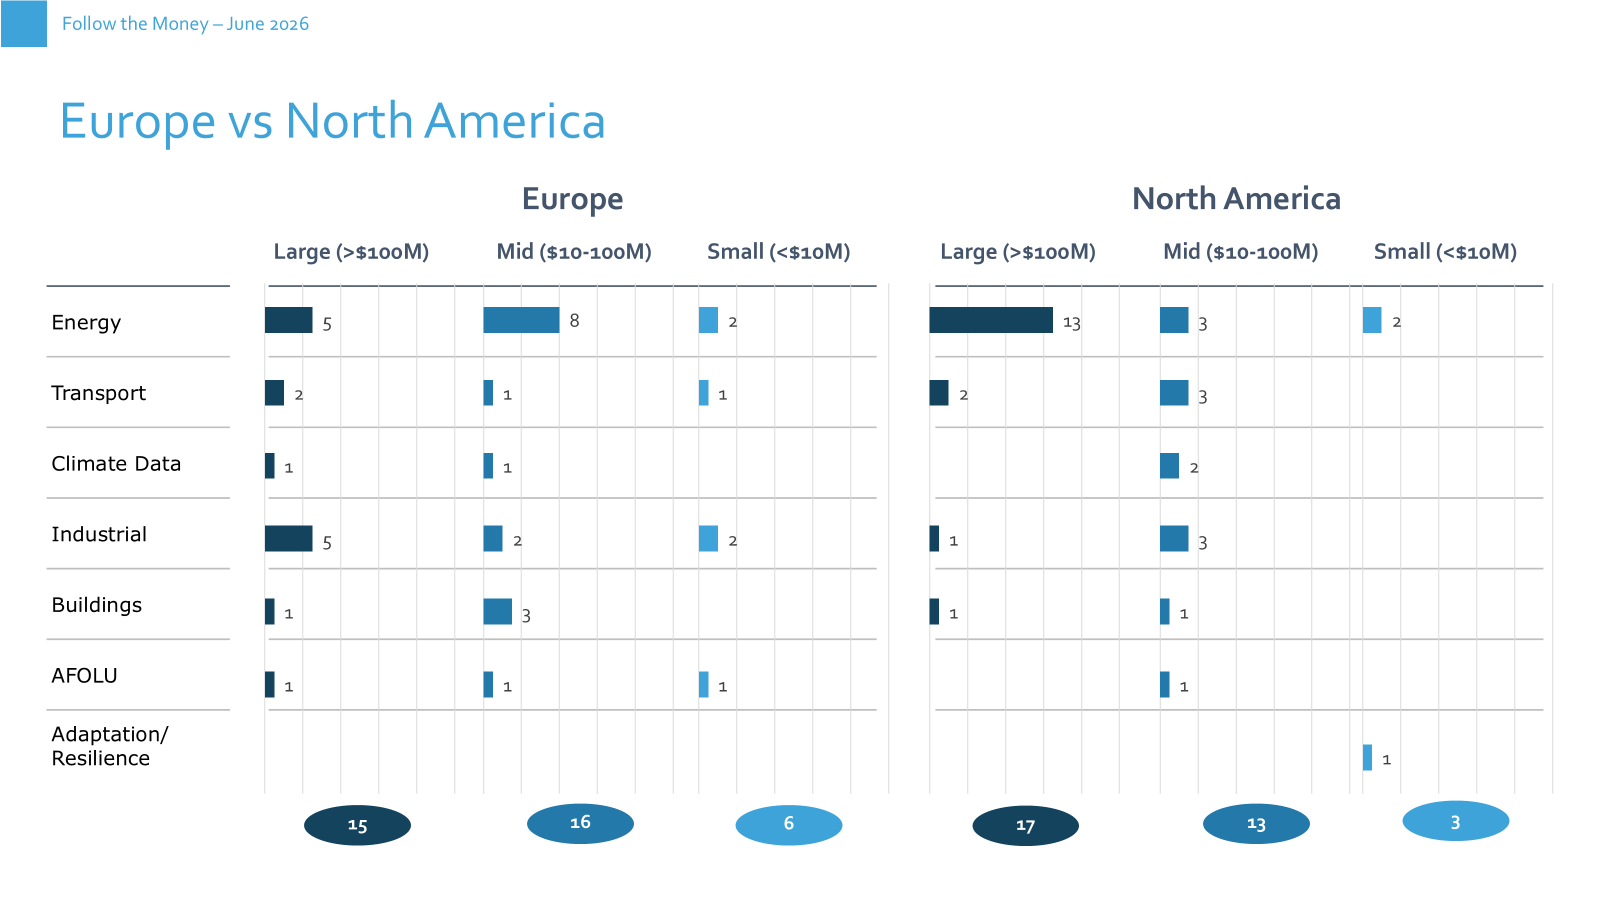
Europe recorded ~$8.6B across 37 deals - blending very large public-finance and industrial packages with one of the deepest mid-stage deep-tech layers in the world: green steel, battery manufacturing, SAR intelligence, AI-for-materials, fusion and nature finance. Two structural anchors set the tone - the EU Battery Booster Facility and Stegra’s green-steel close - reinforcing the pattern of European public finance underwriting deployment while private capital concentrates on first-of-a-kind technology.
Selected June financings:
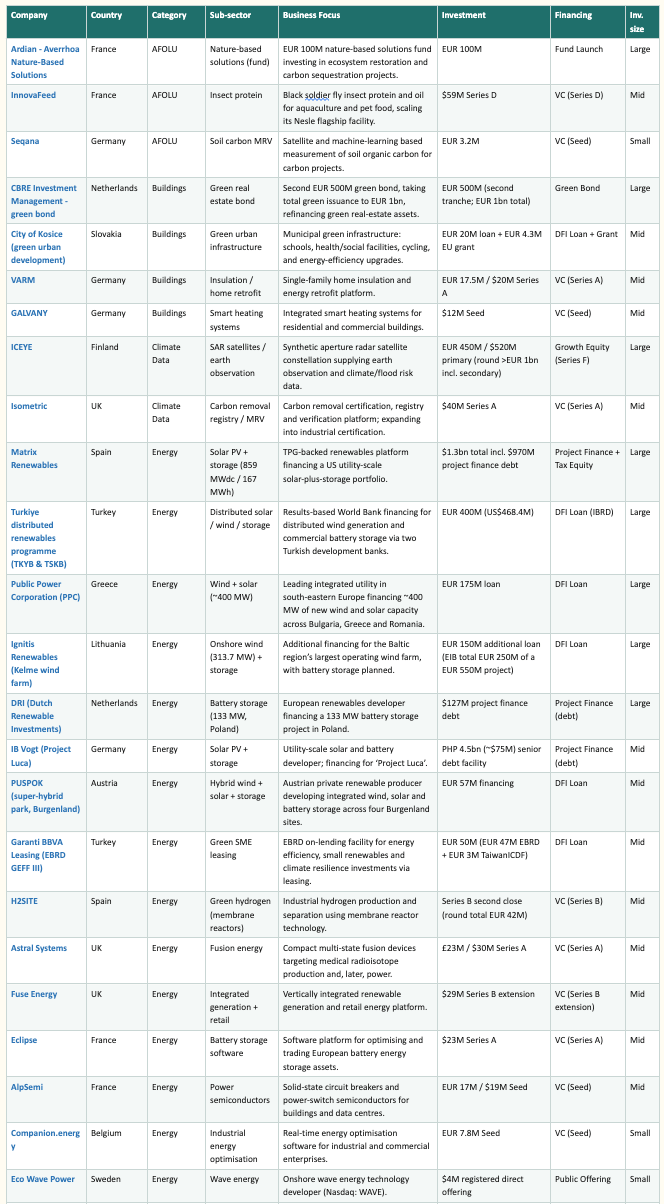
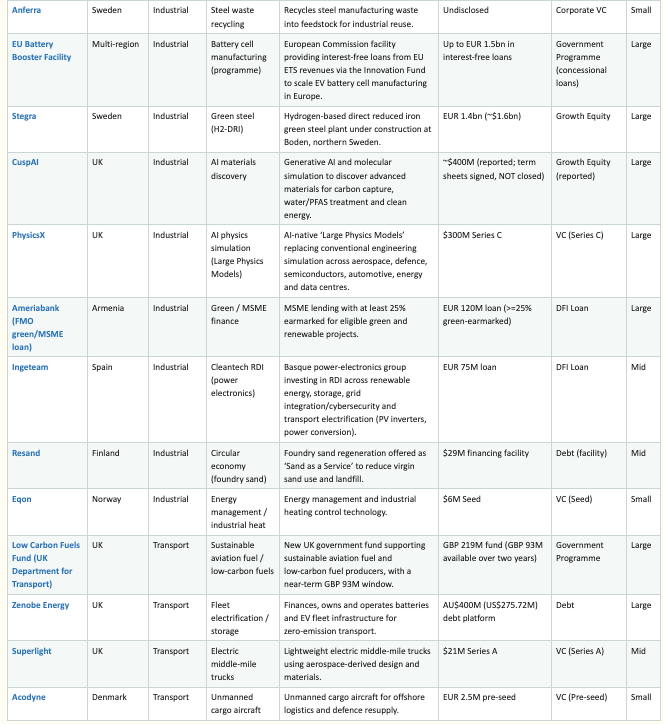
EU Battery Booster Facility (Multi-region) - $1.73B European Commission facility providing interest-free Innovation Fund loans (from EU ETS revenues) to scale EV battery-cell manufacturing in Europe.
Stegra (Sweden) - $1.60B green-steel financing close (June 24; Wallenberg-led equity over an approving lender group); 740 MW hydrogen-DRI plant at Boden - the largest single climate equity raise of the month.
Matrix Renewables (Spain) - $970M Blackstone-backed IPP; solar-plus-storage project finance with tax equity (859 MWdc / 167 MWh).
CBRE Investment Management - green bond (Netherlands) - $580M green real-estate bond financing lower-carbon commercial buildings.
ICEYE (Finland) - $520M primary growth round (General Atlantic lead) taking the synthetic-aperture-radar operator past a €10B valuation; all-weather flood/disaster monitoring under parametric climate insurance.
Turkiye distributed renewables programme (TKYB & TSKB) (Turkey) - $468M World Bank (IBRD) loan for distributed solar, wind and storage.
CuspAI (UK) - $400M generative-AI + molecular simulation for carbon-capture, PFAS and clean-energy materials (Bezos Expeditions, Kleiner Perkins) - reported term-sheet-signed, not yet closed.
PhysicsX (UK) - $300M “Large Physics Models” replacing engineering simulation across aerospace, defence and energy (Temasek lead).
Low Carbon Fuels Fund (UK Department for Transport) (UK) - $293M UK government programme for sustainable aviation fuel and low-carbon fuels.
Zenobe Energy (UK) - $275.7M finances and operates batteries and EV-fleet infrastructure for zero-emission transport.
Ardian - Averrhoa Nature-Based Solutions (France) - $114M €100M nature-based-solutions fund for ecosystem restoration and carbon sequestration (anchored by Société Générale).
InnovaFeed (France) - $58M black-soldier-fly protein and oil for aquaculture and pet food, scaling its Nesle flagship (Creadev, ADM, QIA).
Isometric (UK) - $40M carbon-removal certification, registry and MRV platform expanding into industrial certification (Lowercarbon, Plural).
Astral Systems (UK) - $30M compact multi-state fusion devices targeting medical radioisotopes first, power later (Mercia lead).
Fuse Energy (UK) - $29M vertically integrated renewable generation-and-retail platform (Series B extension).
Resand (Finland) - $29M “Sand as a Service” foundry-sand regeneration cutting virgin-sand use and landfill.
Superlight (UK) - $21M aerospace-inspired lightweight electric middle-mile trucks (2150, Engine Ventures).
VARM (Germany) - $20M single-family home insulation and energy-retrofit platform (ABN AMRO Sustainable Impact, GET Fund).
GALVANY (Germany) - $12M integrated smart heating systems for residential and commercial buildings (AENU, SET Ventures).
Seqana (Germany) - $3.7M satellite + ML measurement of soil organic carbon for carbon projects.
Acodyne (Denmark) - $2.9M unmanned cargo aircraft for offshore logistics and defence resupply.
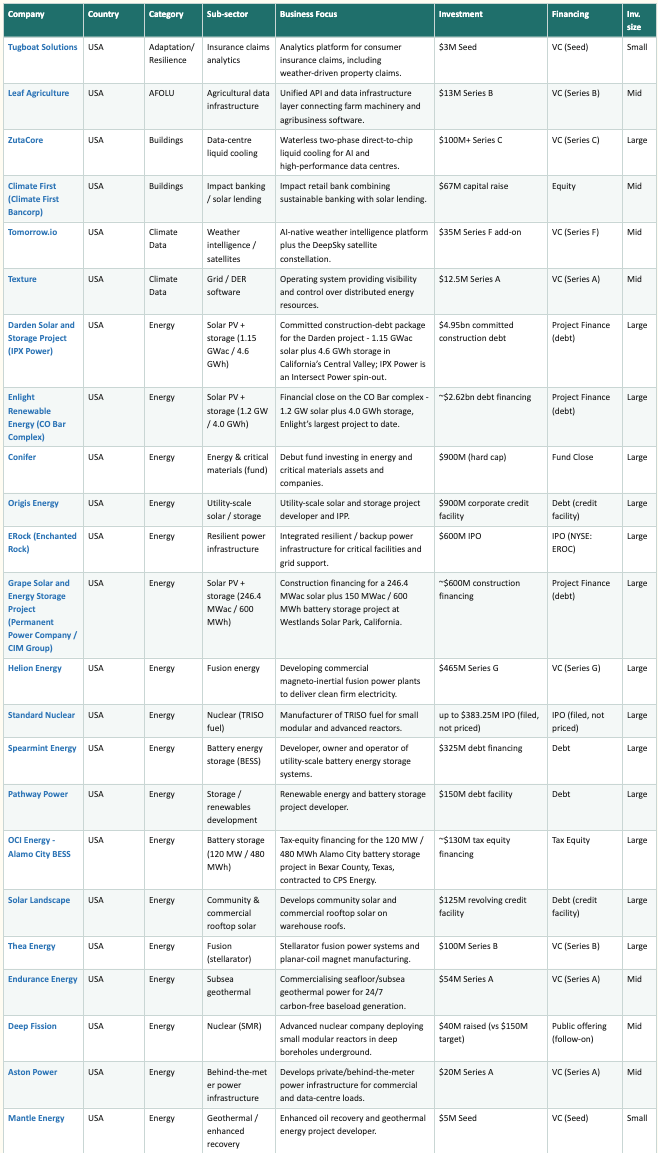
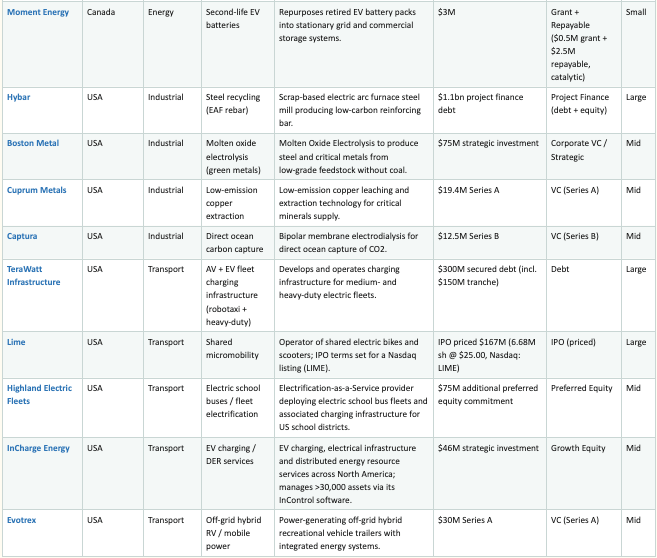
North America recorded ~$14.4B across 33 deals - the dollar leader and the sharpest thematic concentration of the month. The defining narrative is now unmistakable: the U.S. is buying firm, dispatchable power and the infrastructure to feed AI - solar-plus-storage at utility scale, fusion, geothermal, nuclear fuel and grid/critical-materials - and, for the first time this year, taking climate companies public.
Selected June highlights:
Darden Solar and Storage Project (IPX Power) (USA) - $4.95B construction-debt package for 1.15 GWac solar + 4.6 GWh storage in California’s Central Valley (IPX Power, an Intersect Power spin-out); the month’s single largest transaction.
Enlight Renewable Energy (CO Bar Complex) (USA) - $2.62B financial close on the CO Bar complex - 1.2 GW solar + 4.0 GWh storage, Enlight’s largest project to date.
Hybar (USA) - $1.10B scrap-based electric-arc-furnace mill producing low-carbon reinforcing bar (TPG Rise Climate, Koch among backers).
Origis Energy (USA) - $900M credit facility for utility-scale solar and storage development.
ERock (Enchanted Rock) (USA) - $600M NYSE listing (EROC) for resilient backup-power infrastructure (~$4.7B implied) - the month’s largest equity event and a signal the IPO window has reopened.
Grape Solar and Energy Storage Project (Permanent Power Company / CIM Group) (USA) - $600M construction financing for 246.4 MWac solar + 600 MWh storage.
Helion Energy (USA) - $465M Series G at ~$15.5B (Thrive Capital); magneto-inertial fusion with a Microsoft offtake - the largest fusion round of 2026.
Standard Nuclear (USA) - $383.2M filed for a NYSE listing (STDN) of its TRISO advanced-reactor fuel business - announced, not yet priced.
Spearmint Energy (USA) - $325M debt for grid-scale battery energy storage (BESS).
TeraWatt Infrastructure (USA) - $300M charging infrastructure for medium- and heavy-duty electric fleets.
Lime (USA) - $167M priced its Nasdaq IPO (LIME) for shared electric bikes and scooters at a ~$1.8B fully diluted valuation.
Solar Landscape (USA) - $125M community and commercial rooftop solar on U.S. warehouse roofs.
Thea Energy (USA) - $100M planar-coil stellarator fusion; magnet manufacturing as the differentiator.
ZutaCore (USA) - $100M waterless two-phase direct-to-chip liquid cooling for AI data centres (Mitsubishi Electric, Samsung Ventures).
Boston Metal (USA) - $75M molten oxide electrolysis for steel and critical metals without coal (strategic capital from Tata Steel).
Highland Electric Fleets (USA) - $75M electrification-as-a-service for electric school-bus fleets (Galvanize follow-on).
Climate First (Climate First Bancorp) (USA) - $67M impact retail bank built around solar lending (Wellington, AllianceBernstein).
Endurance Energy (USA) - $54M subsea/seafloor geothermal for 24/7 carbon-free baseload (Founders Fund lead).
InCharge Energy (USA) - $46M EV charging, electrical infrastructure and DER services across 30,000+ assets (S2G, QIC).
Deep Fission (USA) - $40M SMRs in deep boreholes; a public offering that priced below plan and undersubscribed - a caution signal.
Tomorrow.io (USA) - $35M AI-native weather intelligence plus the DeepSky satellite constellation - climate data with a direct adaptation use case.
Evotrex (USA) - $30M power-generating off-grid hybrid RV trailers (Anker among backers).
Cuprum Metals (USA) - $19.4M low-emission copper leaching/extraction for critical-minerals supply (Lundin, BHP Ventures).
Leaf Agriculture (USA) - $13M API and data layer connecting farm machinery and agribusiness software (Leaps by Bayer).
Mantle Energy (USA) - $5M enhanced-recovery and geothermal project development.
Moment Energy (Canada) - $3M second-life EV batteries repurposed into stationary storage (catalytic grant + repayable).
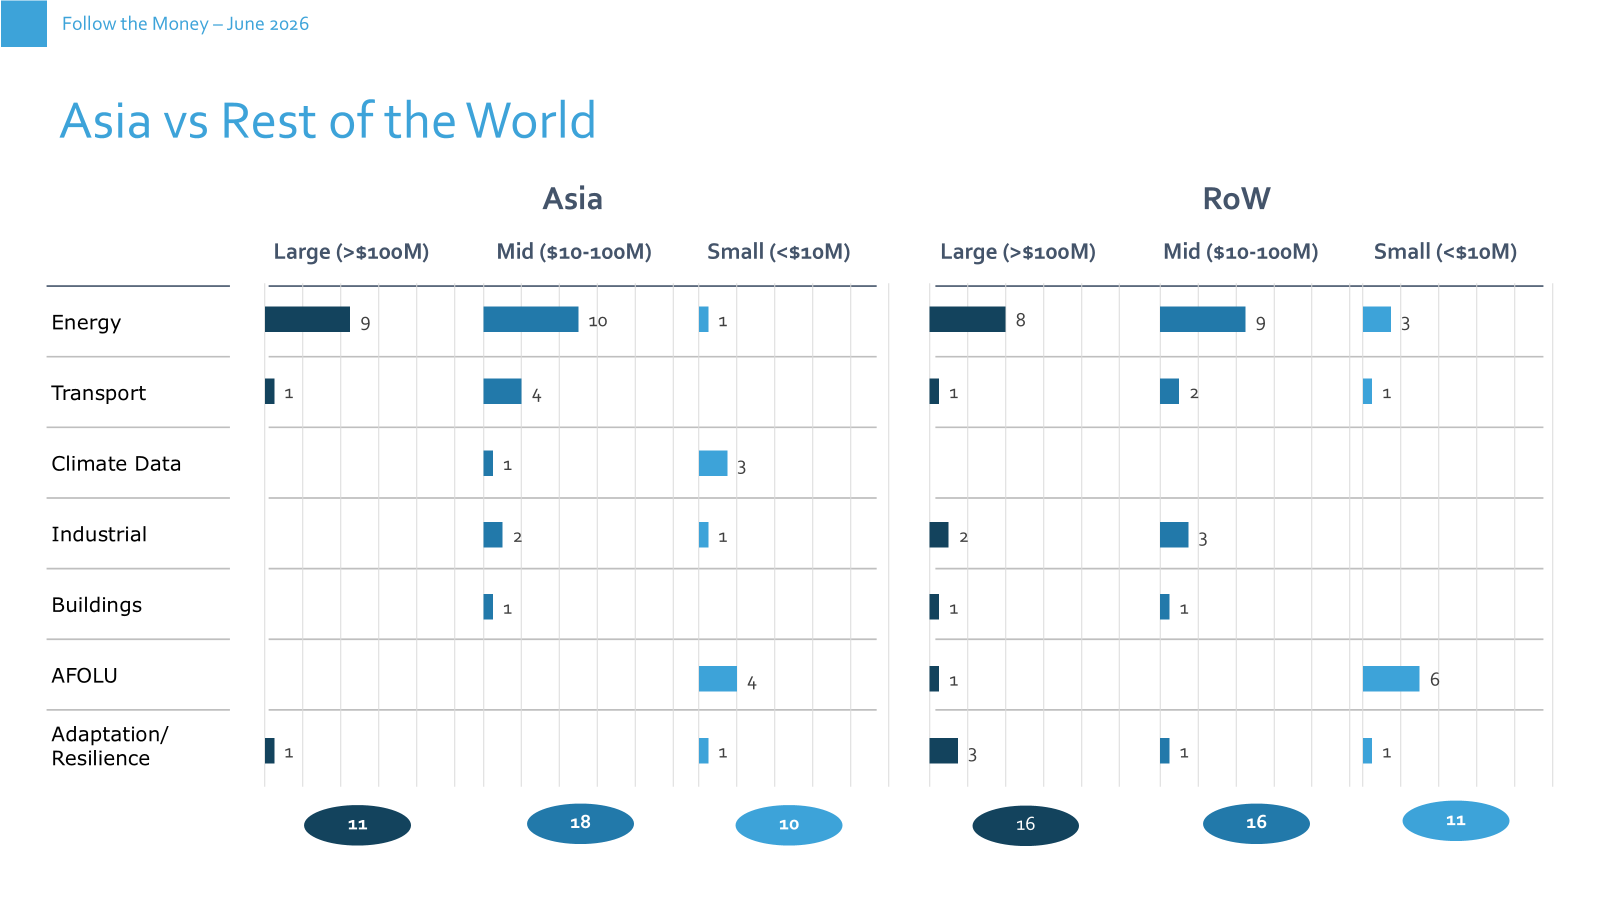
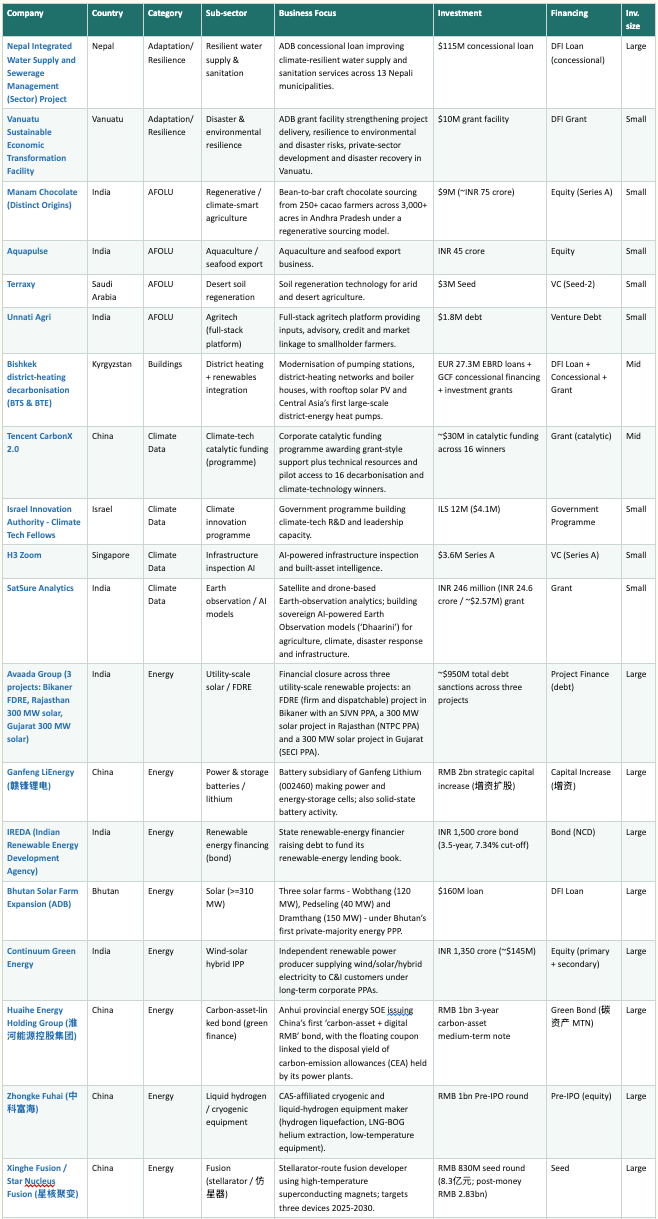
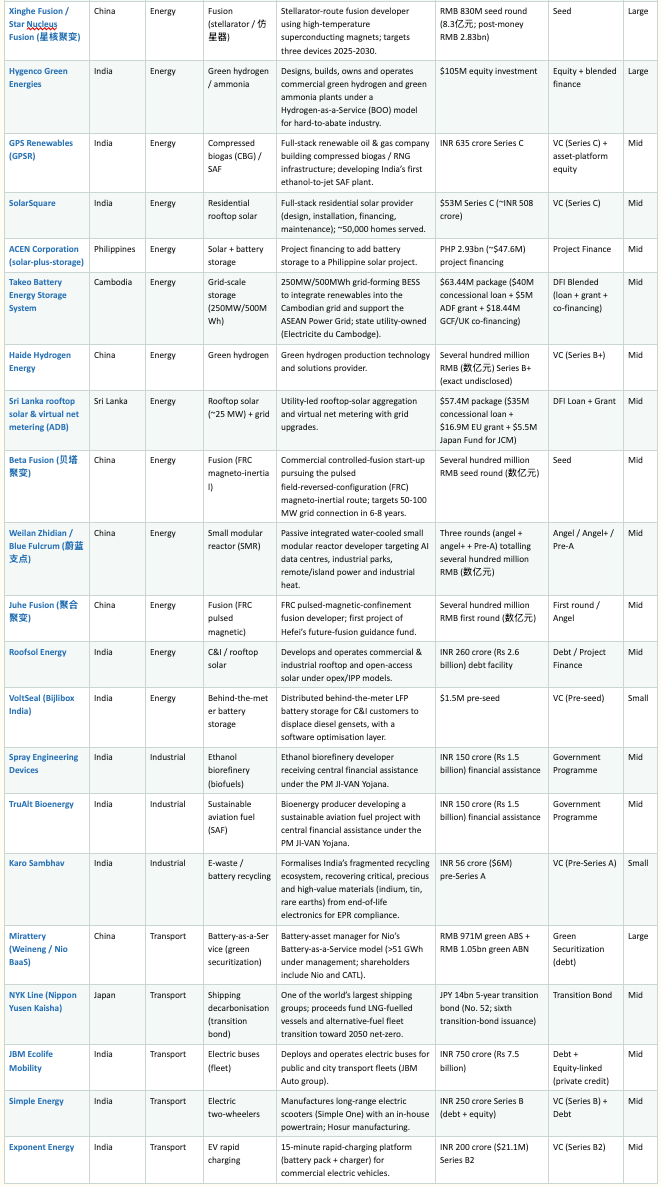
Asia-Pacific recorded ~$3.3B across 39 deals - the deal-count leader with the smallest average cheque. India dominated the renewables, hydrogen and green-financing long tail, while China anchored an unexpected fusion cluster plus battery and grid rounds.
Key June highlights from Asia:
Avaada Group (3 projects: Bikaner FDRE, Rajasthan 300 MW solar, Gujarat 300 MW solar) (India) - $950M financial close across three utility-scale projects including a firm-and-dispatchable (FDRE) project in Bikaner - India now procuring shaped, firm renewable power.
Mirattery (Weineng / Nio BaaS) (China) - $281M green securitisation against Nio’s Battery-as-a-Service fleet (two instruments: ~$135M ABS + ~$146M ABN).
Ganfeng LiEnergy (赣锋锂电) (China) - $278M capital increase into Ganfeng’s battery unit from Chinese bank AICs; power/storage cells and solid-state activity.
IREDA (Indian Renewable Energy Development Agency) (India) - $161M Indian Renewable Energy Development Agency non-convertible-debenture bond for renewables financing.
Bhutan Solar Farm Expansion (ADB) (Bhutan) - $160M ADB loan for three solar farms under Bhutan’s first private-majority energy PPP.
Continuum Green Energy (India) - $145M wind/solar/hybrid IPP for C&I corporate PPAs (Chubu Electric strategic position).
Huaihe Energy Holding Group (淮河能源控股集团) (China) - $139M carbon-asset-linked green bond (MTN) from a Chinese energy group.
Zhongke Fuhai (中科富海) (China) - $139M CAS-affiliated cryogenic and liquid-hydrogen equipment maker (pre-IPO; Guoke Capital).
Hygenco Green Energies (India) - $105M green hydrogen/ammonia under a Hydrogen-as-a-Service model - a composite of five blended tranches (IFC, Siemens, Fullerton, CIF).
Xinghe Fusion / Star Nucleus Fusion (星核聚变) (China) - $115M stellarator-route fusion with high-temperature superconducting magnets (SAIC, Shenzhen Capital among 24 investors).
NYK Line (Nippon Yusen Kaisha) (Japan) - $89M transition bond funding LNG-fuelled and alternative-fuel vessels toward 2050 net-zero - the strongest Japanese climate bond of the month.
JBM Ecolife Mobility (India) - $81M electric-bus fleet financing (debt + equity-linked).
GPS Renewables (GPSR) (India) - $66M compressed-biogas and SAF infrastructure; building India’s first ethanol-to-jet plant (PixelSky lead).
SolarSquare (India) - $53M full-stack residential rooftop solar, ~50,000 homes served (B Capital lead).
Weilan Zhidian / Blue Fulcrum (蔚蓝支点) (China) - $28M passive integrated water-cooled SMR for AI data centres and industrial heat.
Simple Energy (India) - $27M long-range electric scooters with an in-house powertrain (composite: ~$15M equity + ~$14M debt).
Exponent Energy (India) - $21.1M 15-minute rapid charging for commercial EVs (TDK Ventures co-lead).
Sri Lanka rooftop solar & virtual net metering (ADB) (Sri Lanka) - $35M ADB concessional loan for utility-led rooftop-solar aggregation and virtual net metering (~25 MW).
Manam Chocolate (Distinct Origins) (India) - $9M bean-to-bar sourcing from 250+ regenerative cacao farmers (Omnivore lead).
H3 Zoom (Singapore) - $3.6M AI infrastructure inspection and built-asset intelligence.
Terraxy (Saudi Arabia) - $3M soil-regeneration technology for arid/desert agriculture (Aramco’s Wa’ed Ventures).
SatSure Analytics (India) - $2.6M sovereign AI Earth-observation models for agriculture, climate and disaster response (IN-SPACe grant).
Unnati Agri (India) - $1.8M full-stack smallholder agritech platform (venture debt).
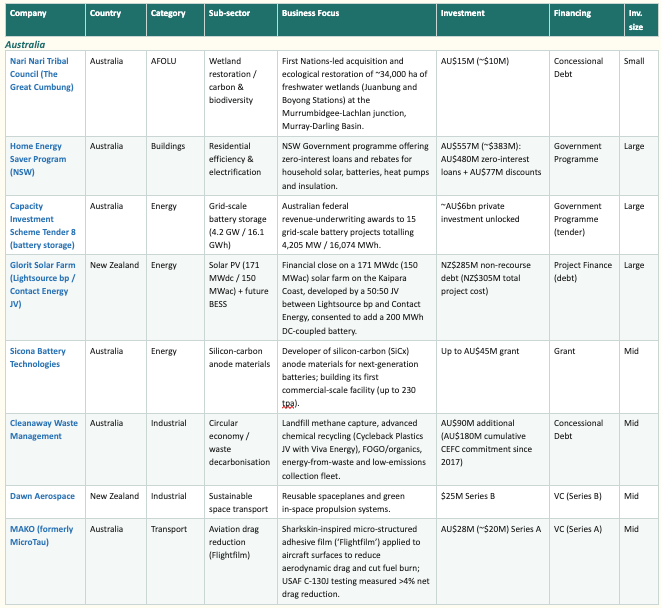
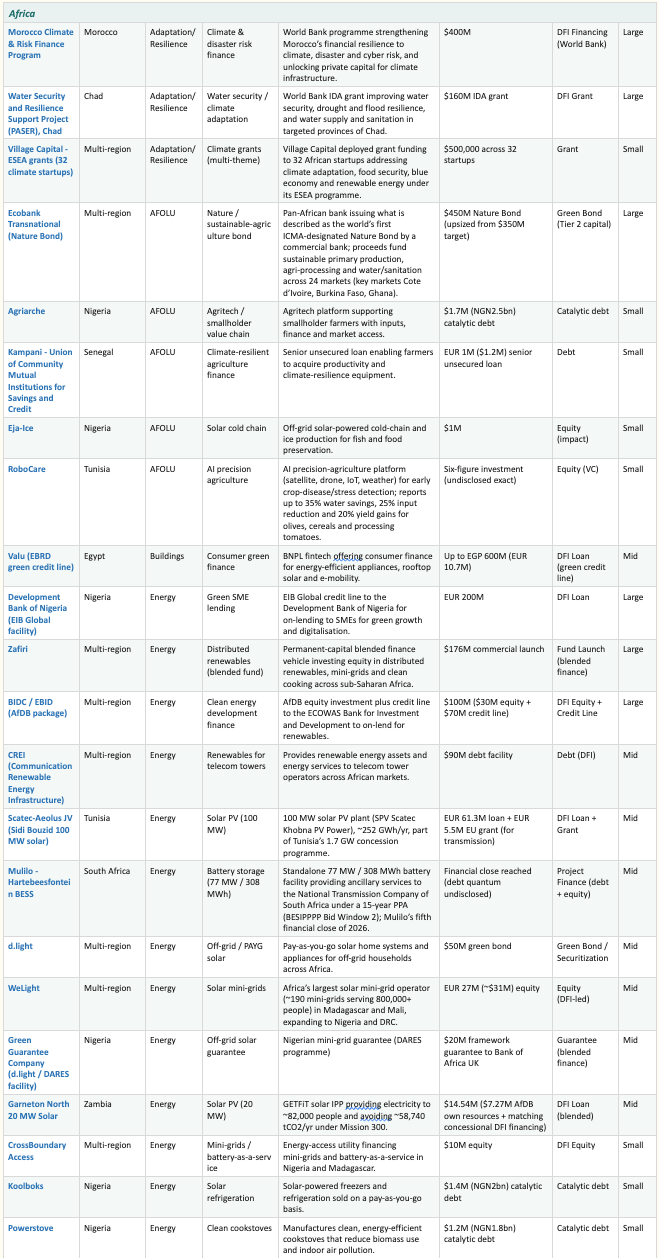
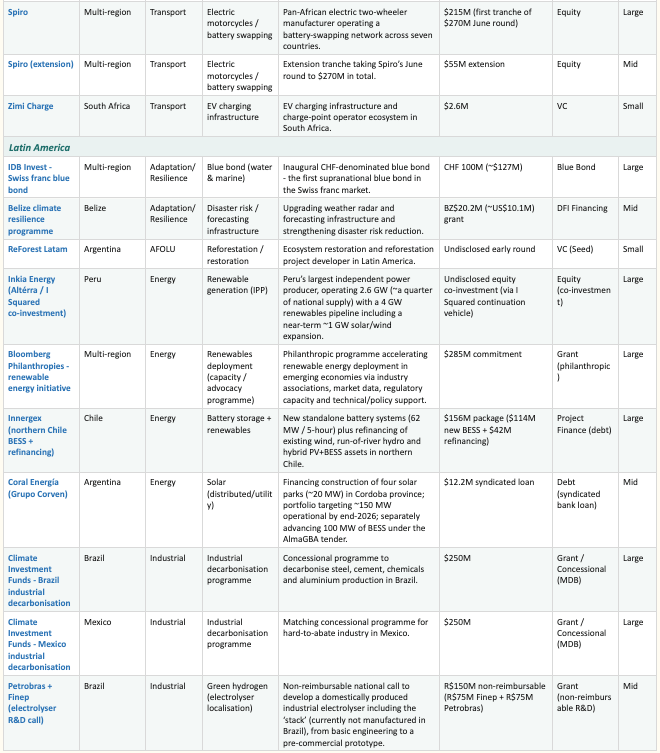
RoW (Australia, Africa, South America) recorded ~$8.1B combined across 43 deals. Australia led at ~$4.6B (8 deals, heavily federal programmes), followed by Africa (~$2.1B, 25 deals) and South America (~$1.1B, 10 deals). As in prior editions, the picture remains anchored by government programmes, MDB/DFI interventions and blended-finance structures, while commercial private capital stays concentrated in a few large closes - with mobility (Spiro) the standout private breakout.
Selected June highlights:
Capacity Investment Scheme Tender 8 (battery storage) (Australia) - $3.90B federal revenue-underwriting for 15 grid-scale battery projects (4,205 MW / 16,074 MWh) - the largest storage procurement in the tracker to date.
Ecobank Transnational (Nature Bond) (Multi-region) - $450M the first ICMA-designated Nature Bond from a commercial bank, 3.9x oversubscribed; funds sustainable production and water across 24 markets.
Morocco Climate & Risk Finance Program (Morocco) - $400M World Bank programme strengthening sovereign resilience to climate, disaster and cyber risk.
Home Energy Saver Program (NSW) (Australia) - $368M zero-interest loans and rebates for household solar, batteries, heat pumps and insulation.
Spiro (Multi-region) - $215M pan-African electric two-wheelers and battery swapping across seven markets ($215M + $55M extension; Impact Fund Denmark, Equitane, FEDA).
Inkia Energy (Altérra / I Squared co-investment) (Peru) - $300M renewable-generation IPP co-investment (Altérra, I Squared).
Climate Investment Funds - Brazil industrial decarbonisation (Brazil) - $250M concessional programme to decarbonise steel, cement, chemicals and aluminium.
Climate Investment Funds - Mexico industrial decarbonisation (Mexico) - $250M concessional programme to decarbonise heavy industry.
Zafiri (Multi-region) - $176M permanent-capital blended vehicle for distributed renewables, mini-grids and clean cooking (Mission 300).
Innergex (northern Chile BESS + refinancing) (Chile) - $156M northern Chilean battery storage plus renewables refinancing.
IDB Invest - Swiss franc blue bond (Multi-region) - $127M Swiss-franc blue bond for water and marine assets.
WeLight (Multi-region) - $31M Africa’s largest solar mini-grid operator (~190 grids, 800,000+ people), expanding to Nigeria and the DRC (IFC-led).
Development Bank of Nigeria (EIB Global facility) (Nigeria) - $229M EIB Global green-SME lending facility.
Mulilo - Hartebeesfontein BESS (South Africa) - $50M Hartebeesfontein battery storage (77 MW / 308 MWh), project finance.
d.light (Multi-region) - $50M off-grid / PAYG solar green bond / securitisation (Nigeria mini-grid guarantee separately).
MAKO (formerly MicroTau) (Australia) - $20M sharkskin-inspired drag-reduction film cutting aircraft fuel burn (>4% net drag reduction on USAF C-130J; CEFC-backed).
Sicona Battery Technologies (Australia) - $30M silicon-carbon anode materials; first commercial-scale facility (ARENA, Port Kembla siting).
Dawn Aerospace (New Zealand) - $25M reusable spaceplanes and green in-space propulsion.
Belize climate resilience programme (Belize) - $10.1M weather-radar and forecasting upgrades and early-warning systems (Caribbean Development Bank).
Zimi Charge (South Africa) - $2.6M EV charging infrastructure and charge-point-operator ecosystem in South Africa (DBSA).
Agriarche (Nigeria) - $1.7M agritech linking smallholders to inputs, finance and markets (catalytic).
RoboCare (Tunisia) - $0.5M AI precision-agriculture (satellite, drone, IoT) cutting water use up to 35% - Tunisian climate-adaptation tech.
The cleanest new signal of the month was that the public markets reopened for climate - though selectively. Whether the fusion and geothermal cheque-writing keeps climbing, whether Europe’s green-industrial FIDs keep closing after Stegra, and whether the reopened IPO window stays open through H2 will tell us how durable June’s turn really is. Adaptation remains the persistent gap: $825M, 2.4% of the month, in the hottest June on record. We will be watching whether the themes identified in December continue to deepen:
U.S.: Nuclear and Geothermal vs. Rest of World: Solar and Wind - strongly supported, now trilateral as China enters the frontier
“Solarpunk” Momentum - electrification beyond cars, powered by cheap batteries; the best-supported theme in June
Dual-Use Innovation: Climate + Defense, Supply Chain, Compute - real, but less visible in June (except for compute)
CapEx-Intensive Mid-Stage Tech and the “Valley of Death” - strongly supported, with Stegra as the template
Industrial Heat Electrification - weak in June; awaiting more traction in this space
Nature-Based Solutions for Carbon and Biodiversity - moderate; one bond carried the category
AFOLU Innovation - diverse but small-cheque
The Rise of Climate Robotics - less visible in June
Stay tuned for next month’s edition as we continue to follow the capital shaping the climate transition.