



惯性聚合 高效追踪和阅读你感兴趣的博客、新闻、科技资讯
阅读原文 在惯性聚合中打开

推荐订阅源

J
Java Code Geeks
小众软件
小众软件
博客园 - 叶小钗
宝玉的分享
宝玉的分享
博客园_首页
Hugging Face - Blog
Hugging Face - Blog
人人都是产品经理
人人都是产品经理
钛媒体:引领未来商业与生活新知
钛媒体:引领未来商业与生活新知
S
SegmentFault 最新的问题
B
Blog RSS Feed
Engineering at Meta
Engineering at Meta
N
Netflix TechBlog - Medium
Google DeepMind News
U
Unit 42
F
Fortinet All Blogs
IT之家
IT之家
Y
Y Combinator Blog
Martin Fowler
Martin Fowler
T
The Blog of Author Tim Ferriss
奇客Solidot–传递最新科技情报
奇客Solidot–传递最新科技情报
The GitHub Blog
The GitHub Blog
Stack Overflow Blog
Stack Overflow Blog
Blog — PlanetScale
Blog — PlanetScale
酷 壳 – CoolShell
酷 壳 – CoolShell

dotData

Auto Loan Delinquency at a Record: The State of Auto Finance, H1 2026 | dotData Auto Loan Charge-Off Rates: Discovering the Hidden Signals Before Losses Hit Your P&L | dotData AI-based Portfolio Monitoring for Lending: Catching the Drift After the Loan Is Booked | dotData AI Loan Approval: Why Speed Alone Fails to Reduce Auto Portfolio Losses | dotData 2026 Best AI-Powered Lending Platforms: A Due-Diligence Framework | dotData AI in Lending: Why Faster Decisions Don't Fix Roll Rates | dotData Auto Loan Pricing Model Optimization: 5 Steps to Identify Mispriced Segments | dotData Auto Loan Delinquency Rate at a 15-Year High: What Extended Terms Are Hiding in Your Loss Forecast | dotData AI-Powered Credit Decisioning Engines and Platforms: What CROs Need to Evaluate Before Buying | dotData Early Payment Default in Auto Lending: How Precision Underwriting Stops It Before Funding | dotData A Guide to Modern Auto Credit Decisioning Software | dotData Why Aging Reports Can Drive Auto Loan Charge-Off | dotData A Diagnostic Framework for Lender Protection | dotData How to Evaluate Analytics for Loan Portfolio Monitoring and Fair Lending | dotData The Hidden Profit and Risks in Auto Lending Origination | dotData How to Evaluate Lending Analytics: From Origination to Charge-Off | dotData Roll Rate Analysis in Auto Lending: Are You Missing Behavioral Risk? | dotData Why Dealer Performance Scorecards Fail in Auto Lending | dotData Why 'Glass Box' Models Win: Credit Risk Analysis Software | dotData Automated Loan Decisioning: Why Static Scoring Breaks | dotData Why Traditional Credit Scoring Fails to Predict a New Wave of Defaults | dotData Building a Modern Auto Credit Decisioning Engine in 2026 | dotData When Generative AI & RAG Are Wrong for eCommerce | dotData The Paradox of In-Store and Online Retail Return Rate | dotData Detecting Straw Borrowers in Auto Lending with Advanced Analytics | dotData
Why Most Credit Decisioning Evaluations Fail | dotData
https://www.facebook.com/dotData · 2026-09-16 · via dotData

Auto loan balances reached $1.69 trillion in Q1 2026, and lenders originated $182.1 billion in new paper in that quarter alone. Each of those originations was priced by a system somebody bought.

Yet, when auto lending risk leaders set out to modernize their risk architecture, the evaluation process itself is often broken from the start.

Most evaluation matrices place four fundamentally different products into a single comparison, apply the same criteria to all of them, and produce a ranking that means nothing. To address this, we created a new interactive resource to help you cut through the noise in your procurement process.

The Problem: One Label, Four Purchases

How do you fix a broken evaluation process? Stop comparing origination fraud filters, decisioning engines, BI dashboards, and Signal Intelligence platforms. They’re often pitched and reviewed under a single category name, but they solve entirely different problems.
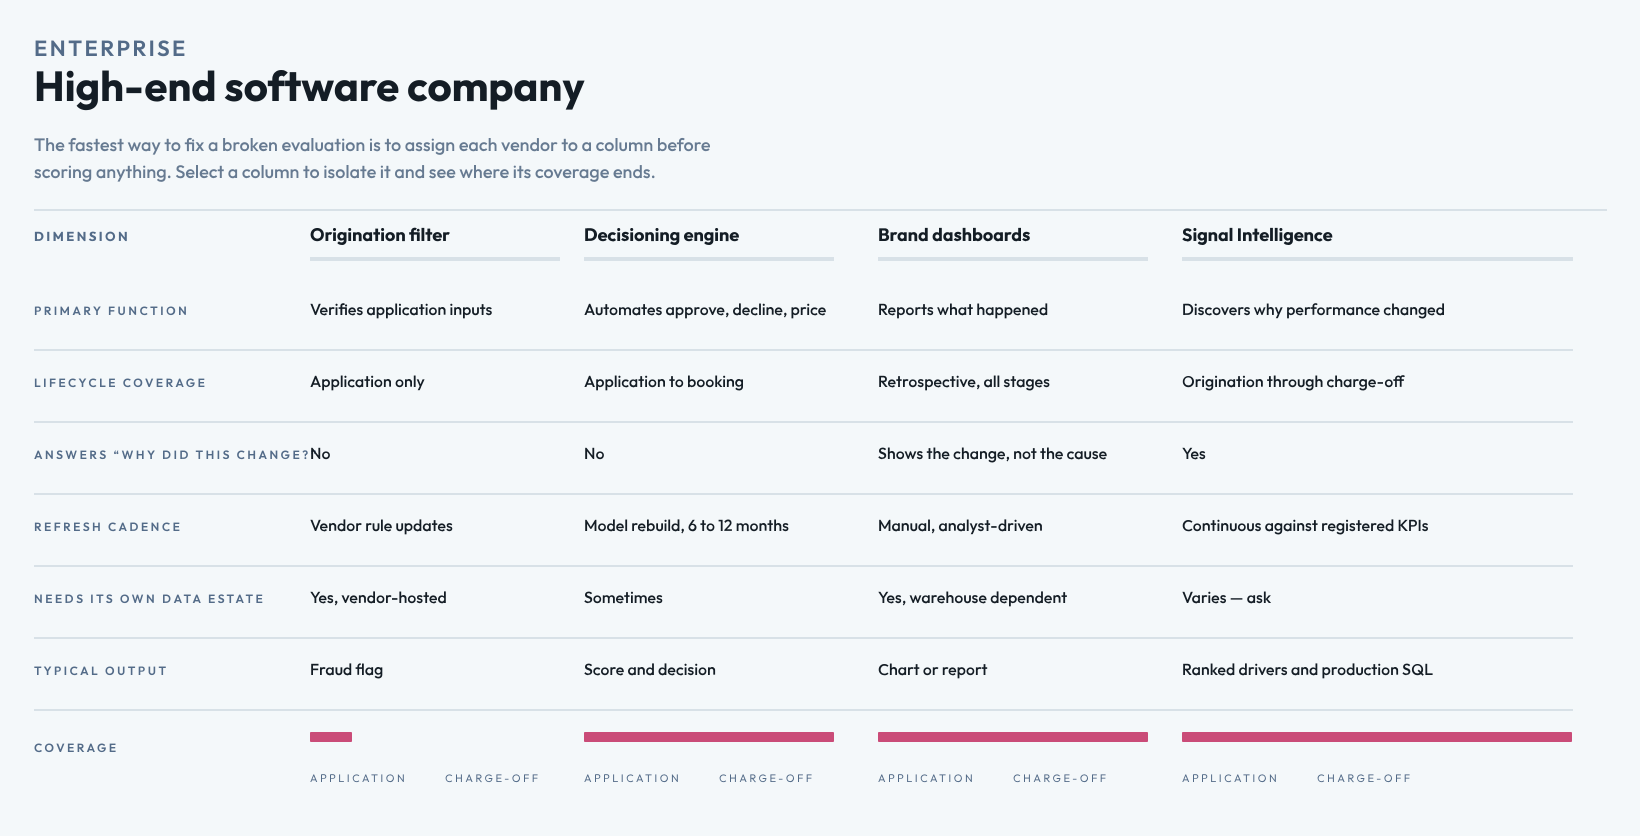
High-end software company

A decisioning engine optimizes a model against a portfolio-level objective—automating the approve, decline, and price decisions. It has no mechanism to explain why a segment within that portfolio began deteriorating. Explaining deterioration is not an optimization problem.

Conversely, BI dashboards make deterioration visible, but they cannot identify the combination of variables that produced it. This leaves your data science team with a multi-week manual investigation. Scoring a BI dashboard against a decisioning engine produces a winner by accident. Our guide helps you assign each vendor to their proper column before you score anything.

Hidden Risks in the Modern Portfolio

Standard demonstrations fail to capture the realities of the modern auto lending market. A vendor demonstration built on portfolio-wide averages is running on data where populations cancel each other out.

Consider the realities risk teams are facing today:
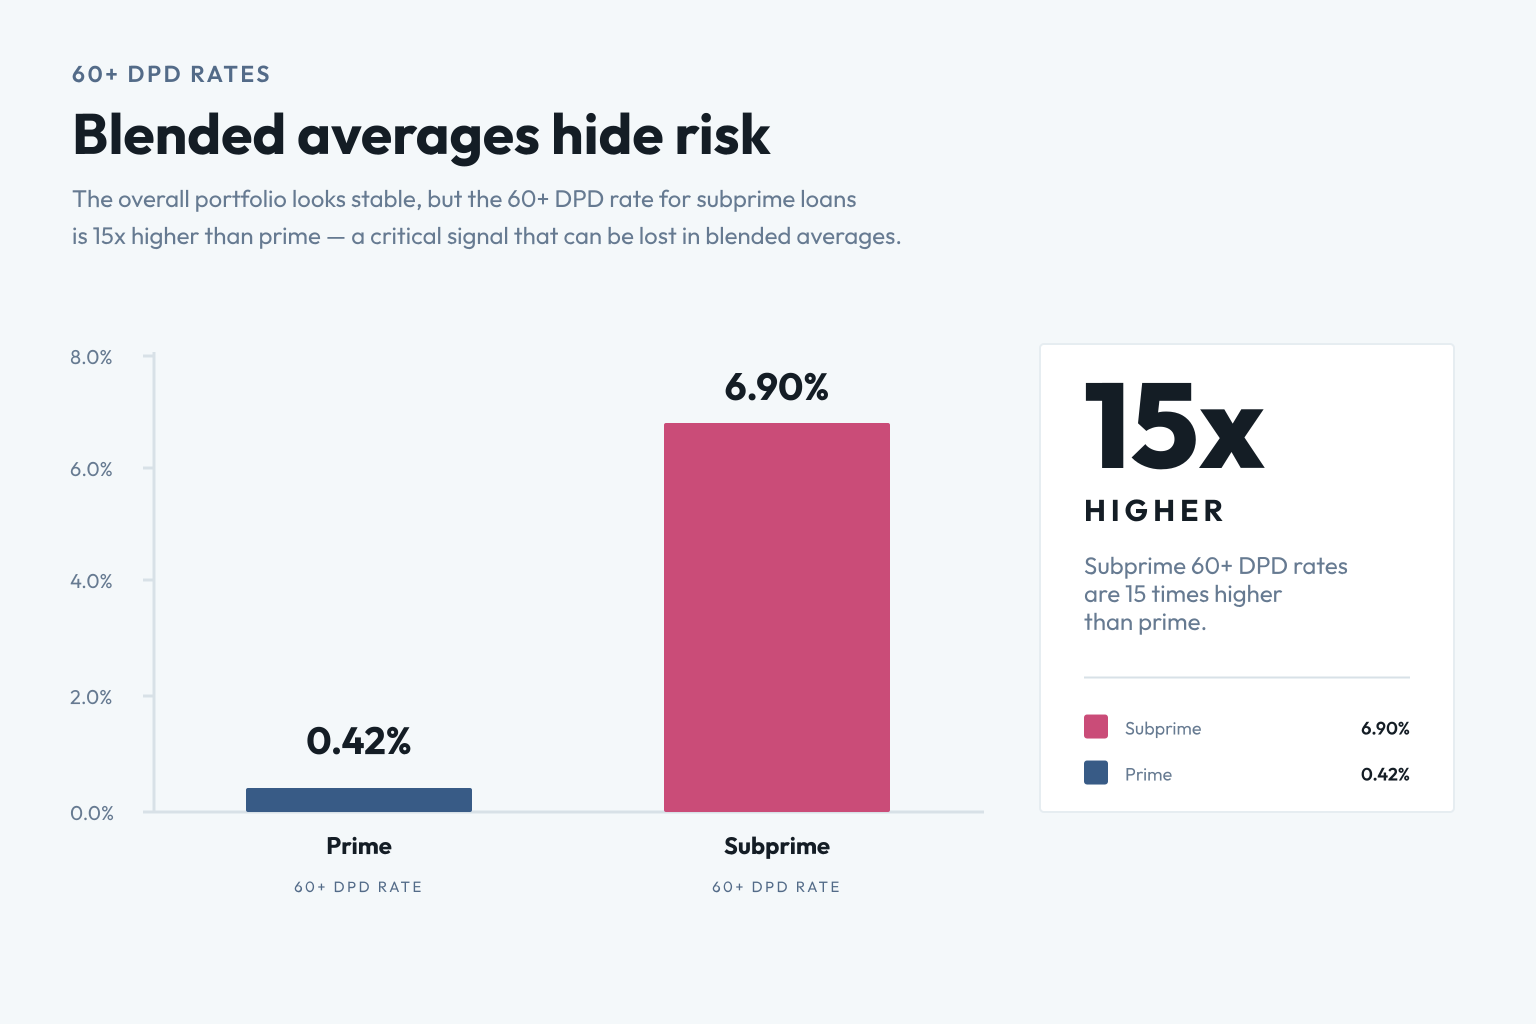
  • Blended averages hide risk: Prime 60+ DPD sits at 0.42% while subprime hit 6.90% in January 2026—a record in an index dating to the early 1990s.
  • The obligation moved, not the borrower: Average new-vehicle payments reached $770 in Q1 2026, with nearly 19% of new-vehicle loans carrying a payment of $1,000 or more. A system that cannot construct payment-to-cash-flow relationships from raw relational data is accurately scoring the wrong metrics.
  • Loss severity is set at origination: In Q2 2026, 29.6% of new-vehicle trade-ins carried negative equity, with an average deficit of $6,884. Loss severity is fixed months before the account appears in a delinquency report.
Blended averages hide risk

The 12 Questions That Decide It

When evaluating vendors, standard questionnaires often consist of baseline hygiene checks. In our buyer’s guide, we’ve isolated the 12 critical questions where a weak answer is diagnostic, not just disappointing.

These are the questions you need to ask live, where a marketing team can’t edit the answers. For example:
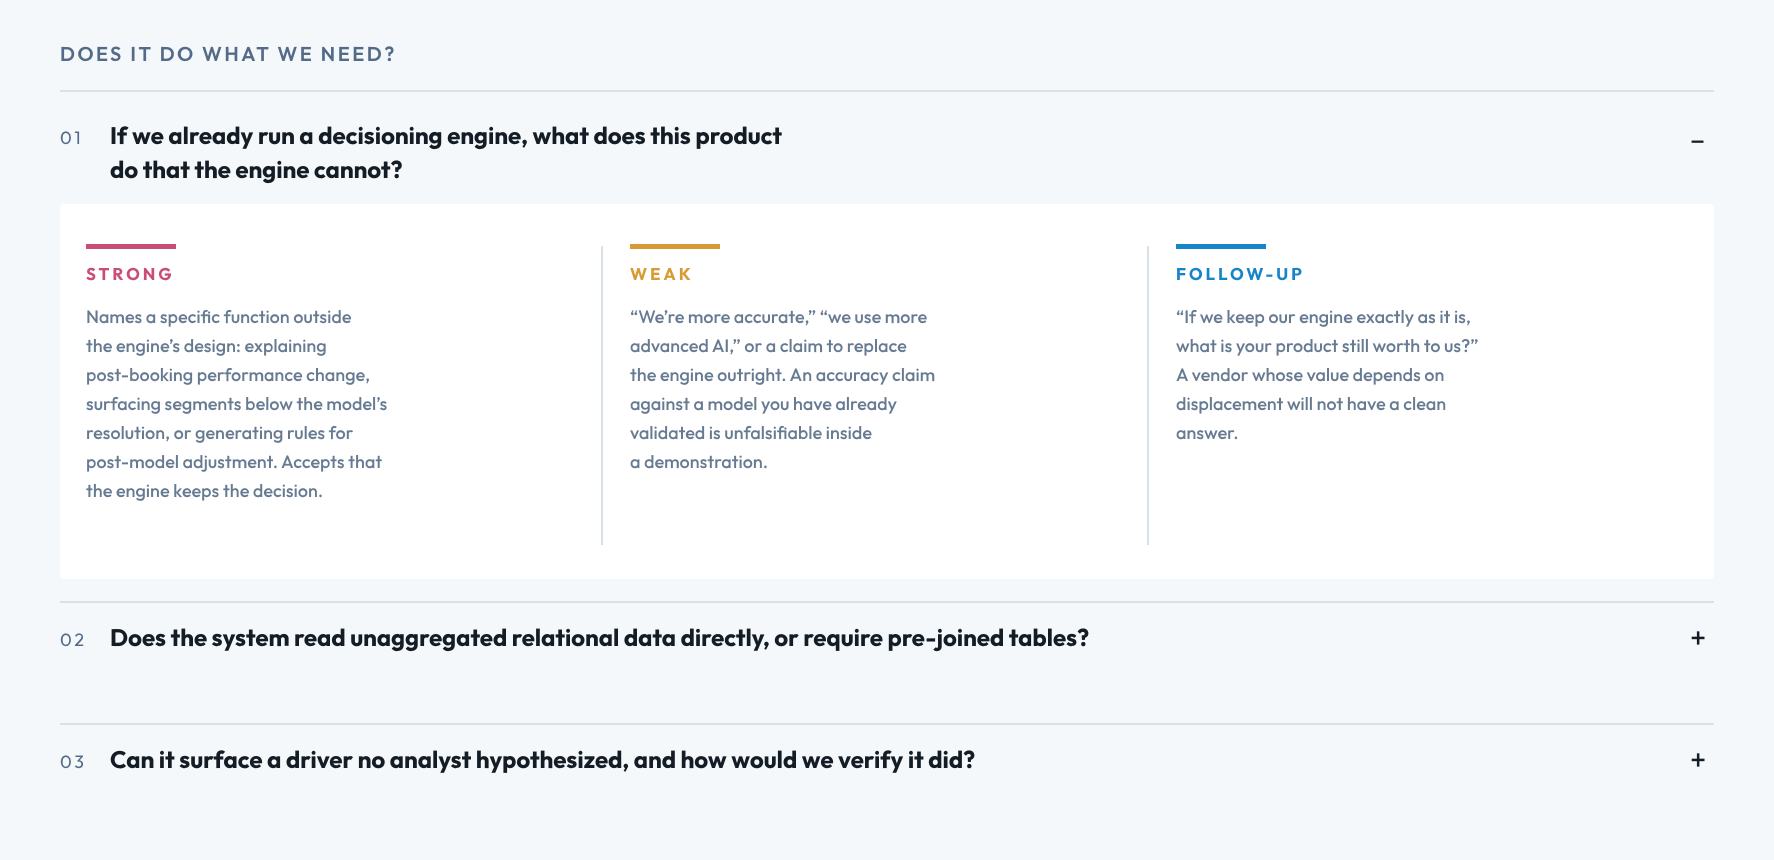
  • Does the platform read raw relational tables, or require pre-flattening? If a vendor says, “We work with your existing warehouse tables,” that often means your analysts do the joining—relocating the work rather than removing it.
  • Can we defend the output? Does the software produce reasons tied to identifiable attributes at the individual decision level, in language that maps onto an adverse action notice? Or does it offer SHAP values and feature importance charts as if they were the same thing?
  • Is the derivation transparent? Does it emit the derivation itself (SQL, code) so your validation team can recompute a variable independently, or is it a fluent description of a black box?
Questions to ask when evaluating

Fix Your Evaluation Process Today

Before your organization invests in the next phase of its credit decisioning architecture, make sure you’re asking the right questions and evaluating the right categories.

Access our interactive buyer’s guide below and create your own downloadable custom configuration process.
dotData

dotData Automated Feature Engineering powers our full-cycle data science automation platform to help enterprise organizations accelerate ML and AI projects and deliver more business value by automating the hardest part of the data science and AI process - feature engineering and operationalization. Learn more at dotdata.com, and join us on Twitter and LinkedIn.