China retains its unrivalled position as the dominant force in the global mobile gaming industry, capturing a staggering 31.7% share of the worldwide mobile games revenue, all generated domestically. That’s according to the latest research from video games market research firm Niko Partners.
China is expected to reach $57 billion in gaming revenues by 2027. That figure includes mobile, PC and console games. Game companies in the country now account for 47% of mobile gaming revenues and 39% of PC revenues globally.
“Chinese game companies are growing internationally, and they are making bold investments at higher rates than ever,” said Lisa Hanson, CEO and founder of Niko Partners. “PC games revenue generated overseas by Chinese owned companies rose by 22% in 2022 and is expected to grow by a 13.8% CAGR through 2027 – which is higher than the domestic growth rate by a significant margin. You must get to know Chinese developers and publishers both in the domestic market and abroad if you are serious about the global games industry.”
- Advertisement -
Is your privacy opt-in rate costing you $525,000 a year?
The gap between a 65% and 90%+ privacy opt-in rate can mean $525,000 in lost revenue annually for a 100K DAU app — and most teams have no idea where they stand.
This guide breaks down the true cost of consent debt, why the average app sits at just 80% opt-in, and the exact tactics top performers use to consistently hit 90%+: prompt timing, banner design, vendor list optimization, and more.
China mobile gaming revenues projected to grow
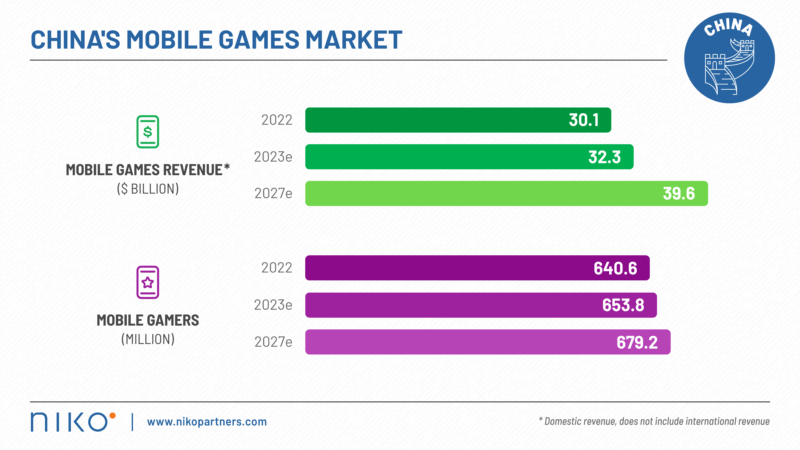
Source: Niko Partners
Despite a declining population, the country is projected to reach a whopping 730 million gamers. In terms of revenue distribution, mobile games account for 66%, PC games for 31%, and console games for 3%.
In 2022, Tencent and NetEase dominated the domestic PC and mobile games revenue, capturing a combined market share of 61%.
However, their dominance weakened compared to 2021 due to underperformance of existing titles and a lack of new game launches. This suggests that other competitors are gaining ground.
In Q1 of 2023, both companies reported positive earnings, with Tencent’s domestic game revenue growing by 10.9% year-on-year and NetEase’s total games revenue increasing by 7.6% year-on-year.
Interestingly, 42.8% of active gaming and esports content viewers in China make in-game purchases every month, compared to only 2.2% of gamers who do not watch esports or gaming content. Furthermore, gamers who engage in live streaming tend to spend, on average, 70% more per month than those who do not.
“China’s market can be tough for domestic and foreign companies, but the country remains the #1 market globally for games revenue and the number of gamers, and cannot be ignored,” stated Lisa Hanson, CEO and founder of Niko Partners. “Game companies are successful in China, both through officially approved releases on app stores and unlicensed releases through platforms such as Steam International. If we consider games published through Steam in China as if Steam were a single entity, the revenue generated from the platform would make surpass all other publishers in the country except for Tencent and NetEase.”
此内容由惯性聚合(RSS阅读器)自动聚合整理,仅供阅读参考。 原文来自 — 版权归原作者所有。