







When it rains, it pours. That seems to be the challenge India is facing on the balance of payments (BoP) front. While the situation remains manageable given the economy’s inherent strengths and India’s historical resilience, the pressures building on the BoP suggest that solutions may need to go beyond curbing gold imports and crude oil consumption, especially if the US/Israel-Iran conflict persists and its economic fallout proves prolonged.
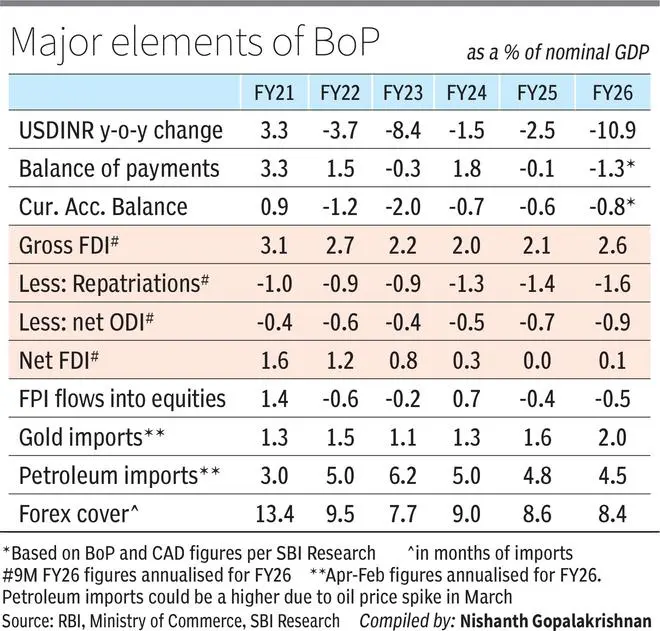
Yes, gold imports have risen sharply over the last five years, from 1.3 per cent of GDP in FY21 to around 2 per cent in FY26. Oil imports, too, have increased from 3 per cent to over 4.5 per cent of GDP. But India has faced similar — and even higher — oil-import burdens in the past, without comparable currency stress. In FY22, oil imports were close to 5 per cent of GDP, yet the rupee weakened only 3.7 per cent against the dollar, compared with the 11 per cent decline in FY26. Similarly, in FY19, when crude imports were around 5 per cent of GDP, the rupee fell about 6 per cent, far less severe than now.
The 11 per cent decline in FY26 marks the rupee’s steepest fall since FY14. But unlike FY14, when forex reserves covered only about seven months of imports, India now has reserves equivalent to over 8 months of import cover.
Compared with five years ago, India’s BoP position has deteriorated from a surplus of 3.3 per cent of GDP to a deficit of 1.33 per cent, based on FY26 BoP estimates by SBI Research.
Beyond oil & gold
A closer look suggests the biggest structural shifts lie beyond gold and petroleum imports.
Since March 2021, the rupee has depreciated 31 per cent. While incremental gold imports contributed about 0.7 percentage points of GDP to the worsening BoP, far bigger changes have emerged in capital flows. Net FDI flows have fallen from a positive 1.6 per cent of GDP in FY21 to near-flat levels now. Importantly, the decline is not due to weaker FDI inflows, which have remained between 2-3 per cent of GDP, but because of rising repatriation of capital out of India.
FDI repatriations have increased from 1 per cent of GDP in FY21 to 1.6 per cent in FY26. In six of the previous 10 fiscals, repatriations remained below 1 per cent of GDP. Except for FY21, however, they have stayed above that mark for the last three years, dragging down net FDI flows.
Net FPI equity flows have also weakened sharply, moving from a positive 1.4 per cent of GDP in FY21 to a negative 0.5 per cent in FY26. While FPI outflows were similarly negative in FY22 (-0.58 per cent), net FDI inflows at that time still stood at 1.22 per cent of GDP, compared with almost negligible levels now.
This is the core challenge confronting policy-makers. A spike in gold or oil imports can be managed in isolation. A temporary export slowdown due to tariff wars is also manageable. But when all of these occur simultaneously — alongside elevated FDI repatriations, IPO-related exits and sustained FPI outflows — the pressure becomes far more serious. It is effectively a battle on multiple fronts.
Higher valuations
In February 2024, when Whirlpool Corporation sold a 24 per cent stake in its Indian subsidiary, its CEO remarked: “When you have a business trading at 50 times multiple when your own company trades a lot lower, it’s an asset arbitrage.”
That example reflects a broader trend. Indian equities continue to trade at substantial premiums to global peers, even in sectors where growth differentials are limited. Large Indian IT services firms, for instance, still command significant valuation premiums over global bellwethers such as Accenture, despite comparable growth prospects.
Relative to global markets, Indian equities appear expensive, regardless of the debate around whether valuations are justified on an absolute basis. The S&P 500 is expected to deliver earnings growth of about 25 per cent in CY26 and trades at roughly 22 times forward earnings. By contrast, the Nifty 500 is projected to post earnings growth of only around 8 per cent, yet trades at similar valuations.
On a trailing basis, the median P/E ratio for S&P 500 companies is 24x, with 64 per cent of firms trading below 30x earnings. For the Nifty 500, the median P/E is significantly higher at 34x, while only 40 per cent of companies trade below 30x.
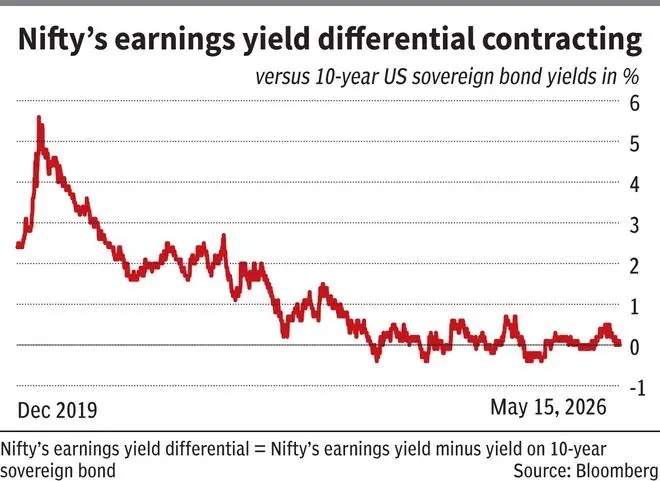
Compounding the issue is the rise in global bond yields, which has reduced the relative attractiveness of Indian equities. The earnings yield of the Nifty 50 relative to 10-year bond yields in major economies has been steadily compressing, making Indian equities less attractive compared with risk-free assets and global AI-linked investment opportunities.
There could be various factors driving the relative over valuation – Indian’s confidence in the country’s growth prospects, favourable taxation regime for equities versus debt, speculation, etc. In the process the country is not only importing gold, but also importing ownership of Indian equities from foreigners at expensive valuations.
All these factors are influencing ‘asset arbitrage’ decisions of global investors adding fuel to the fire of higher gold and crude oil imports. Factors like FII taxation may play some part, but the core issue may lie in relative over valuation of Indian equities.
Published on May 16, 2026