






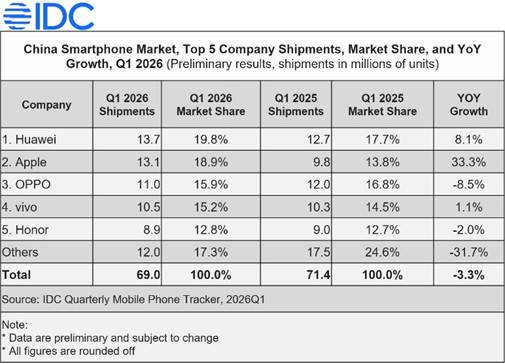
BEIJING, April 15, 2026 – China’s smartphone market declined 3.3% year over year in the first quarter of 2026, with shipments reaching approximately 69.0 million units. Despite a slight contraction, performance exceeded initial expectations due to strong demand for premium products from Huawei and Apple. Rising memory and component costs constrained supply and forced vendors to prioritize high-end models, signaling a from a volume-driven recovery to a margin-protection phase, making quality growth and operational efficiency the primary indicators for the year.
“China’s smartphone market is entering a phase where profitability matters more than shipment growth,” said Will Wong, senior research manager, Devices Research, IDC Asia/Pacific. “Vendors are making deliberate trade-offs by reducing low-end exposure and focusing on premium segments to offset rising costs and protect margins,” Wong ends.
What happened in the China smartphone market in Q1 2026?
The market declined 3.3% year over year to 69.0 million units, but outperformed expectations due to strong premium demand led by Huawei and Apple. Growth was constrained by rising component costs and supply shortages, prompting vendors to reduce low-end exposure and prioritize profitability over shipment volume.
China Smartphone Market at a Glance — Q1 2026
Why did the market change?
Premium demand remained resilient, particularly for Huawei’s Mate 80 series and foldable Pura X, as well as Apple’s iPhone 17 lineup. However, rising memory costs increased overall device production expenses, forcing vendors to reduce exposure to low-margin segments. Supply constraints further limited shipment potential, especially for Apple, where growth could have been higher without shortages.
The first quarter is expected to be the strongest period of 2026. Vendors are revising annual targets downward and maintaining tight control over low-end inventory. Market performance for the rest of the year will depend on how effectively vendors balance innovation, cost management, and supply chain resilience amid sustained pricing pressure.
Huawei maintained market leadership, supported by improved supply of its flagship and foldable devices, with the Pura X exceeding 1.5 million units in shipments. Apple recorded the fastest growth among the top five vendors, with shipments increasing 33.3% year over year, although overall volume was constrained by supply limitations.
Why did the market decline despite strong premium demand?
Rising component costs and supply constraints offset gains from premium devices. Vendors reduced low-end production to protect margins, resulting in an overall shipment decline.
Which vendors benefited the most?
Huawei and Apple led market resilience. Huawei benefited from strong flagship and foldable demand, while Apple recorded the highest growth rate among leading vendors.
What risks could impact the market in 2026?
Persistent component cost inflation, supply chain disruptions, and reduced low-end demand could limit recovery. Vendor discipline on inventory and pricing will remain critical.
IDC Tracker products provide accurate and timely market size, company share, and forecasts for hundreds of technology markets from more than 100 countries around the globe. Using proprietary tools and research processes, IDC’s Trackers are updated on a semi-annual, quarterly, and monthly basis. Tracker results are delivered to clients in user-friendly excel deliverables and on-line query tools. The IDC Tracker Charts app allows users to view data charts from the most recent IDC Tracker products on their iPhone and iPad.
International Data Corporation (IDC) is the premier global provider of market intelligence, advisory services, and events for the information technology, telecommunications, and consumer technology markets. With more than 1,300 analysts worldwide, IDC offers global, regional, and local expertise on technology and industry opportunities and trends in over 110 countries. IDC’s analysis and insight helps IT professionals, business executives, and the investment community to make fact-based technology decisions and to achieve their key business objectives. Founded in 1964, IDC is a wholly-owned subsidiary of International Data Group (IDG), the world’s leading tech media, data and marketing services company. To learn more about IDC, please visit www.idc.com/ap. Follow IDC on Twitter at @IDCAP and LinkedIn. Subscribe to the IDC Blog for industry news and insights.
Will Wong is a Senior Research Manager with IDC’s Asia/Pacific Client Devices Group. Based in Singapore, he covers the mobile phone market and is responsible for formulating valuable insights to help clients stay competitive and successful.
此内容由惯性聚合(RSS阅读器)自动聚合整理,仅供阅读参考。 原文来自 — 版权归原作者所有。