




RED ZONE: The tomato price factor in inflation watch | Photo Credit: DEEPAK KR
Financial year 2025-26 has been one of extreme volatility, caused by rather erratic policies on tariffs. This has continuously changed perceptions on economic performance, making forecasting a challenge. Does this mean we need to look at forecasts with an element of circumspection?
The accompanying table shows the forecasts for both GDP and inflation for FY26 by the RBI’s survey of professional forecasters. The movements are interesting.
The survey for the April forecasts would have been carried out a month earlier, which means it was before the tariff news from the US. The background would have been more to do with the budget’s impact on spending and tax reliefs as well as the rate cuts invoked by the Reserve Bank of India. Subsequently the GDP forecast fell to 6.3 per cent and remained virtually flat in August (before the additional tariff was imposed), then increased to 6.7 per cent (even though there was no deal in sight with the US). The forecast for December is likely to be near 7 per cent or even higher. As all these numbers are median forecasts, intuitively there are several numbers which are both higher and lower than this mark.
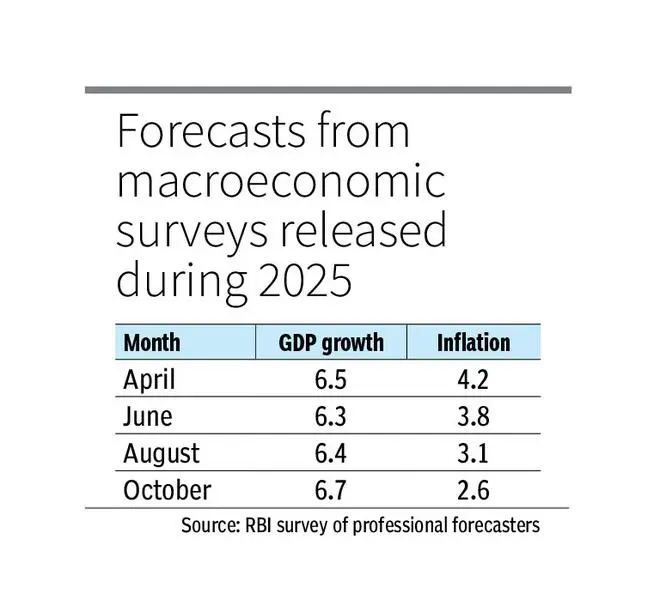
The inflation trajectory has been quite unambiguous, declining over time from 4.2 per cent to 2.6 per cent. The December number may likely be even lower, with some forecasts staying below 2 per cent.
Does this mean that forecasting is quite meaningless if there are such swings in the numbers? This is important because such forecasts form the basis of business strategy for any company. All demand forecasting is based on the GDP growth number, while pricing and cost formulation rely on the inflation forecasts. Monetary policy is discussed based on this number, which can lead to changing rationales for action. Here the RBI has been prudent by looking through the current inflation numbers and keeping an eye on future numbers, as policy needs to be forward-looking. But what if those forecasts, too, are going to change?
Why have inflation forecasts gone terribly wrong? All models would have assumed a normal monsoon for the year and a good crop. Also, forecasters are aware that the price indices in 2024 (the base) were high and would lead to low inflation in 2025. The only intervention came in the form of GST rationalisation, which would affect manufactured products more than food. Moreover, the impact would be felt from October-November. But, surprisingly, the forecasts for core inflation, which exclude food, beverages, and fuel, have been more steadfast at around 4 per cent.
The problem is that all models use past data as the foundation for assumptions on how the variable factors move. Hence the most volatile element has been food prices, where the past relationship between output and price movements has not held, leading to overestimation of inflation. The problem gets exacerbated by base effects, making some of the inflation numbers less credible. For example, tomatoes have always been a problem component with a weight of 0.57 in the CPI. In October 2023, it averaged ₹30 a kilo and went up to ₹64 in October 2024, leading to a very high inflation number. In October 2025, it was ₹38 a kilo, which is still over 20 per cent higher than in 2023. Thus, models would tend to go awry.
A similar picture emerges for the WPI components on the food side. As these indices have gravitated towards zero or turned negative, they tend to also affect GDP growth numbers. GDP components are reckoned at current prices and then deflated with inflation numbers to arrive at real GDP, which is to reflect how broadly the overall production of goods and services has grown after removing price effects. With inflation deflators being low, it is logical that the real and nominal GDP growth numbers have started moving asymptotically closer to one another. This has led to an elevation in GDP growth forecasts. Therefore, lower inflation forecasts are going hand in hand with higher real GDP growth forecasts.
As a layperson, one can ask why the forecaster could not foresee this anomaly. The answer is that it would not have been possible to estimate such low inflation figures, leading to constant changes based on adaptive expectations. The nominal-real GDP nexus has rarely been discussed as there has been a constant difference of 3-4 per cent.
This base effect syndrome would also play a dominant role in FY27, when the tables are turned. The low inflation number of, say, 0.3 per cent witnessed in October 2025 will lead to statistically a much higher number in the 3-4 per cent bracket, even if there are no food price shocks. By the same logic, the GDP growth numbers would tend to be tempered down as the wedge between nominal and real GDP numbers widens with the price deflators being more realistic. A reversal of fortunes?
(The writer is Chief Economist, Bank of Baroda. Views are personal)
Published on November 24, 2025
此内容由惯性聚合(RSS阅读器)自动聚合整理,仅供阅读参考。 原文来自 — 版权归原作者所有。