


At its April 6–8, 2026 meeting, the Reserve Bank of India’s Monetary Policy Committee kept the repo rate unchanged at 5.25 per cent and retained a neutral stance. Risks from the West Asia conflict, particularly via energy prices and supply chain disruptions, have strengthened the case for caution. While domestic fundamentals remain resilient, the Governor’s remarks indicate that the MPC will closely track incoming data before moving on rates. However, with upside risks to inflation increasing and global uncertainty remaining high, the room for rate cuts appears limited for now.
With interest rates uncertain, debt allocations for a 1–4 year horizon look sensible. Target Maturity Funds (TMFs) offer a relatively predictable way to capture prevailing yields over short to medium term. In particular, TMFs maturing within 1–4 years look appealing, as their yields have risen notably over the past six months.
TMFs are passively managed mutual funds, available as exchange traded funds (ETFs) or index funds, designed to replicate their benchmark indices by investing in underlying fixed-income securities in the same proportion. What sets them apart is greater return visibility than traditional open-ended debt funds. At the time of the New Fund Offer (NFO), asset management companies (AMCs) disclose the indicative YTM, which serves as a broad return indicator if the fund is held to maturity. Post-launch, YTMs are updated on AMC websites—daily for ETFs and periodically for index funds. This predictable return profile makes TMFs well suited for goal-based investments. YTM is the annualised yield implied by a bond or portfolio if held to maturity, assuming scheduled payments are received.
Structurally, both index fund and ETF variants are open-ended. TMF ETFs are traded on stock exchanges during market hours, while index funds can be bought or redeemed on business days at prevailing NAVs, like regular mutual funds. Index funds also offer both growth and dividend options. According to ACEMF data, there are currently 103 TMFs in the market, of which nine are ETFs and the rest index funds.
Yields across TMFs have risen over the past six months due to a mix of global and domestic factors. Elevated crude oil prices amid geopolitical tensions have raised concerns over inflation and the current account deficit, pushing bond yields higher.
At the same time, heavy bond supply, especially during the financial year-end, and increased state borrowings have added to the upward pressure on yields. Foreign portfolio investor (FPI) outflows, amid rupee weakness and relatively better yields in developed markets, have further contributed to the rise.
Interestingly, TMFs with residual maturities of 1–4 years have seen a sharper increase in YTM compared to longer-tenure segments of 7–11 years. Yields in the shorter segment rose by as much as 81 basis points, reflecting higher sensitivity to liquidity conditions, near-term rate expectations, and supply factors such as bank issuances and SDL (State development loans) supply.
As per ACEMF data as of April 11, 2026, there are 57 TMFs in the 1–4 year residual maturity segment. As of March 31, 2026, these funds offered YTMs ranging between 6 and 7.8 per cent.
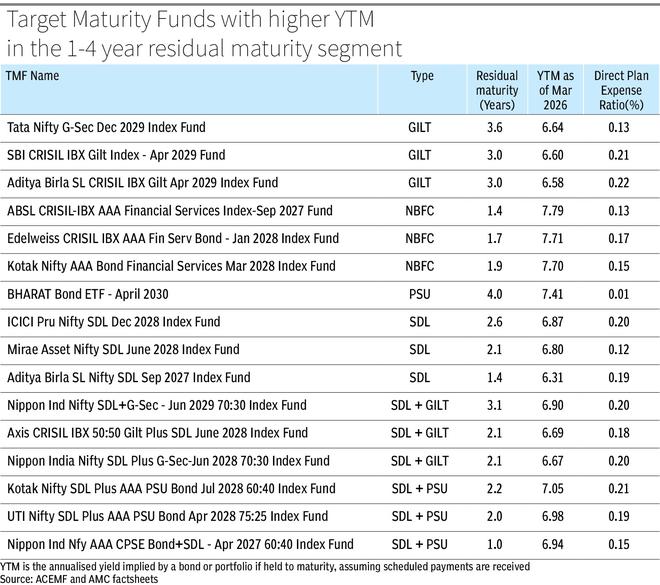
TMFs can be classified based on their underlying investments—government securities (gilt), SDLs, PSU bonds, NBFC bonds, or hybrid combinations such as gilt + SDL or PSU + SDL—each with a distinct risk-return profile.
Gilt-heavy TMFs currently offer up to 6.6 per cent in the 1–4 year segment, with minimal credit risk. Tata Nifty G-Sec Dec 2029 Index Fund offers the highest YTM of 6.64 per cent in this category.
SDL-heavy TMFs offer slightly higher yields of up to 6.9 per cent. SDLs typically deliver 30–50 basis points more than gilts. Recent trends show SDLs becoming more attractive due to higher supply and improved liquidity, with mutual funds preferring issuances from fiscally stronger states. ICICI Pru Nifty SDL Dec 2028 Index Fund offers the highest YTM of 6.9 per cent in this segment.
Among PSU bond-heavy TMFs, Bharat Bond ETF – April 2030 invests in AAA-rated public sector bonds and offers around 7.41 per cent, with a residual maturity of about four years. Compared to G-secs, it carries slightly higher credit risk, with the trade-off being a marginally higher yield along with a small increase in credit and liquidity risk.
NBFC-based TMFs invest predominantly in AAA-rated bonds issued by financial sector entities, including NBFCs and housing finance companies. Unlike PSU or gilt-heavy TMFs, these funds are more concentrated in financial sector credit.
Interestingly, such passive funds can take 100 per cent exposure to a single sector, unlike active debt funds constrained by sectoral caps. They offer higher yields due to the spread over sovereign and PSU bonds, but with moderately higher credit and liquidity risk. Aditya Birla SL CRISIL-IBX AAA Financial Services Index – Sep 2027 Fund offers the highest YTM of 7.8 per cent in this category.
Among hybrid offerings, Nippon India Nifty SDL Plus G-Sec – Jun 2029 Maturity 70:30 Index Fund offers around 6.9 per cent, while Kotak Nifty SDL Plus AAA PSU Bond Jul 2028 60:40 Index Fund offers about 7.05 per cent.
TMFs, with their predictable return profile, are well suited for goal-based investing. Investors can align these funds with specific time horizons, particularly for 1–4 year goals.
They also help reduce interest rate risk when held till maturity. For retail investors, index funds may be more convenient than ETFs due to ease of access. With a wide range of options, investors can choose based on risk appetite — gilt TMFs for safety, and financial-sector-focussed TMFs for higher yields.
When selecting funds, investors should prefer those with lower expense ratios, minimal tracking error, and a larger corpus. Under the current tax framework, gains from TMFs are taxed as per the investor’s income slab, similar to bank deposit interest. However, investors with lower taxable income, particularly those earning up to ₹12 lakh annually, including these gains, may effectively pay minimal or no tax, making TMFs a relatively more efficient option for stable income.
Published on April 11, 2026
此内容由惯性聚合(RSS阅读器)自动聚合整理,仅供阅读参考。 原文来自 — 版权归原作者所有。