


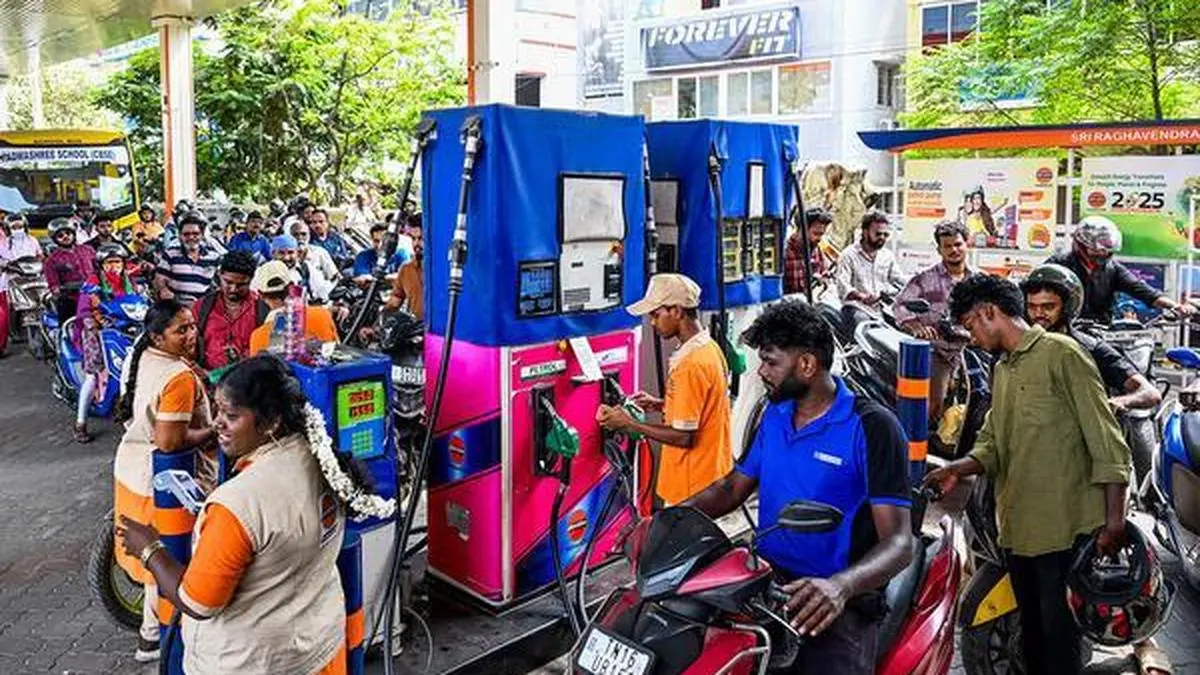
There is an urgent need to align petrol prices with market prices | Photo Credit: JOTHI RAMALINGAM B
Prime Minister Modi’s exhortation to cut back on the usage of petrol, diesel and purchase of gold should be seen as an urgent response to protect the economy from the effects of the Iran war. His focus is unmistakably, and rightly, on a widening current account deficit, at a time when capital flows have turned fickle and weakened the rupee. There can be no real case against austerity in such times. Governments the world over are doing the same in various ways. However, the more crucial question pertains to the manner in which austerity goals are met. The Centre would do well to bear in mind that prices, taxes and tariffs alone will work; moral suasion can make a marginal difference only.
The Prime Minister has focused on four broad product categories whose imports are rising sharply, and account for 38-40 per cent of total imports, at $775 billion in FY26. These are: fuel, gold, edible oils and chemical fertilizers. Petroleum imports were $173 billion in FY26, but will likely top $200 billion in FY27, given our consumption of 2 billion barrels annually at current crude oil prices. Gold imports were $72 billion in FY26, against $58 billion a year ago, rising 24 per cent. Edible oil imports were up over 12 per cent at $19.5 billion. A 61 per cent jump in fertilizer imports is a grave concern, at $16 billion in FY26 – an item whose imports could rise sharply in view of turbulence in global oil markets and our reliance on the Gulf region for supplies.
In view of this disconcerting build-up, PM Modi has urged urban residents to use public transport, work from home, avoid international travel and commute by metro or EVs. He has urged restraint in buying gold and suggested a sharp cutback in chemical fertilizer use. Meanwhile, the CAD, which had already widened to 1.3 per cent of GDP in the October-December quarter of FY26 (1.1 per cent in Q3FY25) in the wake of the tariffs impact, is under stress. The trade deficit too climbed by $25 billion in FY26, adding to the strain on the capital account.
With the elections over, the Centre must raise fuel prices to adjust demand, just as countries the world over have done. In the short run, the move will raise inflation and hurt growth, but it will bring about the desirable adjustment in demand. The status quo will widen CAD and raise inflation through the rupee depreciation route — a more destabilising prospect. Besides, the fiscal deficit will rise, hurting growth and ushering in inflation. Gold demand can be curbed by raising import duties, tweaking capital gains rules and checking loopholes in FTA deals. Edible oils use can be curbed through tariff adjustments. As for fertilizer imports, relative support prices that favour dryland, less input-using crops such as millets and pulses must be considered. Finally, the Centre must realise that for its goals to be met, it must lead by example. Checks on official travel and austerity in events can have a signalling effect in these difficult times.
Published on May 11, 2026
此内容由惯性聚合(RSS阅读器)自动聚合整理,仅供阅读参考。 原文来自 — 版权归原作者所有。