





Justin Paget/DigitalVision via Getty Images
We cover many of the common stocks within the mREIT sector. We view them as carrying relatively high risk. Therefore, risk-averse investors or those looking to buy and hold should focus on preferred shares within the sector. Preferred shares offer a way to invest in the mREIT sector without taking on as much risk. Further, one of the perks of preferred shares in this sector is that they have relatively high dividends.
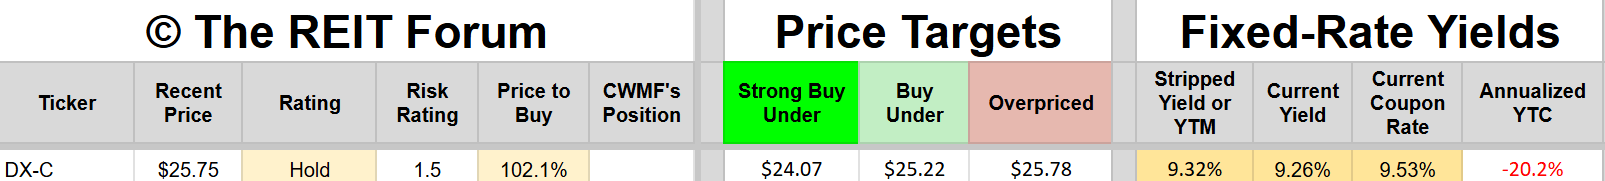
Dynex Capital has one of the lowest-risk preferred shares in the sector, coming in at 1.5. DX-C (DX.PR.C) currently has a stripped yield of 9.32%:
The REIT Forum
Investors should favor looking at the stripped yield (over current yield) because it takes dividend accrual into account. DX-C has rallied over the last month and is in our hold range. The shares have a very respectable dividend yield relative to other options. The biggest risk to these preferred shares is the worst cash-to-call:

The REIT Forum
If shares were called today with the required 30-day notice, investors in DX-C would lose roughly $0.47 per share (compared to the current market price). If an investor has already been holding these shares and collecting dividends, a call wouldn’t hurt them too badly. However, if an investor were to purchase shares today and then have DX call them, they would face a material loss.
It’s important for investors to always be looking at the call risk of preferred shares. It’s highly unlikely that the company would call the shares if they were cheap and trading under call value. The company could simply buy them at the market price. That being said, when mortgage REITs call a preferred share, it generally works against current holders. Because of that, we expect the risk of a call to put a limit on how high the share price can go. It’s fairly rare to see a preferred share trading with call risk worse than -$0.40. For that reason alone, we believe investors should be looking elsewhere to invest their capital.
On a positive note, DX preferred shares have the best coverage out of all the preferred shares we cover. The current ratio of common equity to preferred liquidation is over 15. This provides protection in a worst-case scenario where the company needs to liquidate. The chances of this happening to DX are almost nonexistent, but it helps explain why these preferred shares carry such a low risk rating.
Another added benefit is for investors with taxable accounts. We’ve said this previously and believe it’s important to state it again:
For some investors, DX-C may have a little extra appeal because it's still a REIT dividend, and that can be much more attractive than getting interest income for a taxable account. In those cases, investors may want to contemplate other shares where the call risk is not so high. However, if you're an investor using a tax-advantaged account like a 401k or an IRA, you may find a superior risk-reward option by looking at baby bonds in the sector instead.
The floating rate for DX-C carries a relatively large spread for how low the risk rating is. DX-C carries the highest floating rate of any preferred share we cover that is a risk rating of 2.0 or better. For comparable risk ratings on preferred shares, you would need to look at a company like Annaly Capital (NLY). NLY preferred shares carry a low risk rating but do not offer a stripped yield of 9% or better at current prices.
The only comparable option with the same risk rating or better is NLY preferred shares. Investors could look to the baby bonds being sold in the sector. However, there end up being two issues. First, there are some baby bonds that are comparable on risk rating, but they come in with a lower dividend yield. Second, the companies trading baby bonds with a comparable risk rating are materially riskier than Dynex Capital.
One nice thing about the baby bonds is that they have a higher place in the capital structure than the common stock or preferred shares. The baby bonds do not get the same tax advantage as a preferred share, but that can be solved (for some investors) by simply using tax-advantaged accounts.
DX-C remains one of the most attractive floating-rate preferred shares in the sector. If it weren't for the negative cash to call, I would be debating buying shares. However, at recent prices, we believe investors should sit on the sidelines or invest their capital elsewhere.
此内容由惯性聚合(RSS阅读器)自动聚合整理,仅供阅读参考。 原文来自 — 版权归原作者所有。