


By PYMNTS | April 17, 2026
Highlights
Decision-makers can often prioritize “safe,” defensible choices over potentially better but riskier innovations, mirroring the old “no one ever got fired for buying IBM” mindset.
In B2B payments, this shows up as continued reliance on outdated methods, like checks, because they offer familiarity, control and shared accountability.
Payments are becoming central to growth and customer experience and companies that modernize payment systems gain an advantage.
Few phrases in corporate history have proven as durable as “no one ever got fired for buying IBM.” It is shorthand for something deeper: when stakes are high decision-makers often choose what protects their own position over what maximizes institutional value.
That calculus has not disappeared. It has migrated. Today’s buyers may not be defaulting to a single blue-chip vendor, but they still gravitate toward incumbents, familiar workflows and systems already embedded in organizational muscle memory.
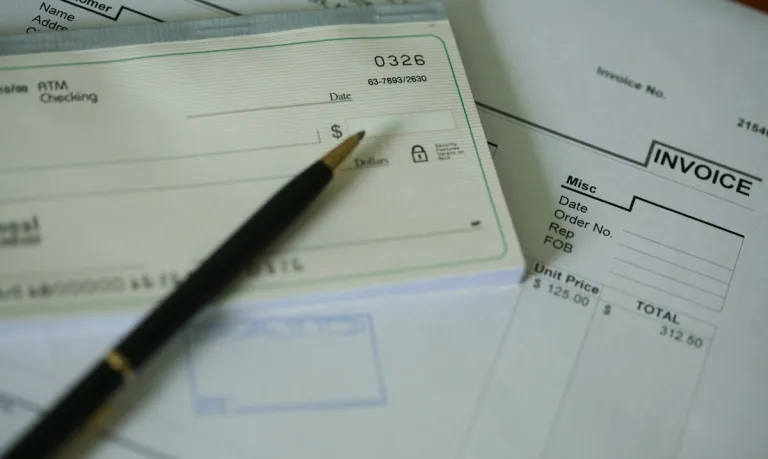
Nowhere is that instinct more visible than in B2B payments. Physical checks remain stubbornly present — and for understandable reasons. They offer visibility, control and auditability. They map to established approval hierarchies, satisfy compliance workflows and distribute accountability across accounts payable, finance and management, diffusing the risk any single decision-maker must absorb.
Digital B2B payment alternatives, by contrast, can require organizations to trust new mechanisms and, in some cases, relinquish familiar safeguards.
Change is scary. But the “safe” dynamics of traditional payment methods are increasingly being tested by a new operational reality in which financial experiences are central to growth.
As automated payments, embedded finance solutions and dynamic credit systems scale across the marketplace, the old maxim may be due for a replacement: No one ever lost business by making it easier for their customers to pay.
Advertisement: Scroll to Continue
See also: How CFOs Are Turning B2B Payments Into a Strategic Weapon
For decades, payments in B2B were treated as an operational afterthought. Invoicing, net terms and reconciliation processes were viewed as back-office concerns, largely disconnected from customer acquisition or retention.
The result was a paradox, where companies invested heavily in modernizing customer-facing experiences while maintaining antiquated payment infrastructures that introduced friction for both customers and internal teams alike.
PYMNTS Intelligence found in December, for example, that 66% of accounts payable teams saw an increase in manual workload over the prior year.
But in today’s environment, the payment layer is often the first meaningful interaction a customer has with a vendor’s system of trust. Before a product is fully adopted, before integration is complete, customers must evaluate how they will pay, when they will pay and what risks they assume in doing so. These considerations are no longer trivial, they are becoming gating functions for growth.
“The office of the CFO is broadening its mandate,” Boost Payment Solutions founder and CEO Dean M. Leavitt told PYMNTS earlier this year, adding that while decisions about how companies pay and are paid “were traditionally a secondary issue for most CFOs,” that legacy hierarchy is now changing as finance leaders come to recognize the working capital implications of strategic B2B payment design.
A company offering frictionless onboarding but rigid payment terms may struggle to convert, while a platform with superior capabilities but opaque billing structures could lose to a competitor with clearer financial workflows. Even subtle factors such as whether credit limits can scale dynamically or whether fraud controls create false positives can now determine whether a deal progresses or stalls.
Read also: CFOs Ditch AI Features to Fix Broken Payment Flows
If the old IBM adage was about avoiding blame, the emerging paradigm may be about redefining what constitutes a defensible decision. In a world where growth increasingly starts at the payment layer, clinging to outdated systems can be as risky as adopting unproven ones.
New data in the “2025–2026 Growth Corporates Working Capital Index: North America Edition,” a collaboration between PYMNTS Intelligence and Visa, reveals a widening performance gap between firms that have modernized their receivables and working capital infrastructure and those that continue to rely on manual, legacy processes.
This shift does not happen overnight. It requires a recalibration of incentives, a willingness to challenge assumptions and a commitment to continuous learning. But as the competitive landscape evolves, the cost of inaction becomes increasingly difficult to ignore.
此内容由惯性聚合(RSS阅读器)自动聚合整理,仅供阅读参考。 原文来自 — 版权归原作者所有。