











- DESCRIPTION
- TABLE OF CONTENTS
- METHODOLOGY
- DOWNLOAD PDF
Military Drones Market By Class (Small, Tactical, Strategic), Type (Combat, ISR, Delivery, Target), MTOW (Up to 150 Kg, 151-2000 Kg, >2000 Kg), Endurance, Payload Capacity, Wing Type, Autonomy, Launch Mode, Propulsion, Region - Global Forecast to 2031

USD 109.22
MARKET SIZE, 2031


MILITARY DRONES MARKET OVERVIEW
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
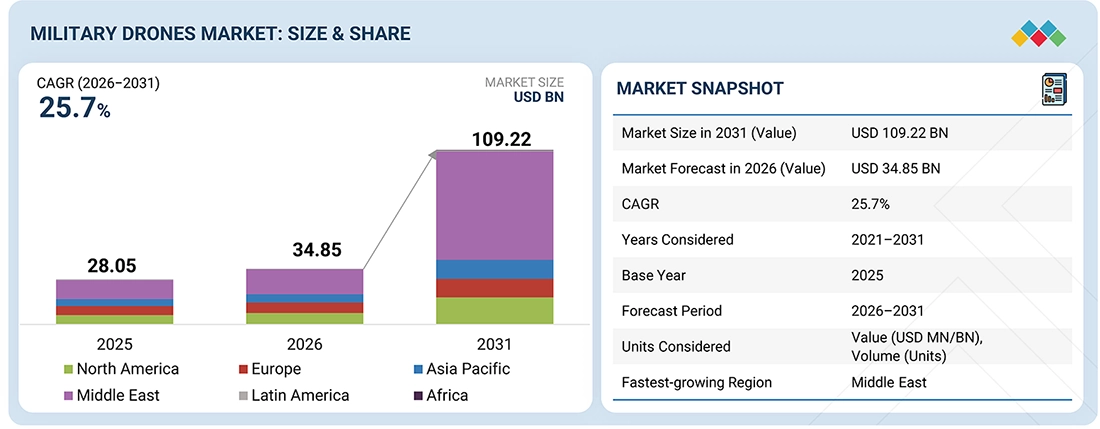
The Military Drones Market in terms of revenue is estimated to be worth USD 34.85 billion in 2026 and is poised to reach USD 109.22 billion by 2031, growing at a CAGR of 25.7%. The procurement volume of military drones is projected to grow from 16,157 units in 2026 to 26,544 units by 2031. The market is growing because of rising defense spending in major countries. Defense agencies are increasing the use of unmanned systems for surveillance missions. Combat support operations are also driving higher drone deployment in defense sectors. Border security activities are increasing the adoption of military drones. Growing investments in autonomous drone technologies are also supporting market growth.
KEY TAKEAWAYS
-
By Region
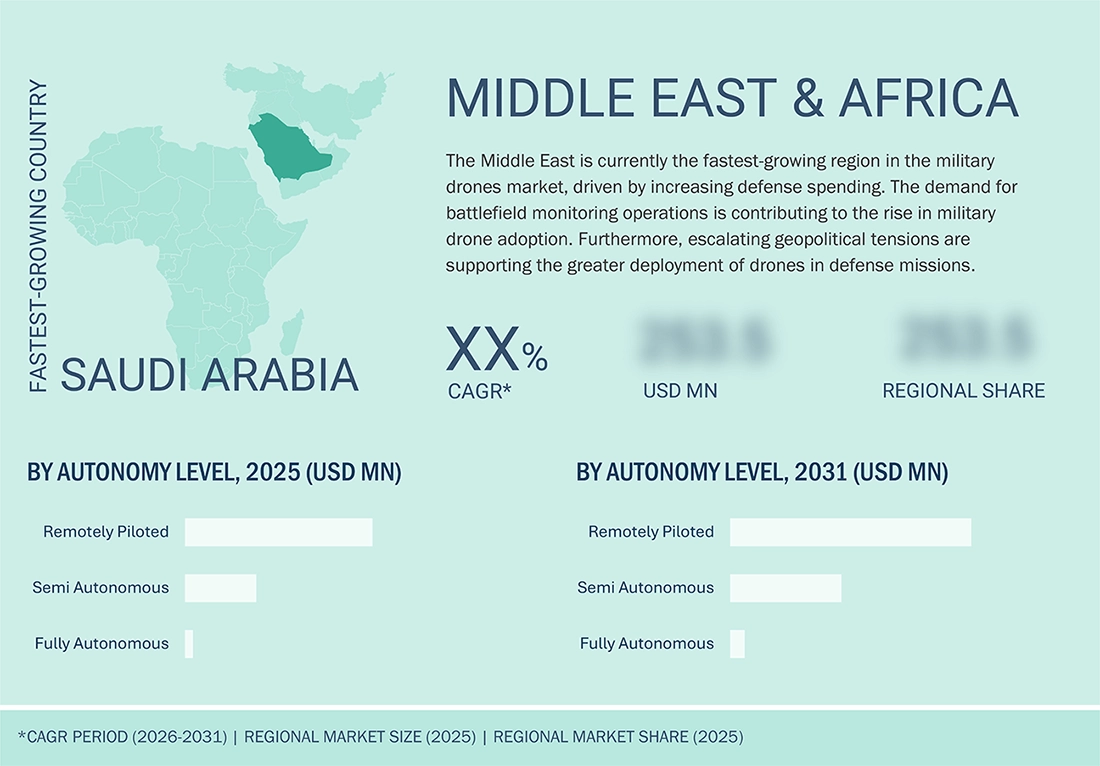
The Middle East dominated the military drones market, with a market share of 41.9% in 2025.
-
By Propulsion
By propulsion, the fuel cell-powered military drone segment is projected to grow at the highest CAGR of 32.5% from 2026 to 2031.
-
By Launch Mode
By launch mode, the catapult launched segment is projected to grow at the highest CAGR of 26.7% from 2026 to 2031.
-
Autonomy Level
By autonomy level, the fully autonomous segment is projected to grow at the fastest rate of 31.7% during the forecast period.
-
Competitive Landscape: Key Players
Northrop Grumman, RTX, General Atomics, Israel Aerospace Industries Ltd., and Teledyne FLIR LLC are recognized as key players in the military drones market. These companies hold strong positions due to their established product portfolios and wide operational presence. Consistent investment in product development supports their market standing.
-
Competitive Landscape: Startups/SMEs
ANDURIL INDUSTRIES and SHIELD AI, among others, are considered progressive companies and have distinguished themselves in the military drones market due to strong product innovation and technological advancement.
The Military Drones Industry is driven by rising defense modernization programs in major countries. Defense agencies are increasing the use of unmanned systems for surveillance missions. Combat operations are also driving higher drone deployment in defense sectors. Border security activities are increasing the adoption of military drones. Military forces are focusing on autonomous drone technologies and advanced intelligence systems for better battlefield operations. Drone manufacturers are developing longer endurance platforms carrying improved payload capabilities for different defense missions.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
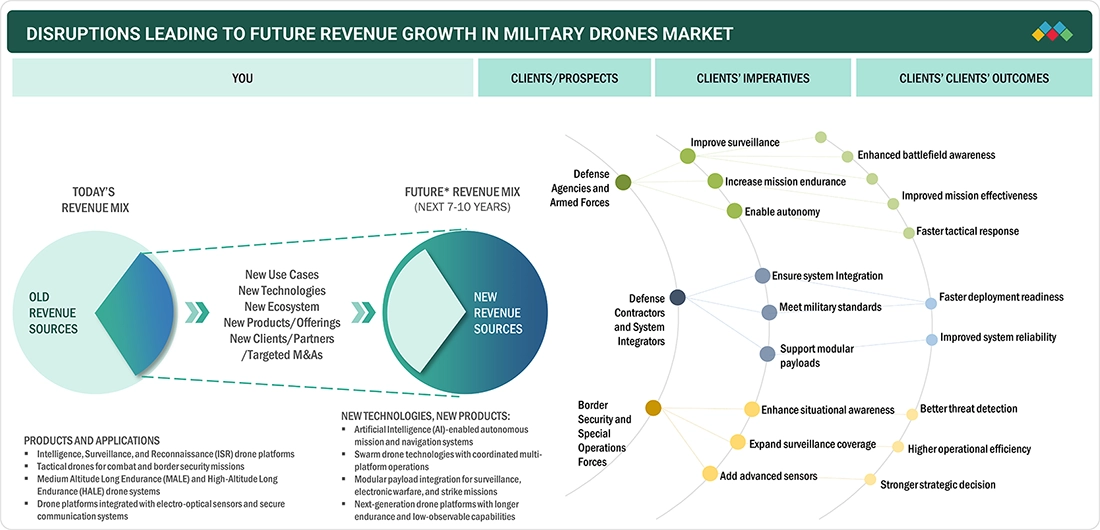
The military drones market is witnessing major technology shifts because of the rising adoption of artificial intelligence-based autonomous systems. Defense agencies are increasing investments in long-endurance drones equipped with advanced surveillance plus targeting capabilities. One major disruption in the market is the growing use of swarm drone technologies for coordinated military missions. For military missions, drone manufacturers are concentrating on modular payload systems.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MILITARY DRONES MARKET DYNAMICS

OPPORTUNITIES
Impact
Level
-
Expansion of military drone exports and international defense collaborations

-
Growing integration of military drones with manned-unmanned teaming operations

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Defense agencies are increasing investments in artificial intelligence-based drone systems for faster battlefield response. Autonomous mission execution is also increasing in military operations. Swarm drone technologies are improving surveillance coverage plus combat coordination during defense missions.
Military drones remain vulnerable to electronic warfare systems and cyberattacks during defense operations. Communication disruptions can affect drone navigation plus mission control activities. Real-time data transmission can also be impacted in combat environments.
Rising defense partnerships in different countries are creating new opportunities for military drone exports. Joint development programs are also increasing in the defense sector. Demand is rising for surveillance drones and combat unmanned systems in the global market.
Military drone production depends heavily on semiconductor components, imaging sensors, and electronic systems. Supply chain disruptions can delay drone manufacturing activities. Component shortages are also impacting defense delivery timelines.
MILITARY DRONE (UAV) MARKET SIZE, SHARE & TRENDS, 2025 TO 2031: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
|
|
Development of high altitude surveillance drones and autonomous unmanned systems for intelligence gathering and defense monitoring operations | Supports long-range surveillance missions, improves battlefield awareness, strengthens autonomous defense capabilities, and enhances real-time intelligence collection |
|
|
Supply of radar systems, targeting technologies, and counter drone solutions for military unmanned platforms | Improves threat detection capabilities, supports electronic warfare operations, enhances mission accuracy, and strengthens air defense systems |
|
|
Design and production of remotely piloted aircraft for surveillance missions and combat support operations | Supports long endurance military missions, improves intelligence gathering operations, enhances border monitoring capabilities, and reduces risks for defense personnel |
|
|
Development of tactical drones and battlefield surveillance systems for defense applications | Improves tactical surveillance operations, supports border security missions, enhances operational response capabilities, and strengthens reconnaissance activities |
|
|
Supply of imaging sensors and surveillance technologies for military drone platforms | Enhances real time monitoring capabilities, improves target identification accuracy, supports surveillance operations, and strengthens situational awareness across combat environments |


Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MILITARY DRONES MARKET ECOSYSTEM
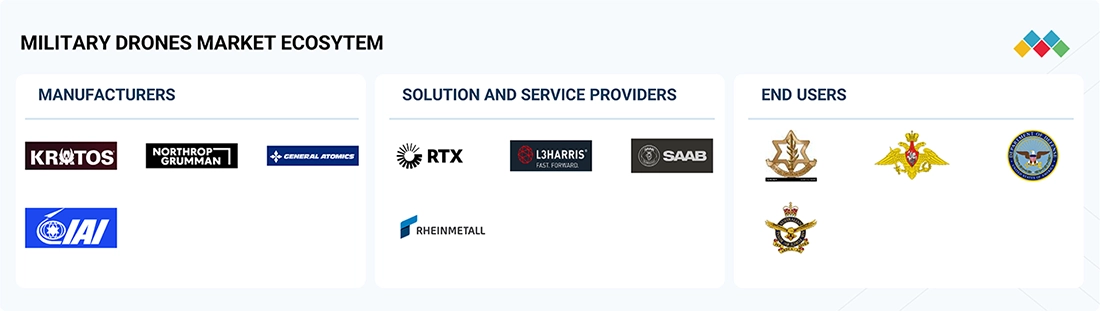
The military drones market ecosystem includes drone manufacturers, defense technology providers, system integrators, and military agencies. Companies such as Northrop Grumman, General Atomics, and Kratos develop unmanned aerial platforms for surveillance and combat missions. Solution providers including RTX, Saab, Rheinmetall, and L3Harris support the market through radar systems, communication technologies, electronic warfare solutions, and mission systems. Defense organizations such as the US Department of Defense, Israel Defense Forces, and other military agencies act as key end users driving demand for military drone technologies.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
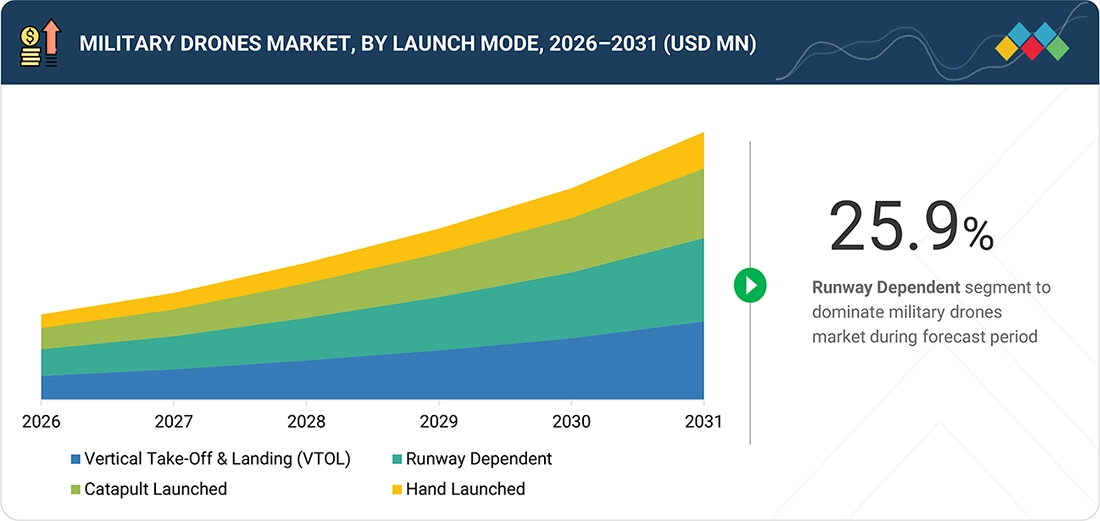
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Tactical drones dominate the military drones market as they are widely used for surveillance missions and battlefield monitoring operations. This segment is leading with the rising demand for real-time intelligence gathering across combat zones and border security activities. Defense agencies continue to expand tactical drone deployment, driving steady demand for lightweight and mission-ready unmanned systems.
ISR drones dominate the military drones market as they play a critical role in intelligence gathering and surveillance operations. This segment is leading with increasing investments in border monitoring and real-time battlefield awareness technologies. Defense forces are increasingly adopting ISR drones to improve mission planning and operational response capabilities.
The 151–1,200 kg segment dominates the military drones market as these drones support long range surveillance and combat missions. This segment is leading with the rising deployment of medium altitude unmanned systems across defense operations. Defense agencies continue to expand the use of medium weight drones, driving demand for larger payload capacity and longer endurance platforms.
The 5–50 kg payload capacity segment dominates the market as these drones support advanced surveillance systems and communication equipment for military missions. This segment is leading with the growing demand for multi-mission drone platforms across defense operations. Military agencies increasingly prefer drones with medium payload capabilities to balance operational flexibility and mission efficiency.
The 5–20 hours segment dominates the military drones market as these drones are widely used for continuous surveillance and reconnaissance missions. This segment is leading with the increasing deployment across border monitoring and combat support operations. Defense forces continue to expand the use of medium-endurance drones, driving demand for reliable long-duration unmanned platforms.
Fixed-wing drones dominate the military drones market as they are widely used for long-range intelligence and surveillance missions. This segment is leading with the rising demand for drones capable of covering large operational areas with higher flight endurance. Defense agencies continue to invest in fixed-wing platforms, driving demand for efficient battlefield monitoring systems.
Remotely piloted drones dominate the military drones market as they provide better operational control during surveillance and combat missions. This segment is leading with the increasing deployment across intelligence gathering and tactical defense operations. Military agencies continue to prefer remotely piloted systems, driving demand for secure communication and mission control technologies.
Runway-dependent drones dominate the military drones market as they support long-endurance missions and larger payload operations. This segment is leading with the growing deployment of high-performance unmanned systems across military surveillance activities. Defense agencies continue to expand runway-based drone operations, driving demand for advanced fixed-wing platforms.
Fuel-powered drones dominate the military drones market as they support longer flight duration and higher operational range for defense missions. This segment is leading with the increasing deployment in surveillance and combat support operations across large military zones. Defense forces continue to prefer fuel-powered systems, driving demand for long-endurance unmanned platforms.
MILITARY DRONES MARKET REGION
Middle East to be fastest-growing region in global aircraft seating market during forecast period
The Middle East is the fastest-growing region in the military drones market because defense spending is increasing in the region. Strong demand is rising for surveillance drones and combat unmanned systems for border security operations. Governments are investing more in autonomous defense technologies for better intelligence gathering capabilities. Battlefield monitoring operations are also increasing the adoption of military drones. Rising geopolitical tensions are further supporting higher drone deployment in defense missions. These factors are making the Middle East a major growth region for the military drones market.
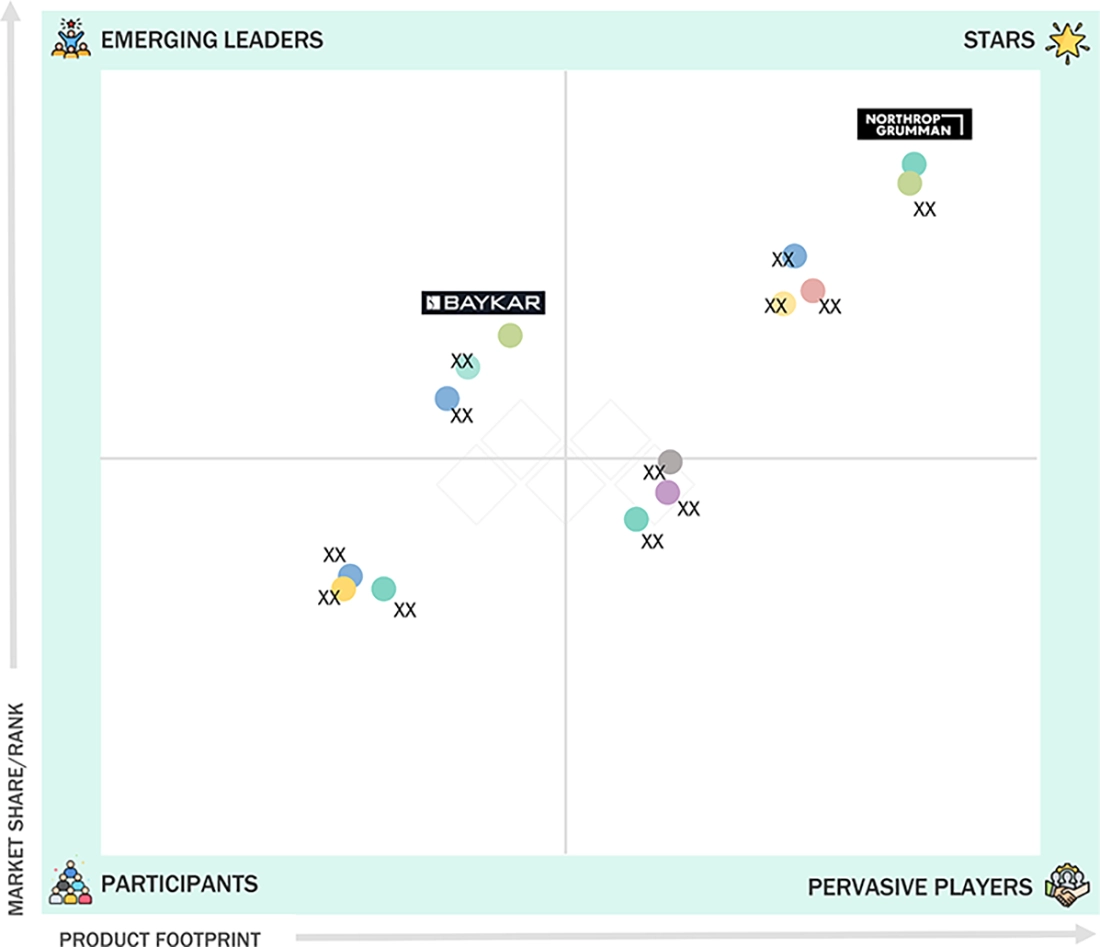
MILITARY DRONE (UAV) MARKET SIZE, SHARE & TRENDS, 2025 TO 2031: COMPANY EVALUATION MATRIX
Northrop Grumman is a leading player in the military drones market with strong capabilities in high altitude surveillance drones and autonomous defense systems used across intelligence and combat operations. The company’s presence in long-endurance unmanned platforms supports its strong market position. BAYKAR TECH is an emerging company in the military drones market with a growing portfolio of combat drones and tactical unmanned systems for defense applications.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MILITARY DRONES MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2026 (Value) | USD 34.85 Billion |
| Market Forecast in 2031 (Value) | USD 109.22 Billion |
| Growth Rate | 25.7% |
| Years Considered | 2021-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/Billion), Volume (Units) |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered |
|
| Regions Covered | North America, Europe, Asia Pacific, Middle East, Latin America, and Africa |
WHAT IS IN IT FOR YOU: MILITARY DRONE (UAV) MARKET SIZE, SHARE & TRENDS, 2025 TO 2031 REPORT CONTENT GUIDE
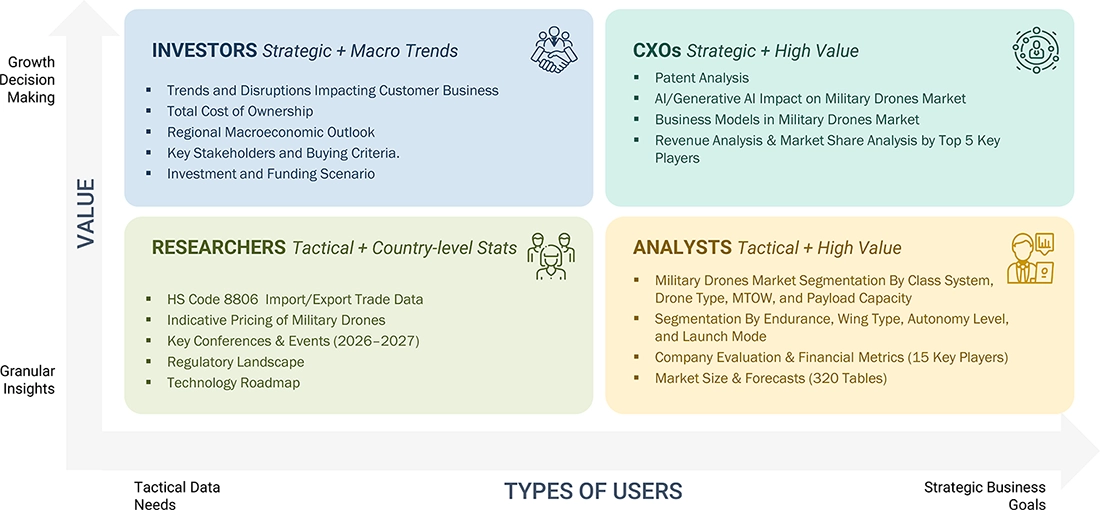
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Leading Manufacturer | Additional segment breakdown for countries | Additional country-level market sizing tables for segments/subsegments covered at the regional/global level to gain an understanding of market potential by each country |
| Emerging Leader | Additional company profiles | Competitive information on targeted players to gain granular insights into direct competition |
| Regional Market Leader | Additional country market estimates | Additional country-level deep dive for a more targeted understanding of the total addressable market |
RECENT DEVELOPMENTS
- 2/1/2026 12:00:00 AM : Northrop Grumman started flight testing activities for its Beacon autonomous drone platform to support artificial intelligence integration in future military aircraft programs. The development focuses on autonomous mission execution and battlefield decision support technologies for defense operations.
- 1/1/2026 12:00:00 AM : RTX expanded its counter-unmanned aerial system capabilities through advanced radar and electronic warfare technology integration for military drone defense applications. The development supports improved threat detection and air defense response across military operations.
- 10/1/2025 12:00:00 AM : BAYKAR TECH completed new flight demonstrations for its next-generation unmanned combat drone platform designed for surveillance and combat missions. The company focused on improving autonomous flight capabilities and operational endurance for defense applications.
- 8/1/2025 12:00:00 AM : AeroVironment, Inc. introduced an upgraded tactical drone system with enhanced surveillance payloads and secure communication technologies for military intelligence operations. The development supports improved battlefield monitoring and rapid deployment capabilities.
- 5/1/2025 12:00:00 AM : Leonardo S.p.A. expanded its unmanned aerial system portfolio through the integration of advanced sensor technologies for intelligence and reconnaissance missions. The development focused on strengthening real-time surveillance and defense monitoring operations.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
4
MARKET OVERVIEW
4.3
UNMET NEEDS AND WHITE SPACES
4.4
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
4.5
STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
5
INDUSTRY TRENDS
5.1
MACROECONOMIC OUTLOOK
5.1.2
GDP TRENDS AND FORECAST
5.1.3
TRENDS IN GLOBAL UAV (DRONES) INDUSTRY
5.1.4
TRENDS IN GLOBAL MILITARY DRONES INDUSTRY
5.4
INVESTMENTS & FUNDING SCENARIO
5.5.1
AVERAGE SELLING PRICE TREND OF KEY PLAYERS, BY TOP MODEL
5.5.2
AVERAGE SELLING PRICE TREND OF KEY PLAYERS, BY APPLICATION
5.5.3
AVERAGE SELLING PRICE TREND, BY TYPE (2025)
5.5.4
AVERAGE SELLING PRICE TREND, BY REGION (2025)
5.5.5
AVERAGE SELLING PRICE TREND, BY PLATFORM (2025)
5.7
KEY CONFERENCES AND EVENTS, 2026-2027
5.8
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
5.9
INVESTMENT AND FUNDING SCENARIO
5.11
IMPACT OF 2025 US TARIFFS ON MILITARY DRONES MARKET
5.11.3
PRICE IMPACT ANALYSIS
5.11.4
IMPACT ON COUNTRIES/REGIONS
5.11.5
IMPACT ON DIFFERENT APPLICATIONS
6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
6.1
KEY EMERGING TECHNOLOGIES
6.1.1
AI IN MILITARY DRONES
6.1.2
MID-AIR REFUELING OF DRONES
6.1.5
ANTI-UAV DEFENSE SYSTEMS
6.2
COMPLEMENTARY TECHNOLOGIES
6.2.2
AUTONOMOUS TAKE-OFF AND LANDING SYSTEMS
6.3
ADJACENT TECHNOLOGIES
6.3.2
ADDITIVE MANUFACTURING
6.4
TECHNOLOGY/PRODUCT ROADMAP
6.5.1
SYNTHETIC APERTURE RADAR
6.5.3
ELECTRONIC WARFARE USING MILITARY DRONES
6.5.4
MANNED UNMANNED TEAMING (MUM-T)
6.5.7
HYPERSONIC ARMED FORCES
6.8
IMPACT OF AI/GEN AI ON MILITARY DRONES MARKET
6.8.1
TOP USE CASES AND MARKET POTENTIAL
6.8.2
CASE STUDIES OF AI IMPLEMENTATION IN MILITARY DRONES MARKET
6.8.3
INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
6.8.4
CLIENTS’ READINESS TO ADOPT GENERATIVE AI IN MILITARY DRONES MARKET
7
SUSTAINABILITY AND REGULATORY LANDSCAPE
7.1
REGIONAL REGULATIONS AND COMPLIANCE
7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
7.2
SUSTAINABILITY INITIATIVES
7.2.1
CARBON IMPACT AND ECO-APPLICATIONS OF MILITARY DRONES
7.3
SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES
7.4
CERTIFICATIONS, LABELING, AND ECO-STANDARDS
8
CUSTOMER LANDSCAPE & BUYER BEHAVIOR
8.1
DECISION-MAKING PROCESS
8.2
BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
8.3
ADOPTION BARRIERS & INTERNAL CHALLENGES
8.4
UNMET NEEDS FROM VARIOUS END-USES
9
IMPACT OF GEOPOLITICAL CONFLICTS ON MILITARY DRONES MARKET
9.1
EVOLUTION OF MODERN WARFARE AND RISE OF DRONE-CENTRIC OPERATIONS
9.1.1
SHIFT FROM CONVENTIONAL TO ASYMMETRIC WARFARE
9.1.2
ROLE OF DRONES IN RECENT CONFLICTS (UKRAINE, MIDDLE EAST, AND OTHERS)
9.1.3
TACTICAL VS. STRATEGIC DRONE USAGE EVOLUTION
9.2
REGIONAL HOTSPOTS AND DEFENSE SPENDING REALIGNMENT
9.2.1
EUROPE (RUSSIA–UKRAINE IMPACT)
9.2.2
MIDDLE EAST (ISRAEL, IRAN DYNAMICS)
9.2.3
ASIA PACIFIC (CHINA–TAIWAN TENSIONS)
9.2.4
BUDGET SHIFTS TOWARD UAV PROCUREMENT
9.3
ACCELERATION OF PROCUREMENT, LOCALIZATION, AND SUPPLY CHAIN RECONFIGURATION
9.3.1
URGENT PROCUREMENT CYCLES
9.3.2
INDIGENOUS DRONE PROGRAMS (INDIA, TURKEY, AND OTHERS)
9.3.3
SUPPLY CHAIN DECOUPLING (CHINA VS. WEST)
9.4
EMERGENCE OF LOW-COST, HIGH-IMPACT DRONE STRATEGIES (LOITERING & SWARM SYSTEMS)
9.4.1
RISE OF LOITERING MUNITIONS
9.4.2
COST ASYMMETRY IN WARFARE
9.4.3
SWARM DRONE STRATEGIES
10
MILITARY DRONES MARKET, BY CLASS (MARKET SIZE & FORECAST TO 2031 - USD MILLION & UNITS)
10.2.1
NANO ( UP TO 250 GM)
10.2.2
MICRO (251 GM – 2 KG)
10.3.1
SHORT RANGE (UP TO 50 KM)
10.3.2
MEDIUM RANGE (51-200 KM)
10.3.3
EXTENDED RANGE (201-500 KM)
11
MILITARY DRONES MARKET, BY DRONE TYPE (MARKET SIZE & FORECAST TO 2031-USD MILLION)
11.2
COMBAT/STRIKE DRONES
11.2.2
LOITERING MUNITION
12
MILITARY DRONES MARKET, BY MTOW (MARKET SIZE & FORECAST TO 2031-USD MILLION)
13
MILITARY DRONES MARKET, BY PAYLOAD CAPACITY (MARKET SIZE & FORECAST TO 2031-USD MILLION)
14
MILITARY DRONES MARKET, BY ENDURANCE (MARKET SIZE & FORECAST TO 2031-USD MILLION)
15
MILITARY DRONES MARKET, BY WING TYPE (MARKET SIZE & FORECAST TO 2031-USD MILLION)
16
MILITARY DRONES MARKET, BY AUTONOMY LEVEL (MARKET SIZE & FORECAST TO 2031-USD MILLION)
17
MILITARY DRONES MARKET, BY LAUNCH MODE (MARKET SIZE & FORECAST TO 2031-USD MILLION)
17.2
VERTICAL TAKE-OFF & LANDING (VTOL)
18
MILITARY DRONES MARKET, BY PROPULSION (MARKET SIZE & FORECAST TO 2031-USD MILLION)
19
MILITARY DRONES MARKET, BY REGION (MARKET SIZE & FORECAST TO 2031-USD MILLION)
19.4.6
REST OF ASIA PACIFIC
19.5.4
REST OF MIDDLE EAST
20.2
KEY PLAYER COMPETITIVE STRATEGIES/RIGHT TO WIN
20.3
REVENUE ANALYSIS - TOP 5 PLAYERS
20.4
MARKET SHARE ANALYSIS OF KEY PLAYERS,
20.6
COMPANY EVALUATION MATRIX: KEY PLAYERS,
20.6.5
COMPANY FOOTPRINT, KEY PLAYERS,
20.6.5.1
COMPANY FOOTPRINT
20.6.5.2
REGION FOOTPRINT
20.6.5.3
DRONE TYPE FOOTPRINT
20.6.5.4
PAYLOAD CAPACITY FOOTPRINT
20.7
COMPANY EVALUATION MATRIX: STARTUPS/SMES,
20.7.1
PROGRESSIVE COMPANIES
20.7.2
RESPONSIVE COMPANIES
20.7.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES,
20.7.5.1
LIST OF KEY STARTUPS/SMES
20.7.5.2
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
20.8
COMPETITIVE SCENARIO
20.8.3
OTHER DEVELOPMENTS
21.1.1
NORTHROP GRUMMAN CORPORATION
21.1.3
ISRAEL AEROSPACE INDUSTRIES LTD.
21.1.4
GENERAL ATOMICS AERONAUTICAL SYSTEMS, INC.
21.1.6
AEROVIRONMENT, INC.
21.1.9
LOCKHEED MARTIN CORPORATION
21.1.10
ELBIT SYSTEMS LTD.
21.1.14
KRATOS DEFENSE & SECURITY SOLUTIONS, INC.
21.1.15
BAYKAR TECHNOLOGIES
21.2
OTHER PLAYERS (STARTUPS)
21.2.2
ANDURIL INDUSTRIES, INC.
21.2.5
GRIFFON AEROSPACE, INC.
21.2.6
XTEND DEFENSE LTD.
21.2.8
BLUEBIRD AERO SYSTEMS LTD.
21.2.10
IDEAFORGE TECHNOLOGY LIMITED
22.1.1.1
KEY DATA FROM SECONDARY SOURCES
22.1.2.1
KEY DATA FROM PRIMARY SOURCES
22.1.2.2
KEY PRIMARY PARTICIPANTS
22.1.2.3
BREAKDOWN OF PRIMARIES
22.1.2.4
KEY INDUSTRY INSIGHTS
22.2
MARKET SIZE ESTIMATION
22.2.1
BOTTOM-UP APPROACH
22.2.3
BASE NUMBER CALCULATION
22.3
MARKET FORECAST APPROACH
22.4
RESEARCH ASSUMPTIONS
22.5
RESEARCH LIMITATIONS AND RISK ASSESSMENT
23.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL
23.3
CUSTOMIZATION OPTIONS
Methodology
The study followed four main steps to estimate the size of the military drones market. Secondary research was conducted to collect data on military drone platforms, surveillance systems, combat operations, payload technologies, autonomous systems, and defense modernization programs across major countries. These findings were validated through primary interviews with defense agencies, drone manufacturers, OEMs, and industry experts. The research team analyzed defense spending trends, military procurement programs, drone deployment activities, and technology advancements to assess market demand. Market estimates were then segmented by class system, drone Type, MTOW, payload capacity, endurance, wing type, autonomy level, launch mode, and propulsion. Data triangulation was applied to validate the final figures for each segment and subsegment.
Secondary Research
Secondary research was conducted to build the foundation for this study. Data was collected from defense reports, military procurement programs, drone manufacturers, and government defense publications across major regions. Company information was reviewed through annual reports, product documents, press releases, and investor presentations of military drone manufacturers. The study also examined industry articles, white papers, and research studies related to unmanned aerial systems, autonomous technologies, payload systems, and surveillance applications. Additional insights were gathered from defense associations and industry platforms to analyze market trends, technology developments, and regional adoption patterns.
Primary Research
Primary research was conducted after key insights from secondary analysis were identified. The study team engaged with executives, engineers, cabin designers, and suppliers involved in the military drone ecosystem. Discussions included drone manufacturers, defense organization representatives, OEMs, material suppliers, and industry experts across major regions. Interviews were conducted via calls and written correspondence to validate market size estimates and customer requirements. These inputs helped refine perspectives on competition, product innovation, and deployment strategies. Feedback was also used to adjust assumptions and improve data accuracy.
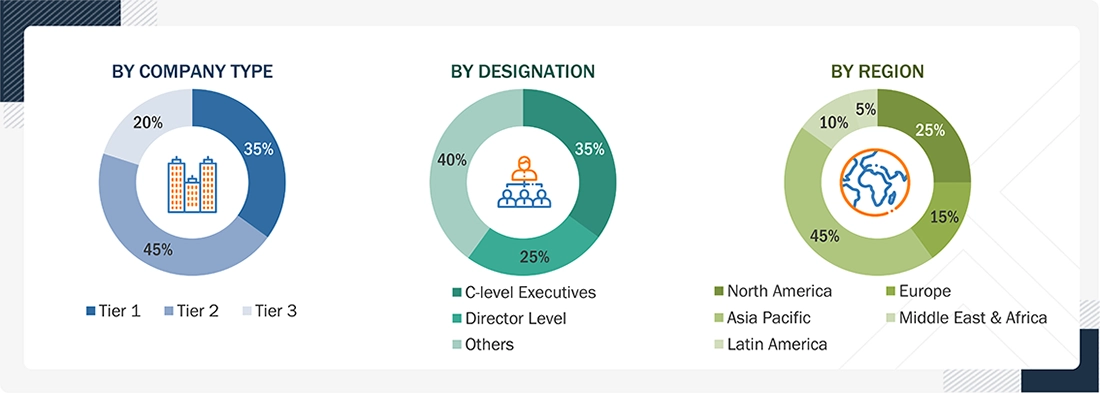
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
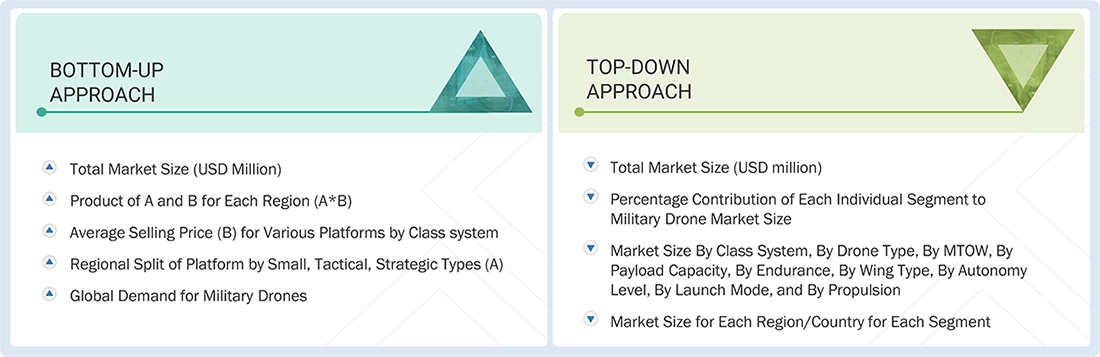
The top-down and bottom-up methods were used to estimate and validate the size of the military drones market. The research process involved several steps to ensure accuracy.
- Key companies active in the military drones market were identified through secondary research. Their market share was evaluated using a combination of primary inputs and published data. This included reviewing annual reports, financial disclosures, certification updates, and public filings from various organizations. Interviews were also conducted with industry participants such as company executives, program managers, operators, infrastructure providers, and aviation experts. These inputs were used to validate assumptions and refine market size estimates across regions.
- All percentage shares, segment splits, and market breakdowns were first developed using secondary information. These values were then verified through primary discussions with industry participants.
- The analysis evaluated key factors shaping the military drones market, including defense spending trends, military drone procurement programs, autonomous technology developments, payload integration capabilities, and surveillance requirements. Each factor was assessed through primary research and used to develop both quantitative and qualitative market estimates for this report.
Military Drones Market : Top-Down and Bottom-Up Approach
Data Triangulation
After determining the overall market size, the total market was divided into multiple segments and subsegments. The data triangulation and market breakdown procedures described below were carried out, where applicable, to complete the overall market analysis and determine the estimated market figures for the segments and subsegments. The data was triangulated by examining various factors and trends from both demand and supply sides. Additionally, the market size was validated using the top-down and bottom-up approaches.
Market Definition
The military drones market encompasses unmanned aerial systems (UAS) designed, manufactured, and deployed for defense and security operations across tactical and strategic environments. These systems operate across varying levels of autonomy, ranging from remotely piloted to fully autonomous, and are purpose-built to execute mission-critical applications, including intelligence, surveillance, and reconnaissance (ISR), precision strike operations, loitering missions, logistics, and battlefield resupply, and target simulation.
Modern military drones are highly engineered platforms integrating advanced subsystems such as electro-optical/infrared (EO/IR) sensors, radar systems, secure communication links, navigation and guidance systems, propulsion architectures, and AI-enabled autonomy software. Platform configurations vary significantly based on operational requirements, with differentiation driven by parameters such as payload capacity, endurance, range, propulsion type, launch mode, and mission profile.
As defense forces globally transition toward network-centric and unmanned warfare strategies, military drones are increasingly central to force modernization programs. These systems enable enhanced situational awareness, persistent surveillance, precision engagement capabilities, and risk reduction for personnel, while delivering cost-effective operational scalability across diverse combat and non-combat scenarios.
Key Stakeholders
- Defense agencies responsible for military drone procurement and deployment programs
- Military drone manufacturers developing surveillance drones and combat unmanned systems
- Original Equipment Manufacturers (OEMs) supplying drone platforms and mission technologies
- Payload system providers offering radar systems, imaging sensors, communication equipment, and targeting technologies
- Autonomous technology companies developing artificial intelligence-based drone systems
- Component suppliers providing propulsion systems, navigation systems, batteries, and electronic warfare equipment
- Defense technology companies supporting counter-drone systems and surveillance operations
- Maintenance, repair, and overhaul (MRO) service providers supporting drone maintenance and lifecycle management
- Government organizations responsible for defense regulations and military drone certifications
- Research institutions and defense associations supporting unmanned system innovation and technology development
Report Objectives
- To define, describe, and forecast the size of the military drones market based on class system, drone type, MTOW, payload capacity, endurance, wing type, autonomy level, launch mode, and propulsion
- To forecast the size of market segments with respect to key countries in the following regions: North America, Europe, the Asia Pacific, the Middle East, Latin America, and Africa
- To identify and analyze drivers, restraints, opportunities, and challenges influencing the growth of the market
- To identify industry trends, market trends, and technology trends currently prevailing in the market
- To provide an overview of the regulatory landscape with respect to the global military drones market regulations
- To analyze micromarkets with respect to individual growth trends, prospects, and their contribution to the overall market
- To analyze opportunities in the market for stakeholders by identifying key market trends
- To profile key market players and comprehensively analyze their market share and core competencies
- To analyze the degree of competition in the market by identifying growth strategies, such as agreements, acquisitions, partnerships, collaborations, and product launches, adopted by leading market players
- To identify detailed financial positions, key products, and unique selling points of leading market players
Available Customizations
MarketsandMarkets offers the following customizations for this market report:
- Additional country-level analysis of the military drones market
- Profiling of other market players (up to 5)
Product Analysis
- Product matrix, which provides a detailed comparison of the product portfolio of each company in the military drones market
Company Information
- Detailed analysis and profiles of additional market players (up to five)
Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Military Drones Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Leading technology innovator in Aerospace and Defense
MarketsandMarkets has been crucial to our research findings and so far, they are the best source we've been able to locate. I'm sure nobody has the predictions nailed, but they seem to know it better than most.
Previous Next
