










I first wrote about the Rule of 40 in 2015. I’d heard a late-stage investor describe it at a board meeting - growth rate plus profit should add up to at least 40% - and the simplicity stuck with me. So I blogged about it. Fred Wilson was at the same board meeting and posted his own version a few days later. Between the two posts, the Rule of 40 spread. It’s now gospel in SaaS.
I still like it. It’s a clean way to compress two things that usually fight each other - growth and profitability - into one number. Grow 40% and break even, you pass. Grow 20% with 20% margins, you pass. Grow 50% and lose 10%, you pass. Below 40%, you have work to do.
The number isn’t really the point. Rather, the market rewards growth until it doesn’t, and then it rewards profitability. I learned that the hard way in 2000. The Rule of 40 is a simple way to check that you aren’t too far out over your skis in either direction.
Others have tried to sharpen it. Bessemer proposed a Rule of X that weighs growth more heavily than profit - growth times a multiplier of two or three, plus free cash flow margin. The logic is that a point of growth compounds and drives the revenue multiple, so it’s worth more than a point of profit. I think that’s right for SaaS but it also makes my point for me. The moment you start weighting the inputs, you’re admitting the flat number was never the whole story.
While I’ve done plenty of SaaS investments, I also invest in hardware companies. Formlabs, Whoop, and Sphero today, and before that, MakerBot, Fitbit, Harmonix, and many others. I periodically get asked if the Rule of 40 means anything for a company that makes physical things.
While the answer is yes, you have to read the curve, not the snapshot.
The Rule of 40 grew up in software for a reason. SaaS has low marginal costs, high gross margins, recurring revenue, and fast iteration. A customer who signs up keeps paying. Margins show up early and hold steady. In that world, a single quarter’s snapshot tells you a lot.
Hardware breaks most of those assumptions. I’ve called it software wrapped in plastic for years. Development cycles run in years, not weeks. You spend real money up front on tooling, manufacturing, and supply chain, long before you ship a unit. Revenue often comes as one-off sales instead of a subscription, and even when recurring revenue shows up, it builds over time. Margins are real, but they tend to arrive later in a company’s life.
Point the Rule of 40 at a young hardware company and it looks broken. Growth might be strong while margins (including gross margin) are negative because the company is still building the thing. The number says “unhealthy.” The company says “on track.”
That’s the trap. A hardware company doing everything right can fail the Rule of 40 for years. If you treat the snapshot as the verdict, you push for profitability too early, you focus on the wrong things, or you cut the growth investment that makes the company worth something.
The fix isn’t to throw out the Rule of 40. It’s to stop reading it in a single time period.
For hardware, the shape of the curve matters more than any one quarter. Is the gross margin trajectory improving? Is each product generation more profitable than the last? Is the company earning the right to turn on the profit engine, or just delaying it? Those questions tell you whether a sub-40 number is a problem. In hardware, gross margin often tells the story. I’ve written before that founders and investors should go deep on it. Most don’t.
I’ve watched this play out in boardrooms for 30 years and the conversation feels different in a hardware boardroom than a SaaS one. In SaaS, growth versus profitability is a dial you can turn from one quarter to the next. In hardware, it’s a set of bets - on a product generation, a factory, a supply chain - you placed years ago and are now living with. The hardware companies that worked looked bad on the Rule of 40 early and great on it later. The ones that didn’t work looked the same all the way through. The difference was the slope.
Formlabs is a dramatic positive example. Today it’s over $250m in revenue, profitable, and depending on the quarter, hovers around or exceeds the Rule of 40. It’s the market leader in its category, with economics that look completely different from those of other 3D printing companies.
Over the years, Formlabs has repeatedly launched successful new products and entirely new product categories while simultaneously streamlining operations and improving margins. By contrast, its longest-tenured publicly traded competitor, 3D Systems, has seen revenue decline quarter after quarter for nearly five years, alongside deteriorating margins. Stratasys, which currently leads the public peer group in revenue, has fared only marginally better: revenue has also trended downward, and margin improvements have been modest. The result is two businesses that have effectively been treading water.
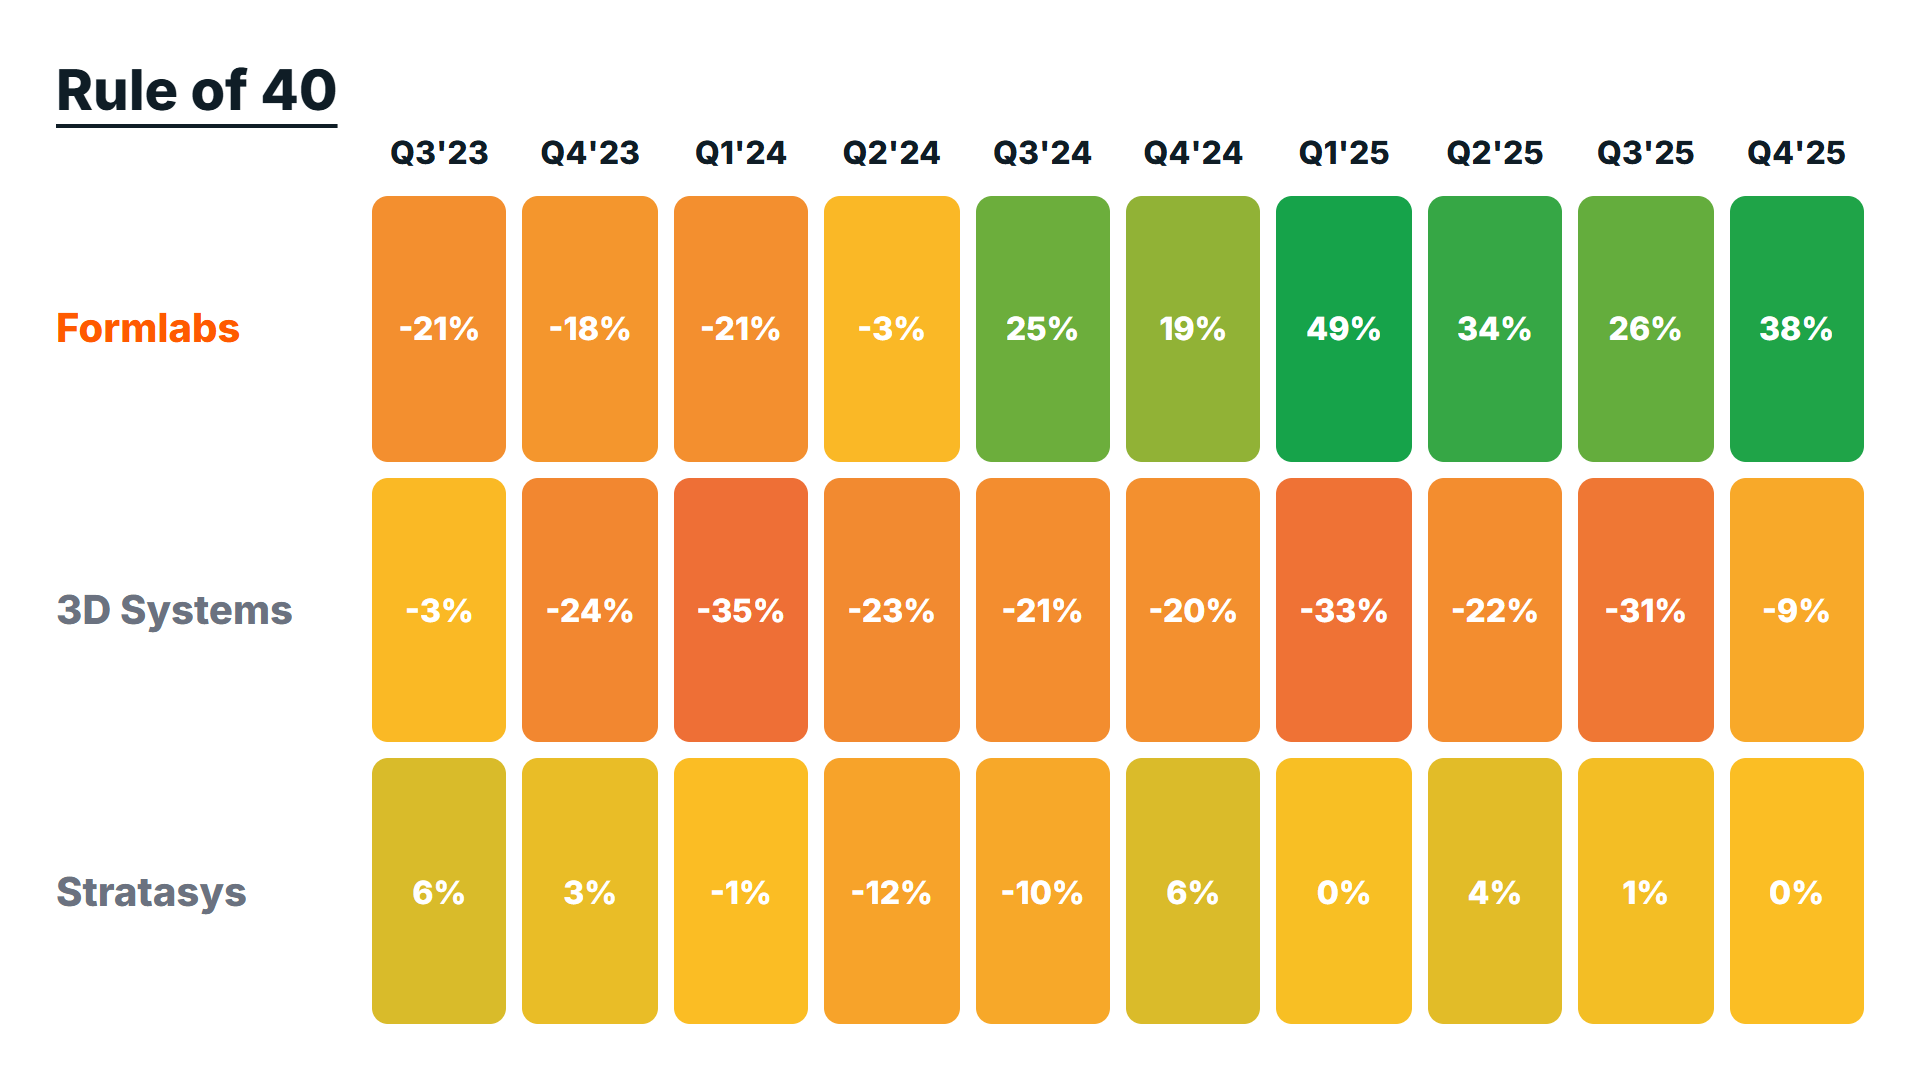
It did not look like that at the start. Getting a hardware business to the point where growth and profitability show up at the same time takes years of decisions that don’t fit on a single quarter’s scorecard. The decisions that get you there are the unglamorous kind - improving gross margin with each product generation, holding price discipline, and not turning on the profit engine until the growth engine has earned it. It also takes less capital than most people assume, which is one of the things that still surprises and delights me about well-run hardware companies.
If you had judged Formlabs based on a snapshot from its early years, you would have missed the company it eventually became.
The Rule of 40 is a good target. I’ll keep using it, in SaaS and in hardware.
Just don’t confuse the snapshot with the trajectory. Match the metric to the business model. In SaaS, you can mostly get away with the snapshot. In hardware, you can’t. Read the shape of the curve, not the single frame, and the Rule of 40 still tells you something useful.
此内容由惯性聚合(RSS阅读器)自动聚合整理,仅供阅读参考。 原文来自 — 版权归原作者所有。