



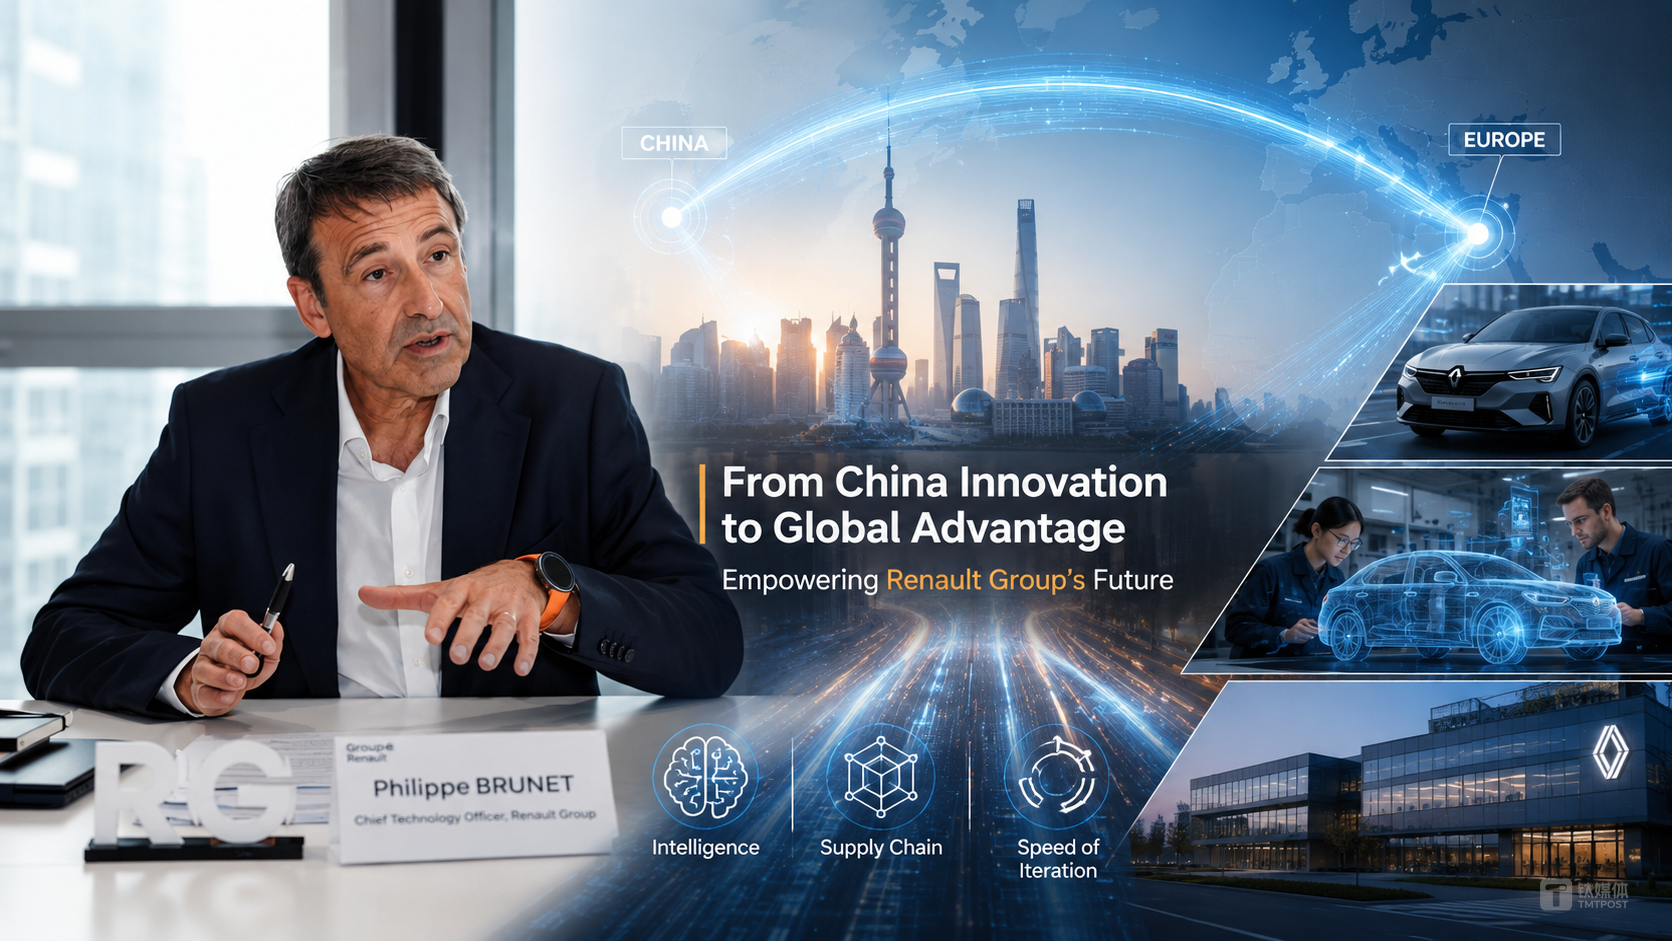
Renault Group Chief Technology Officer and ACDC General Manager Philippe Brunet
NextFin News -- Renault has been out of China’s passenger-car sales business for years, but it hasn’t truly left China’s automotive industry.
Over the past three years, Philippe Brunet—Renault Group’s Chief Technology Officer and General Manager of ACDC—has visited China 20 times. In the first half of this year alone, he has already been here three times. For a European automaker that doesn’t sell complete vehicles in China, that kind of travel cadence is uncommon. Brunet’s explanation is straightforward: if you don’t come to China, you can’t really understand where automotive technology is heading.
Behind this is a shift in how multinational automakers perceive the China market. For a long time, China primarily meant sales volume, production capacity, and a local joint-venture system. Now—at least for Renault—China’s role is pivoting in another direction: it has become more of a benchmark for R&D efficiency, supply-chain organization, and the way user needs are evolving.
Brunet describes the Chinese market as a “compass.” In his view, Chinese users’ expectations today for AI, assisted driving, and the overall EV experience may show up in the European market within the next year or two. European consumers still haven’t treated assisted driving as a decisive factor when buying a car, but as Chinese automakers enter Europe, faster software iteration, a richer set of smart features, and more price-competitive EVs will collectively reshape local users’ expectations.
For European automakers, that pressure is more complicated than simple price competition. In the past, they could rely on brand, quality systems, and accumulated global engineering expertise to define a car’s value. In the era of smart EVs, those standards are no longer stable. The product experience, cost structure, and development tempo forged through high-frequency iteration in China are, in turn, influencing the global automotive industry.
What makes Renault distinctive is that it hasn’t chosen to return to China to sell cars; instead, it has brought China into its own R&D and supply-chain system. That is more worth watching than debating whether Renault can still sell cars in China.
Building a Car in 22 Months
ACDC is Renault’s R&D center set up in Shanghai three years ago. Brunet defines its role on three levels: connecting with Chinese partners, tracking and bringing in cutting-edge technologies; building cost competitiveness by leveraging China’s supply chain; and developing full-vehicle R&D capabilities in China.
The key here isn’t any single point technology—it’s speed.
Renault’s first signature project completed in China was the all-electric version of the Twingo. The car was co-developed with input from the China team, manufactured in Europe, and sold in Europe. The development cycle was about 22 months, setting an internal record within the Renault Group. Brunet revealed that the first batch of Twingos had already begun sales and deliveries, with orders coming in at more than twice what had been expected.
In the Chinese market, developing a car in two years isn’t unusual. But for a European automaker, that timeframe reaches deep into the organization and engineering processes. Under its futuREady strategy, Renault proposed that before 2030, all models across the Group should aim to complete R&D within two years. Behind that goal is a compression of the traditional European development timeline.
When Brunet talked about the Twingo project, what was most interesting wasn’t a specific technical spec, but the difference between two ways of working. He found that in China, co-locating engineering, purchasing, suppliers, and project management to collaborate in the same place is almost the default; in Europe, teams may be spread across multiple offices, with some members not even knowing each other, relying mainly on email, meetings, and software tools to push the project forward.
The difference in pace is also obvious. Chinese projects tend to run in parallel, while European processes are more linear: one step is completed, validated, and signed off before it’s handed to the next. Chinese partners often want feedback later the same day, whereas European teams are more used to “reply by the end of the week.”
On the surface, these differences look like work habits. In reality, they point to a shift in R&D logic. In the era of internal-combustion vehicles, platforms and powertrains evolved relatively steadily, and a car could be developed, validated, and refined on a multi-year cycle. Intelligent EVs are different: E/E architectures, software features, intelligent driving solutions, and supply-chain costs are all changing rapidly. If development takes too long, a vehicle may miss the technology window by the time it launches—and miss the pricing window as well.
This is the real pressure Chinese automakers have brought to their global peers. European automakers used to explain their pace in terms of quality systems, engineering know-how, and validation cycles. Now, they still need quality—but it’s hard to keep equating “slow” with “reliable.”
Brunet didn’t dodge the question. He stressed Renault’s “zero compromise” on quality, while also noting that it had not run into quality issues when working with Chinese suppliers. The subtext is that moving fast doesn’t necessarily mean skipping validation—and that a slower European system doesn’t automatically equate to higher quality.
For Renault, the real challenge isn’t building a Twingo; it’s whether it can turn what it learns from this project into group-wide capability. Engineering, purchasing, validation, decision-making, and supplier management all need to adapt to a new pace—and that is harder than simply compressing a project timeline.
China’s Supply Chain has Become a “Shelf”
Another piece of Renault’s work in China is bringing Chinese suppliers into its global procurement system.
Brunet was careful in how he put it. He didn’t frame it as a simple “export of Chinese technology,” nor did he say Renault was going to switch its supply chain at scale. He preferred to describe it as “connecting with and learning from China’s ecosystem.” But the goal is clear: secure more competitive technical solutions at a better cost.
Renault’s approach is to bring in at least one Chinese supplier to compete in every vehicle module. Renault’s global supply chain is still dominated by European suppliers, but once Chinese suppliers enter the bidding system, it forces incumbent suppliers to improve on pricing, efficiency, and technical responsiveness. The Twingo project has already seen this kind of mix: for the electric drive system, Renault chose a Shanghai-based e-drive supplier, and glass suppliers include Fuyao.
China’s supply chain offers more than low cost. For Renault, what matters even more is mature components, fast response, and a complete ecosystem. Brunet used a vivid metaphor: China’s automotive supply chain is like a “big supermarket,” where automakers can pick proven parts right off the shelf. European automakers have long been used to redesigning large numbers of parts for every new program, but within a two-year development cycle, that “starting from scratch” model is difficult to sustain.
This also points to a more understated layer of China’s automotive spillover. In the past, discussions about Chinese automakers going global mostly focused on whether European consumers would accept their brands. Now, a deeper shift is underway: Chinese suppliers are entering the R&D processes of multinational automakers, becoming part of their global product development.
This will put pressure on Europe’s supply chain. Traditional European suppliers have historically maintained their edge through long-term partnerships, certification barriers, and local ties. Once Chinese suppliers bid for the same modules, comparisons on price, response speed, and technology maturity become far more direct. Renault doesn’t need to openly pick sides—simply having both in the room is enough to reshape the competitive dynamics.
But this path is far from easy. Brunet noted that the biggest challenge right now is building an efficient collaboration model with new suppliers and new partners. Language barriers, time zones, and geographic distance are only the surface issues; deeper down, the real gap lies in two very different operating systems: the European system prioritizes process, validation, and risk control, while the Chinese system places greater emphasis on speed, collaboration, and rapid decision-making. Combining the two could boost efficiency—or create new friction.
That’s why ACDC is not merely an engineering center. It is more like an organizational interface: translating the speed, cost advantages, and maturity of China’s supply chain into capabilities that Renault’s global system can actually use. That may be even harder than sourcing a single component.
Learning From China, Without Giving up Control
Learning China’s speed does not mean Renault is prepared to surrender technological leadership. Brunet drew a clear line on this point.
He said Europe remains Renault’s home turf, and Renault will continue to compete on the strength of its own core technologies. It will bring in Chinese suppliers and partner with Chinese companies, but the direction of key technologies and product definition will still be controlled by Renault. Outside Europe, Renault is more open in its approach—for example, partnering with Geely to expand into the South Korean and Brazilian markets.
This arrangement reflects the complicated mindset multinational automakers have when facing China’s automotive ecosystem. On the one hand, they have already acknowledged China’s advantages in electrification, intelligence, supply-chain maturity, and R&D efficiency; on the other hand, they are unwilling to hand over core capabilities entirely to external partners—especially in their home European market.
Striking that balance will only get harder. Competition brought by Chinese companies going global is not just about lower prices; it also includes faster product iteration, a more end-to-end intelligent experience, and stronger supply-chain coordination. Once European consumers get used to these experiences, legacy automakers will no longer be able to justify premium pricing with brand heritage and engineering tradition alone.
Brunet’s view on the electrification trend was also fairly clear. He believed that, outside the United States, electrification continued to advance in most markets, and emissions regulations would keep squeezing the room available for internal-combustion vehicles. In Renault’s European sales, the share of EVs had already risen from under 20% a year earlier to 50%. That said, Renault did not choose to bet solely on battery EVs; instead, it pursued two tracks in parallel—battery EVs and HEVs—without emphasizing PHEVs.
This also ties to Renault’s mass-market brand positioning. Brunet stressed that Renault does not pursue technology for technology’s sake, nor is it a luxury brand built around showy performance. What it needs to solve is how to bring technology that customers truly want—and can afford—to the mainstream market.
This is exactly where the significance of the Twingo lies. It isn’t a product meant to showcase technological prowess; it’s a small EV used to test whether Renault can use “China methods” to reshape Europe’s mainstream vehicle development model. Under Renault’s plan, the development cycle for subsequent models in the same family is set to be shortened further to 16 to 18 months. Brunet said that when Renault set the 22-month target, Chinese suppliers were very confident; when the timeline was squeezed to 16 months, they started to feel the pressure too.
This suggests that the race for speed has boundaries. Compressing the schedule too aggressively could introduce new risks in quality, coordination, and organizational execution. For Renault, “China methods” aren’t an answer that can be copied verbatim, but a toolkit that has to be digested, filtered, and reorganized.
For now, Renault’s China experiment still can’t be written up as a success story. What it has shown is that European automakers can learn in China—speed, cost discipline, and ecosystem collaboration. At the same time, it raises a thornier question: now that China has become one of the sources of methodology for the intelligent EV industry, how can multinationals preserve their own judgment while learning?
Renault doesn’t sell cars in China, yet it has woven China into its R&D system. This may be a more realistic stance for multinationals when facing China’s auto industry. What Renault still needs to prove next is whether this approach can push through the inertia of Europe’s organizations, supply chains, and brand systems—and ultimately become Renault’s own capability. (Author | Li Yupeng, Editor | Yang Lin)