





Then, after the close on Tuesday, Micron Technology dropped its earnings report—and the theater filled back up.
Revenue of $41.5 billion. Gross margins of 84.9%. EPS of $25.11. Every figure landed well above what Wall Street had expected, blowing past a Street consensus of $35.9 billion in revenue and $20.86 in earnings per share. More startling than the numbers themselves was the guidance: Micron told investors to expect $50 billion in revenue next quarter — roughly $6.5 billion more than analysts had penciled in, at a consensus of $43.6 billion. Its stock, which closed Tuesday at $1,048.51, jumped sharply in after-hours trading, pulling up NVIDIA, AMD, and the broader semiconductor complex with it.
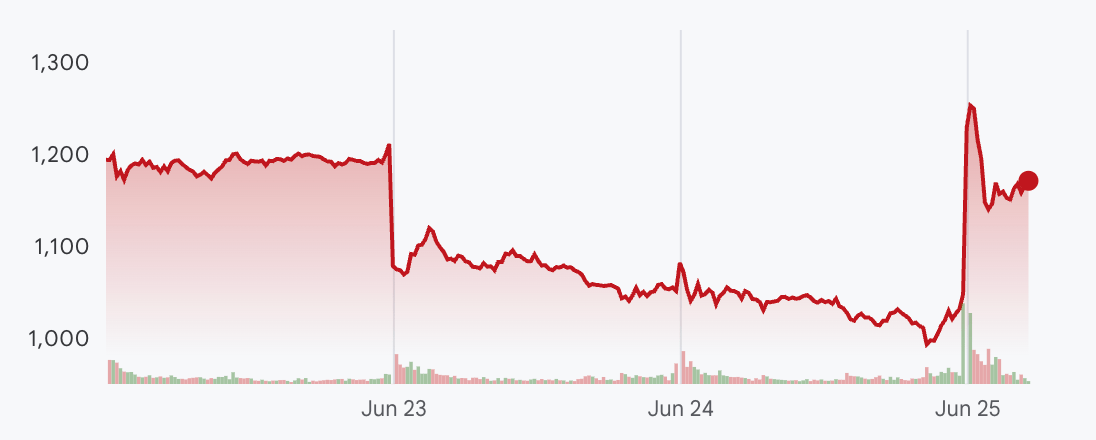
“Tech investors will be in a very positive mood and breathe a sigh of relief,” Wedbush Securities’ Dan Ives wrote in a note to clients, with the typically bullish analyst reaching for the kind of hyperbole that sounds extreme until you check the tape. He called it a “drop the mic quarter.”
Other analysts argued that this might be quite a bit more than that. Buried inside the earnings call and the cascade of analyst notes that followed was something that could reshape how investors think about memory chips—and possibly the entire AI infrastructure trade—for a generation.
To understand what Micron reported Tuesday night, you first have to understand what has happened to memory over the past two years.
Memory chips—the DRAM and NAND that store and move data inside computers and servers—have historically been the most brutally cyclical corner of the semiconductor industry. Prices spike, manufacturers overinvest, supply floods the market, prices crater, manufacturers pull back, and the whole thing starts again. For decades, buying a memory stock felt less like investing in a technology company and more like betting on the weather.
AI may not have broken that cycle, but it bent severely.
The explosion of large language models and AI inference infrastructure has created a class of memory demand that is qualitatively different from anything that came before it. High-Bandwidth Memory — the stacked, specialized DRAM that sits directly atop AI accelerators like NVIDIA’s Blackwell chips — cannot simply be manufactured faster by throwing more money at the problem. Building the cleanrooms takes years, the process nodes are among the most complex in semiconductor manufacturing and labor is constrained.
The result: memory demand is, right now, running significantly ahead of supply—and Micron says it expects that gap to persist beyond 2027. On Tuesday night, the company extended that forecast, telling investors there is no clear line of sight to when supply will catch up.
“The company states that, as the AI market expands, memory intensity will increase and memory will become a strategic device, and that this shift is still in its early stages,” Jefferies’ Tokyo-based analyst Masahiro Nakanomyo wrote in a note to institutional clients.
The data bore that out. DRAM revenue of $31.3 billion was up 67% quarter-over-quarter, representing 76% of total company sales. Average selling prices for DRAM rose approximately 60% in the quarter and core data center revenue—the segment most directly tied to AI infrastructure — more than doubled sequentially, reaching $11.5 billion, up 653% year-over-year.
“We are seeing no cracks in AI demand on the chips, hardware, or software front,” Ives wrote, “which gives us a bright green light to own the core tech winners into year-end.” In other words: what AI bubble?
But the numbers, extraordinary as they were, were almost secondary to the structural announcement buried deeper in the call.
Micron disclosed that it has now signed 16 Strategic Customer Agreements — SCAs — with customers ranging from four large hyperscalers to medium-sized technology companies to nine smaller automotive suppliers. These are not soft letters of intent. They are five-year, take-or-pay contracts, running from 2026 through 2030, with binding volume commitments and rigid pricing terms. Customers who walk away from them do not get their money back: Micron has collected $18 billion in cash deposits and $4 billion in letters of credit—$22 billion in total financial commitments—as guarantees.
Each contract contains a ceiling and a floor. The ceiling is pegged to current market prices—roughly where DRAM was trading in the second calendar quarter of 2026. The floor is set at levels that, according to Micron’s management, would generate gross margins above the company’s best-ever quarterly performance in any prior industry cycle—a historical peak in the low-60% range. So the worst-case pricing scenario in these contracts is better than the best Micron has ever done in a downturn.
“The historical ceiling,” noted Stifel analyst Brian Chin, “is now a floor”.
For Wall Street, this represented something close to a paradigm shift. Memory companies have historically traded at depressed multiples precisely because their earnings are wildly unpredictable. The SCAs introduce, for the first time at scale, contractual earnings floors across a multi-year horizon. The boom-bust model that defined memory investing for 40 years may not be dead, but it has been materially altered.
Stifel’s Chin called it “concrete evidence of a paradigm shift” that “could temper the downside swings that characterized past cycles.”
Not everyone in the analyst community was unambiguously cheering.
Vivek Arya, BofA’s lead semiconductor analyst and one of the sharpest voices on the street, reaffirmed his Buy rating and raised his price target to $1,550 — the highest target among major banks — up from $1,500 previously. But he introduced a concept that other analysts danced around without naming: the memory tax.
Memory, Arya noted, now accounts for roughly 35% of AI infrastructure capital expenditure. As prices have soared, Micron and its peers have effectively become a toll booth on the AI highway — collecting an ever-larger share of every dollar that hyperscalers like Microsoft, Google, Amazon, and Meta spend building out their data centers.
That dynamic has a natural limit. Push the toll too high and the drivers start looking for alternate routes—or slow down. In price-sensitive markets like mobile phones and automobiles, already operating on thin margins, memory price spikes can tip purchasing decisions, crimp demand, and eventually feed back into oversupply.
“Elevated memory pricing could act as a ‘tax’ on data center customer capex growth,” Arya wrote, “while also leading to potential demand destruction in price-sensitive end markets like mobile and auto.”
The SCA pricing caps—which moderate Micron’s near-term upside—exist partly because Micron’s biggest customers pushed back. Locking in supply at current prices, for five years, with a ceiling on further increases, is a rational move for a hyperscaler facing its own cost pressures. Morgan Stanley’s Joseph Moore noted the dynamic candidly, writing that some Micron disclosures “have led to some sentiment that the company is capping prices.”
Of course, the bulls note, gross margins heading toward 90% and a structural floor well above prior cyclical peaks make the “capped” scenario extraordinarily profitable by any historical standard. BofA noted that gross margins are expected to peak in the high-80% range over the next few quarters before some normalization sets in, as rising bit costs from new capacity and technology transitions weigh on the other side. “While bears may focus on pricing moderation,” Arya wrote, “we see continued evidence supporting a structural rerating.”
That word—rerating—is not one that Wall Street uses lightly.
For years, memory stocks have traded at single-digit earnings multiples during their best years, because investors assumed the good times wouldn’t last. The memory cycle was treated like a commodity: buy low, sell when the upcycle peaks, exit before the inventory pile-up arrives.
BofA argued explicitly that Micron should structurally rerate to 12x–15x P/E, versus a historical range of 8x–10x — a re-rating of 50% or more on the valuation baseline — driven by the SCA structure, the AI demand durability, and the FCF profile now taking shape. At current prices, Micron trades at roughly a 10% free cash flow yield, according to BofA’s model. BofA projects TTM free cash flow exceeding $100 billion within the next 12 months, with margins expanding.
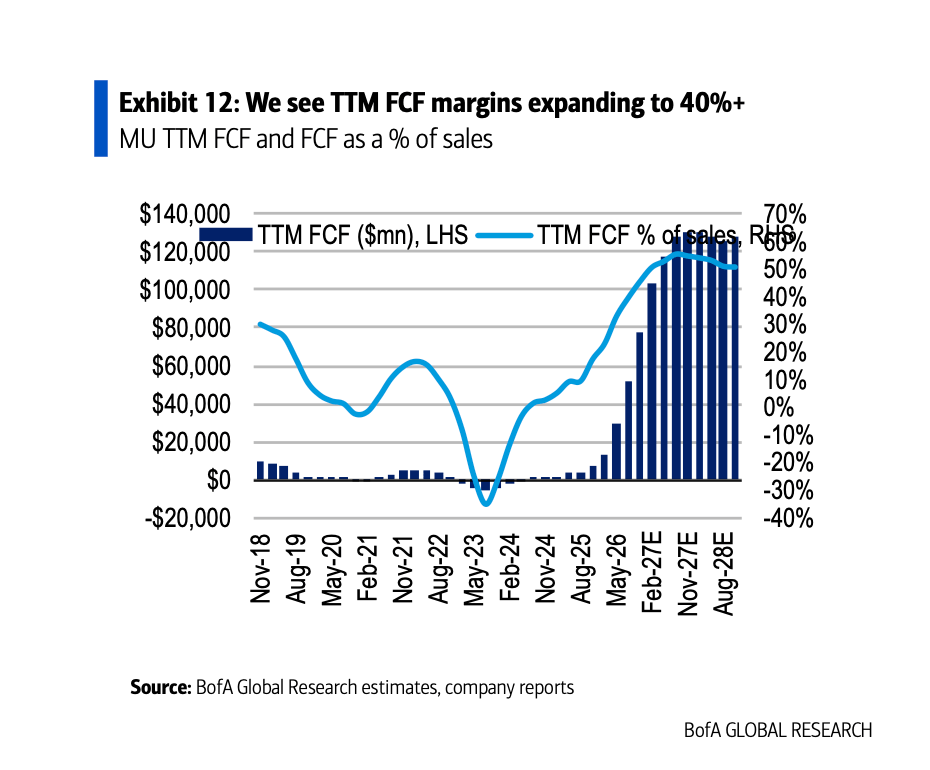
Morgan Stanley’s Moore bumped his price target to $1,200 from $1,050, and kept his Overweight rating. He lifted his FY27 EPS estimate by 40% to $168 per share and his FY27 FCF estimate from $104 billion to $140 billion. “DRAM fundamentals are in uncharted territory, and should continue to improve as datacenter/AI markets continue their upward trajectory,” he wrote.
Micron’s 20-year, $200 billion U.S. investment plan, backed with support from the Trump administration’s CHIPS program, is already underway: Idaho Fab 1 is on track for its first wafer output in mid-2027, and construction on Fab 2 has accelerated with operations targeted for late 2028; the New York fab broke ground in January 2026.
The catalyst hiding inside all of this is the CHIPS Act clock. On December 9, 2026, two years after Micron signed its definitive CHIPS Act agreements, restrictions on certain uses of the company’s cash expire. Management has committed to returning 100% of excess free cash flow to shareholders thereafter. BofA models $31.7 billion in buybacks for fiscal year 2027 alone — and notes, pointedly, that this represents only approximately 25% of the free cash flow Micron is likely to generate that year. Net cash on the balance sheet is projected to reach $140 billion by the end of fiscal 2027.
For context on the scale of that number: Micron’s net cash was negative as recently as late 2025.
Micron’s results do not exist in isolation. They are, in effect, a real-time audit of the AI infrastructure buildout—conducted by the company supplying one of its most critical and constrained inputs.
When Micron says memory demand will exceed supply beyond 2027, that is also a statement about NVIDIA’s order book, about Microsoft’s Azure expansion, about Meta’s data center ambitions, about the capex plans of every hyperscaler that has bet its next decade on AI. When it says it is accelerating construction of new fabs in Idaho, New York, Taiwan, and Singapore—with FY26 capex now guided to $27 billion, up from a prior guide of $25 billion, and FY27 capex projected at $45 billion—that is a statement about the earnings outlook for Applied Materials, Lam Research, KLA, ASML, Advantest, and the entire semiconductor equipment supply chain.
Beyond data centers, Micron flagged an emerging demand driver that most AI coverage has yet to seriously price in. The penetration of Level 2 Advanced Driver Assistance Systems (ADAS) and above systems is expected to more than double to over 20% of new vehicles in 2026 and reach 40% by 2030. Level 2+ vehicles carry over five times the memory content of an average car. More striking still: humanoid robots carry 10 times the memory content of a Level 2 vehicle, and Micron described a “multi-decade memory demand cycle” in robotics expected to begin in the latter part of this decade.
There are risks, of course. A recession that slows enterprise IT spending. A faster-than-expected ramp of Chinese memory competitors. A sudden softening of AI model training demand if frontier labs hit architectural walls. A geopolitical flare-up disrupting the Taiwan supply chain. Stifel’s Chin enumerated the bear case in his own note: economic recession, over-expansion of supply, AI datacenter projections proving too aggressive, irrational pricing from new entrants, or delays on technology roadmaps, including HBM4 and next-generation NAND. Memory has surprised to the downside before, suddenly and violently, and the very complacency that comes with long-term contracts can mask the inventory buildup arriving at the margin.
But Tuesday night’s results made the bear case considerably harder to argue.
For now, the sell-off is over. The memory tax is real. And the valuation regime may be changing faster than anyone expected.
For this story, Fortune journalists used generative AI as a research tool. An editor verified the accuracy of the information before publishing.
此内容由惯性聚合(RSS阅读器)自动聚合整理,仅供阅读参考。 原文来自 — 版权归原作者所有。