






The numbers are hard to ignore. The top 10 companies in the S&P 500 now account for 34% of all index profits—a share that’s doubled since 1996—and 41% of its market cap. AI companies represent nearly 87% of all venture capital funding and roughly half of all investment-grade bond issuance.
By almost any measure, artificial intelligence isn’t just influencing markets. It is the market. And that has Wall Street doing something it can’t quite help: reaching for history.
Every major strategist covering equities is running the same mental comparison — lining up today’s AI boom against the late 1990s internet buildout and asking where we are in the cycle. Evercore ISI’s Julian Emanuel says the post-March 2026 rally “feels like 1999 … relatives, friends, doctors, Uber drivers are all talking about AI/Tech stocks.” On the other side, veteran chip analyst-turned-fund manager Dan Niles argues the closer parallel is 1997 — years three and four of an infrastructure buildout with real runway remaining. Both men are staring at the same market and seeing different years.
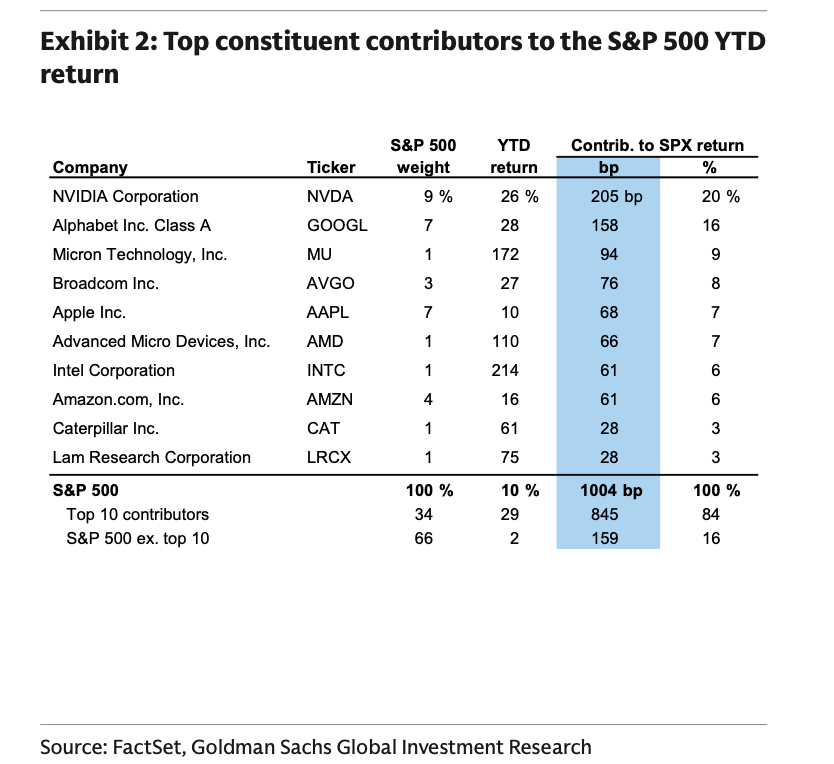
The Goldman Sachs equity strategy team led by Ben Snider put a fine point on the structural problem this week. In their Weekly Kickstart, they describe the S&P 500 as “one big trade”: technology accounts for 85% of the index’s 10% year-to-date return, and Nvidia alone — at 9% of S&P market cap — has contributed 20% of the aggregate YTD return.
The Goldman Momentum factor, which now moves in near-lockstep with AI stocks, has surged 25% in three months, one of its sharpest rallies on record. Goldman notes that in past episodes of comparably sharp momentum rallies with the market near a high — including mid-1998, late 1999, and late 2021 — subsequent S&P returns were soft. The market breadth signal is flashing a similar warning: the median S&P 500 stock sits 13% below its 52-week high even as the index registers new records.
Apollo’s Torsten Slok has been sounding the concentration alarm with data that is hard to dismiss. The S&P is no longer a diversified index, he argues on his Daily Spark blog — it’s a vehicle dominated by a small number of extraordinarily profitable tech companies, and capital is piling in across every asset class.
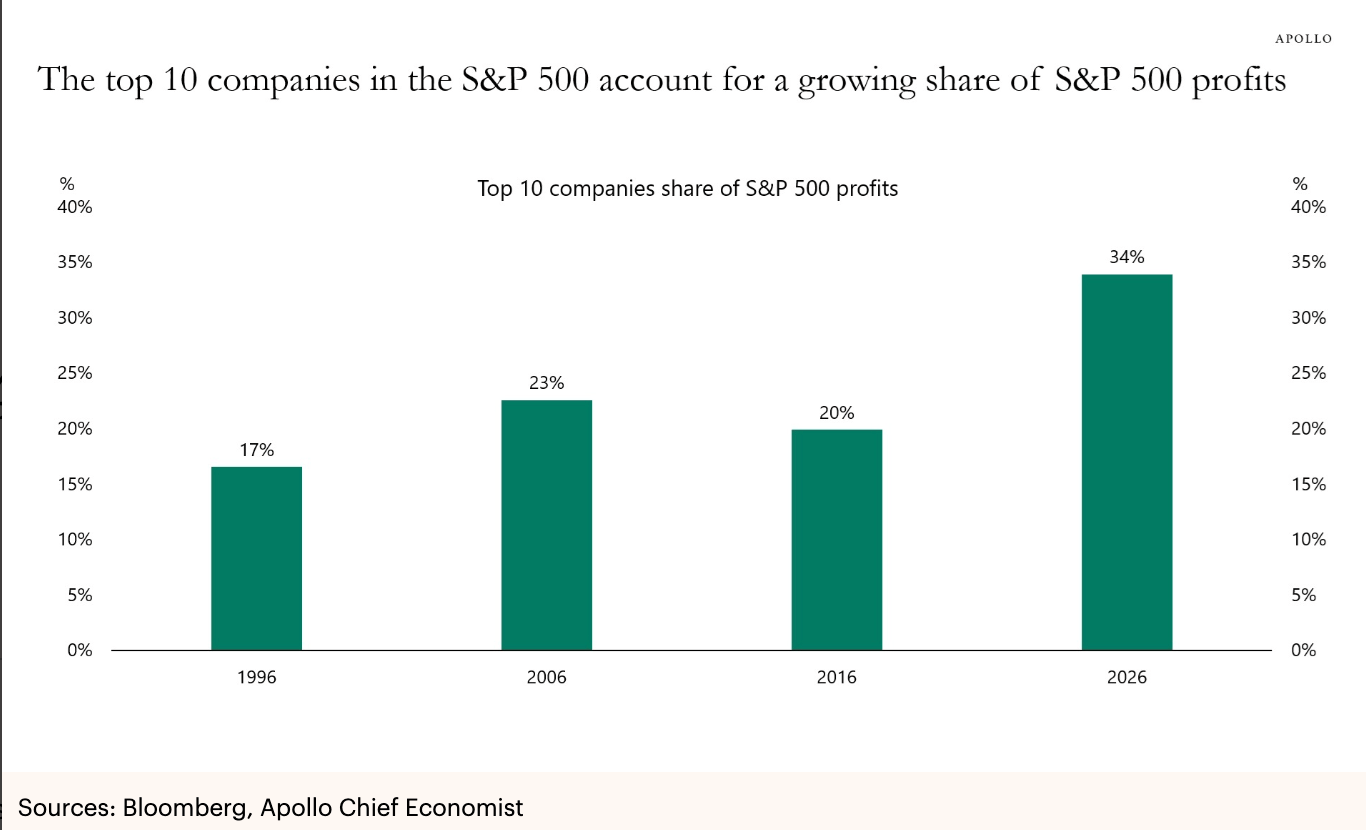
Goldman’s economics team, in a separate note by Pierfrancesco Mei published Saturday, deepened the structural case: rising concentration has accounted for roughly one-third of the increase in U.S. corporate profit margins since 2000, and the industries most exposed to AI — information, finance, professional services — are already the most concentrated and highest-margin sectors in the economy. When AI accounts for nearly all VC funding and half of IG bond issuance, that’s not diversification of the AI thesis. It’s doubling down on it across the entire capital markets stack.
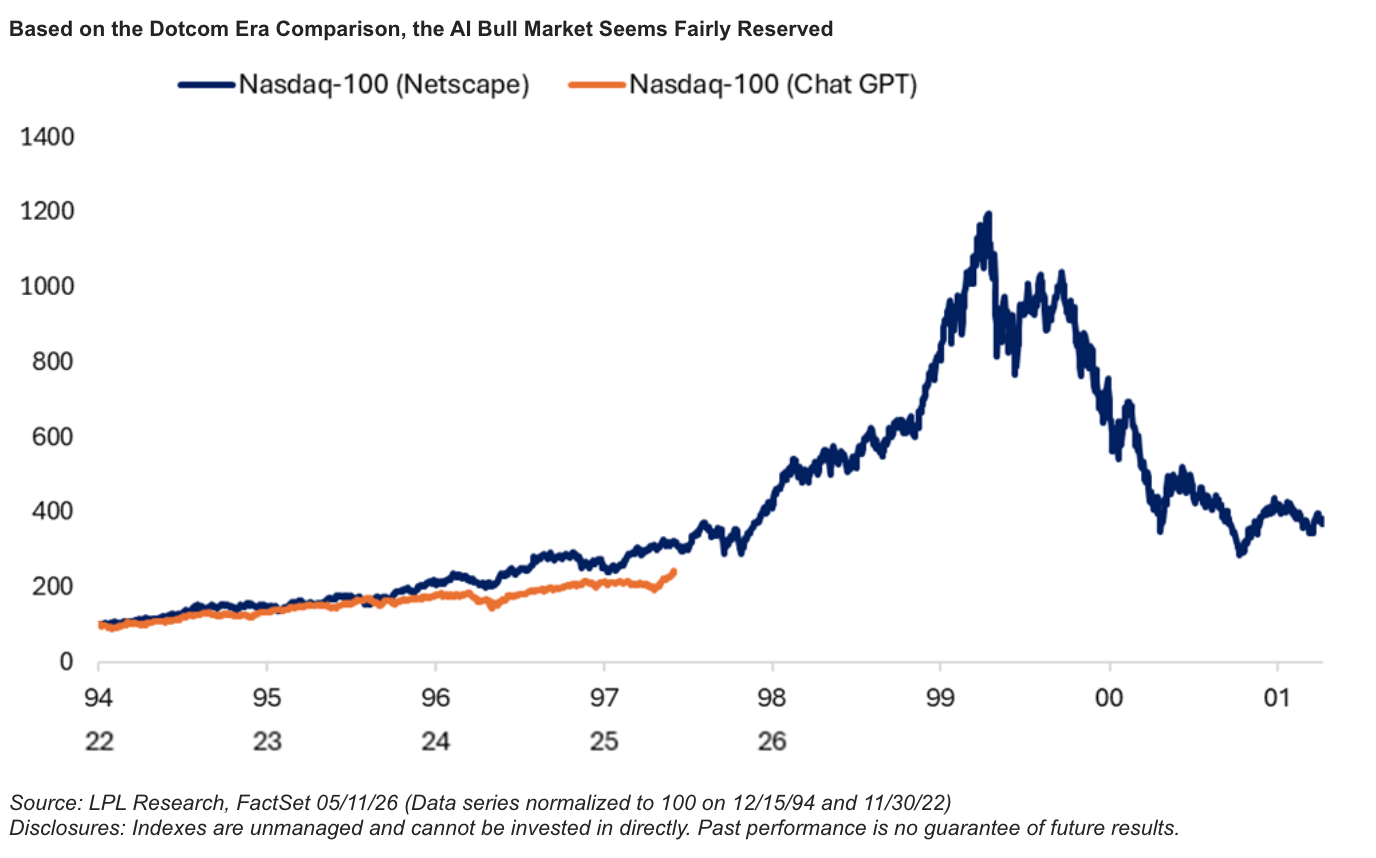
LPL Financial’s Jeff Buchbinder offers the counter. The Nasdaq-100 is up roughly 140% since ChatGPT launched — impressive, but nowhere near the 1,090% gain the index posted between Netscape’s debut and the dotcom peak in March 2000. Tech valuations sit around 25x forward earnings today; at the 2000 peak they were 58x.
Goldman’s Mei agreed that the valuation picture looks different from the dotcom era: breadth today is “far less narrow than the market in 1999-2000,” and current market concentration — while extreme — has not reached dotcom-era levels. Critically, the AI adoption phase has barely begun; the current buildout is still centered on infrastructure.
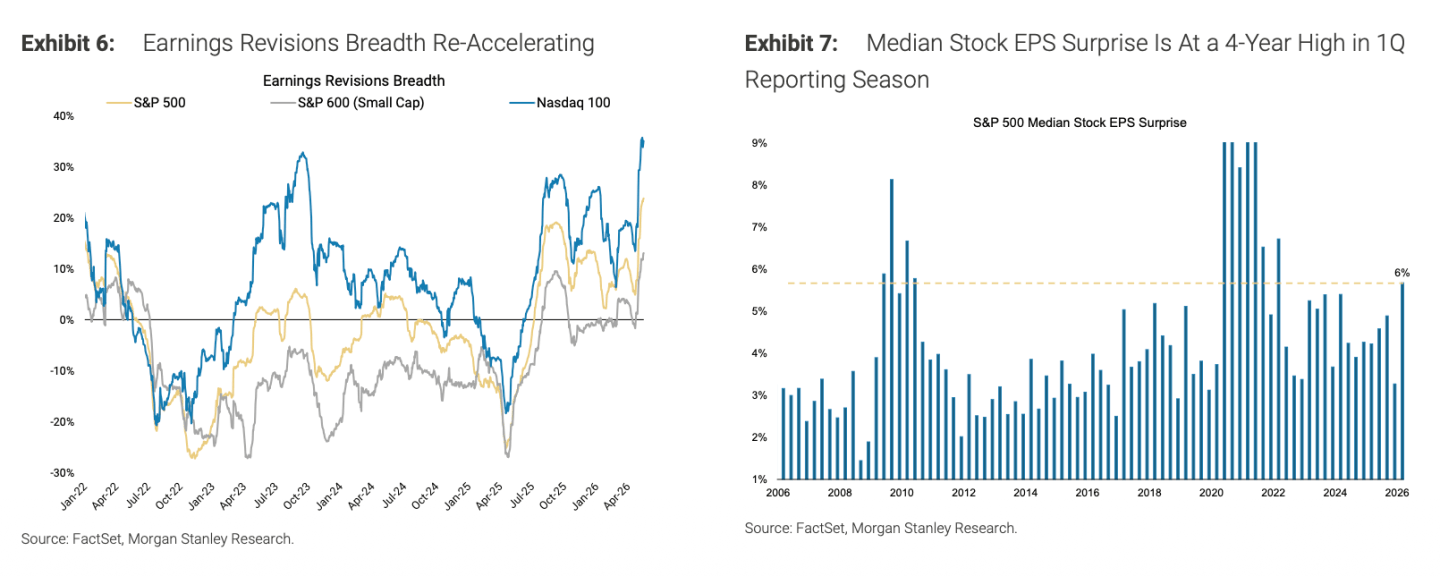
Morgan Stanley’s Michael Wilson offered a different frame entirely that complicates the 1997/1999 binary. In his mid-year outlook, published this month, the bank’s chief U.S. equity strategist raised his S&P 500 year-end 2026 target to 8,000 and his 12-month target to 8,300, insisting “this is an earnings story, not a multiple expansion one.” His core argument: the AI rally is masking a genuine broadening of earnings growth beneath the surface. S&P 500 EPS revision breadth just hit a four-year high at 24%, median stock earnings growth is running at 16% — double the trailing four-quarter average — and small-cap forward earnings growth is approaching 20%.
Gad Levanon, chief economist of the Burning Glass Institute, similarly waved aside the bubble talk in a recent conversation with Fortune.
“Anytime there’s a huge increase in stock prices for a long time, people will think that there is a bubble,” he said. “But at the same time, we also have a huge increase in the earnings of those companies, so it’s not based on nothing.”
Maybe there is some overvaluation and you can never rule out bubbles in markets, Levanon allowed, but if you look at the revenue growth of the Magnificent Seven, “certainly a lot is happening.” He said it’s hard to use some new tools coming online, Claude Code from Anthropic in particular, “and not think that it’s transformative.” Levanon said it’s obvious to him that there will be “huge usage” of these tools in many professions.
Goldman’s read of the data supports these arguments in part: EPS revisions have been positive in every S&P sector over the past month, and consensus 2026 and 2027 EPS estimates have each risen 8% YTD — driven primarily by AI infrastructure and energy capex. Yet when you strip out AI infrastructure and energy companies, 2027 EPS estimates are essentially flat YTD. The broadening, in other words, is real but fragile — and it lives almost entirely inside the AI story.
Goldman economist Mei’s work on concentration and margins provides the deepest structural context of any of these notes. The core finding: new technologies have historically raised concentration rather than democratized it, because scale advantages accrue to the firms with the capital and organizational capacity to deploy technology first.
The sales share of the top 1% of U.S. firms rose from roughly 60% in the 1960s and ’70s to around 80% in recent years — and concentration has risen fastest during periods of rapid technological change. The implication for AI is explicitly two-sided: AI could plausibly foster greater competition in some high-margin, high-concentration sectors; but history suggests the more likely outcome is that the most successful AI adopters pull further ahead, intensifying concentration and sustaining elevated margins for the leaders.
That dynamic is already visible. Morgan Stanley’s data show that excluding semis, hardware, and power stocks, long/short hedge fund exposure is at a 10-year low — meaning most of the market is being left behind as a narrow group captures the AI gains.
The 1997-or-1999 question isn’t academic. If Buchbinder and Wilson are right, investors rotating out of AI-adjacent tech now are leaving the best part of the cycle’s returns on the table. If Slok’s concentration data — and Goldman’s momentum analysis — are the more telling signal, the market’s apparent health is a top-10-company illusion.
The honest answer may be that the 1997/1999 framing is itself a symptom of bubble brain — the irresistible human urge to map the present onto the past. This time is different in ways that matter (earnings-backed, cash-flow-funded, infrastructure-phase growth rather than adoption-phase growth) and similar in ways that should make investors nervous (record concentration, record momentum, and a market that is, as Goldman puts it, “one big trade”). The question is whether “different enough” is a sufficient margin of safety.
For this story, Fortune journalists used generative AI as a research tool. An editor verified the accuracy of the information before publishing.
此内容由惯性聚合(RSS阅读器)自动聚合整理,仅供阅读参考。 原文来自 — 版权归原作者所有。