





That hard-to-get reservation at the just-opened restaurant? It might run through a booking platform owned by your credit card company. The court-side tickets and the post-game meet-and-greet? Same. The hotel you’re about to book, the car ride to the restaurant, the points that post when the check arrives—increasingly, all of it lives inside infrastructure controlled by a single card issuer.
When American Express acquired the restaurant reservation platform Resy in 2019 and integrated it into its mobile app as a benefit for rewards cardholders, it was the first of its kind in an increasingly perk-heavy ecosystem that has come to encompass the credit card industry. Five years later, Amex paid $400 million for Tock, the reservation and table management service, expanding its foothold in a dining category that accounted for $100 billion in spending on Amex cards in 2024 alone. In 2021, Chase acquired The Infatuation, a restaurant discovery platform, and has since built exclusive dining promotions, food festivals, and content access into its Sapphire card lineup.
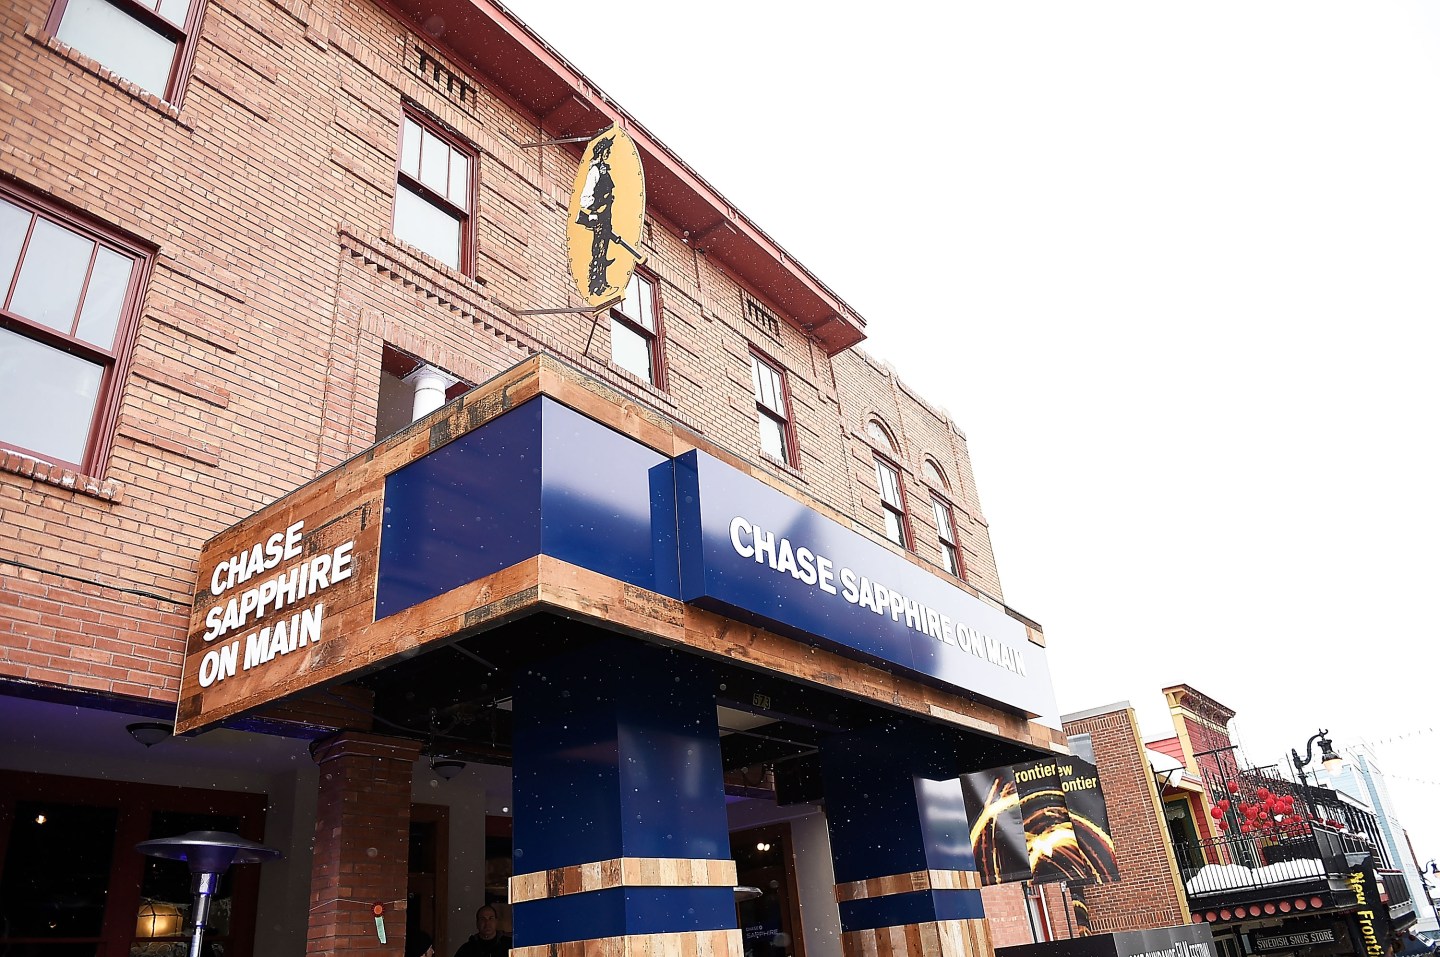
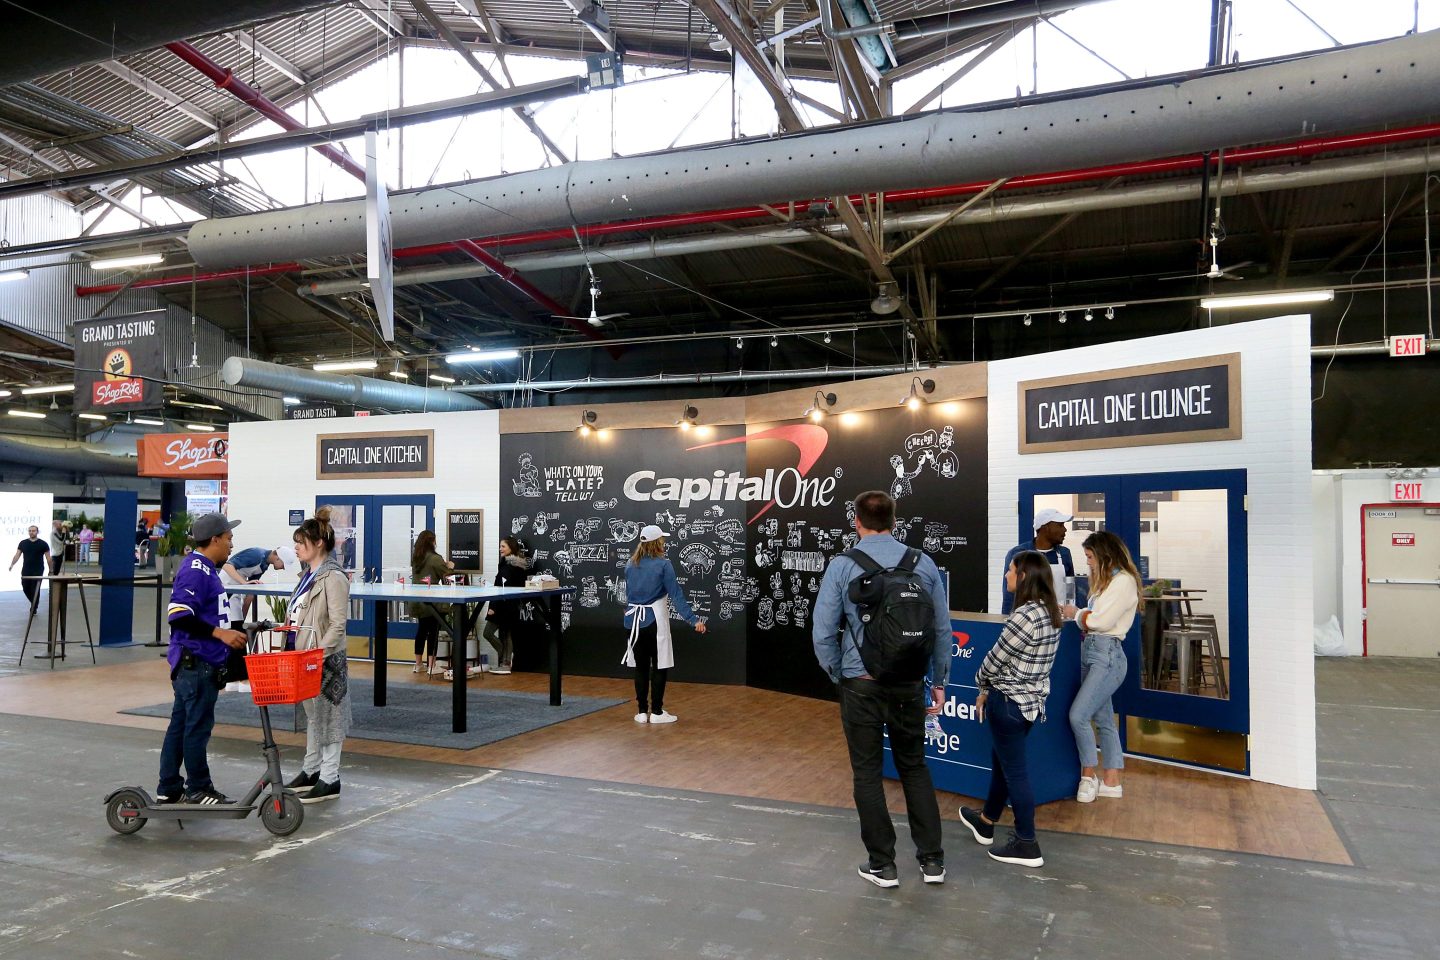
The acquisitions are only part of the strategy. Amex Platinum and Centurion cardmembers get access to “By Invitation Only” events, Platinum House pop-ups, and Global Dining Collection experiences with top chefs, none of which are open to the public. Amex cardmembers get special ticket access and presales across sports, theater, dining, and live music, and Amex hosts its own member experiences at Austin City Limits. Chase Sapphire Reserve cardmembers get exclusive lounges, film panels, and dining events at the Sundance Film Festival, just as it opened branded Sapphire Lounges at JFK, LaGuardia, Las Vegas, Phoenix, San Diego, and Philadelphia, each featuring curated food from restaurant groups like Momofuku. Like Amex, Sapphire Reserve cardmembers now get exclusive restaurant reservations through Sapphire Reserve Exclusive Tables on OpenTable, with the list curated by The Infatuation. And Capital One gives cardholders early access to events it sponsors, such as the New York City Wine & Food Festival and the South Beach Wine & Food Festival.
Sure, all of this may look like credit card perks to market to cardholders, but they’re largely acquisitions that signal a fundamental shift in what credit card companies are building. These aren’t perks bolted onto a credit card. They’re the credit card.
Matt Winkelmeyer/Getty Images
“Amex owns Resy, Chase owns The Infatuation,” said Nick Ewen, editor-in-chief of The Points Guy. “They are investing heavily in creating these ecosystems that live within their card programs.” The traditional model—swipe, earn points, redeem them somewhere else—is giving way to something more vertically integrated.
Chase’s travel portal illustrates the playbook. Sapphire Reserve cardholders earn 10 points per dollar when they book through Chase. Book the same hotel directly, and they earn 4. “They’re incentivizing you to stay in their ecosystem,” Ewen said. “If you’re someone who values points, that’s a significant difference.”
Every stage of the transaction—discovery, reservation, payment, rewards—now sits inside the issuer’s infrastructure. Chase processes the payment, owns the content platform that recommends where to eat, controls the booking engine that reserves the hotel, and runs the rewards program that makes it all feel like a deal.
Richard Kerr, VP of Travel at Bilt Rewards and a former Points Guy writer, said other issuers are moving in the same direction. Bilt began as a card that let renters earn points on rent, a category no one else had figured out how to monetize. It has since become something closer to a neighborhood operating system.
“We are way past the point of, oh, it’s a credit card company. Less than 10% of our members even have the Bilt card,” Kerr said. He described the company as building an “identity layer” that ties a member’s housing, dining, and travel preferences into a single profile that follows them across services.
The neighborhood layer matters. A restaurant used to drop flyers in apartment buildings advertising specials and proximity. In Bilt’s model, Kerr said, a member books through Resy or OpenTable, the system automatically arranges a Lyft to the restaurant, payment processes through Toast at the table, and the loyalty points post — without anyone coordinating the chain.
“No one’s calling anyone,” Kerr said. “No one’s texting anyone. It’s fully automated. The member just shows up.”
Hospitality was the harder sell. Luxury hotel owners had long viewed points programs as downmarket—cheap currency, cheap customers. Bilt’s answer, Kerr said, was an AI concierge. A first-time guest at a five-star hotel typically generates 90 minutes of pre-arrival coordination—who they are, what they like, which room they belong in. The concierge handles that matchmaking from the member’s profile, pairing travelers to properties based on preferences rather than price.
“We can make a first-time guest feel like a tenth-time guest,” Kerr said.
For suite-level bookings, Bilt has automated BLADE helicopter transfers and car service through a partnership with the company, layering more of the trip into the same ecosystem—one that now reaches more than 5.5 million U.S. households. Bilt partnered with Forbes Travel in February 2026 and, a month later, acquired Sion, a commission management platform that processes $7 billion in travel-booking revenue.
Rob Kim/Getty Images for NYCWFF
Matt Schulz, chief consumer finance analyst at LendingTree, said the math supports the expansion. Banks make so much on interchange fees and annual fees that even a cardholder who never carries a balance is profitable. Once that customer is inside the ecosystem, the issuer can keep selling—premium banking, wealth management, travel.
“They know that Chase can upsell you and make you a private client if you have x amount of money in your checking account,” Schulz said. “It’s the same thing as the front of the checkout counter at Old Navy. They’ve got socks and belts. They’re just trying to upsell you.”
The difference, Ewen said, is the surface area. The upsell is no longer a co-branded store card. It’s the entire surrounding ecosystem—restaurant reservations, hotel bookings, travel portals, fitness memberships, event access. A Platinum cardholder books dinner through Resy, gets an exclusive reservation, earns Membership Rewards on the meal, and books the hotel through Amex’s Fine Hotels & Resorts program—never leaving Amex.
“Every touchpoint is theirs,” Ewen said.
The trade-off is price transparency. The platforms are designed to steer cardholders toward hotels and restaurants that earn more points, and away from alternatives. The fewer options a member sees, the more their spending is shaped by the platform’s design rather than their own preferences. A travel portal might offer a hotel at 10x points, even though a direct booking at 4x would cost less in dollars. A reservation app might highlight a partnered restaurant over one closer to what the diner actually wanted.
The issuers are building these systems because they work—and they work in part because cardholders rarely stop to compare.
“At some point,” Ewen said, “you have to ask whether you’re optimizing for the card or for your life.”
此内容由惯性聚合(RSS阅读器)自动聚合整理,仅供阅读参考。 原文来自 — 版权归原作者所有。