








Top economist Kent Smetters thinks the U.S. is on a 20‑year clock—and the tilt of the federal budget toward baby boomers is at the center of the story.
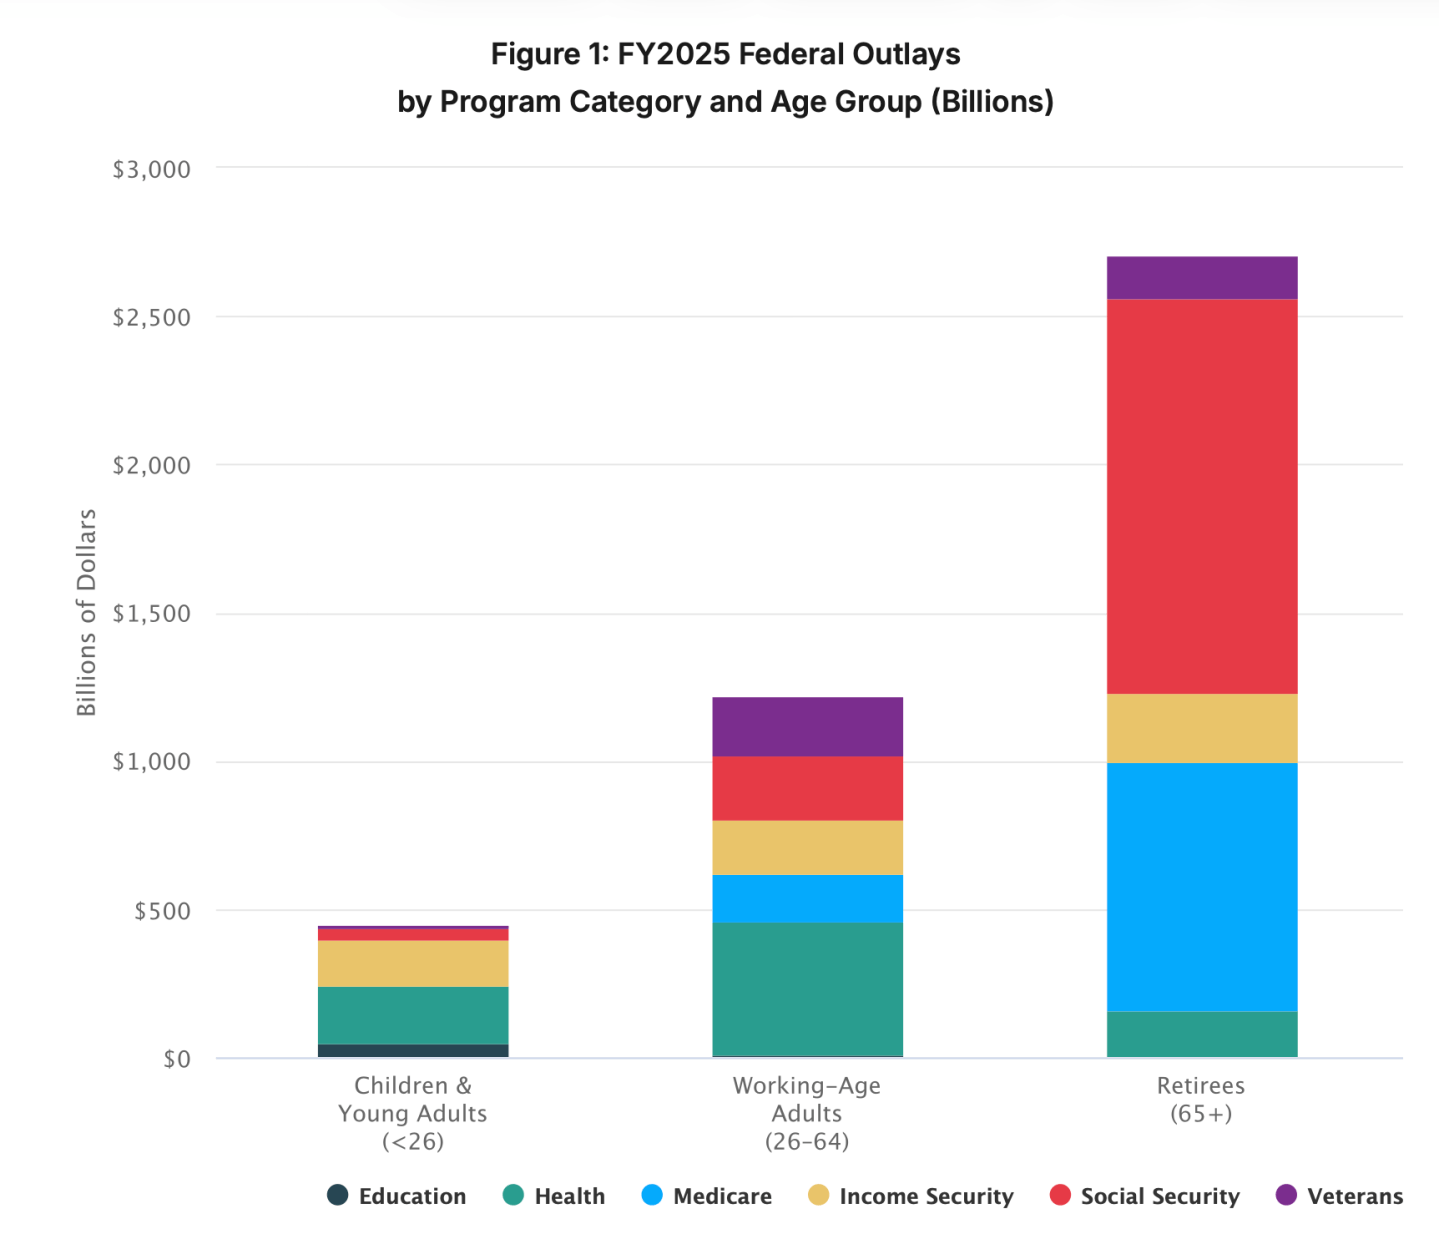
In a new analysis and in an interview with Fortune, the Penn Wharton Budget Model (PWBM) faculty director sketches an outer limit for U.S. federal debt and a political economy that heavily favors older Americans. His bluntest line may also be his simplest: “We do spend about 10x more per older person than we do per younger person. In total, we spend about 6x in aggregate on older people than younger people.”
This means means the average older person gets much more than the average younger person as a policy choice, but since there is a greater number of younger people, when you add up all dollars going to each group, the total to older people is “only” about six times. PWBM estimated in April retirees (adults age 65 and older) receive $2.7 trillion, equal to 38.6% of total federal outlays and 61.9% of age-assignable spending, while working-age adults (ages 26-64) receive $1.2 trillion (27.9% of age-assignable), and children and young adults (under age 26) receive $449 billion (10.3%).
Smetters added he works a lot on understanding the political economy of the U.S. and there’s just “a lot of incentive for every generation to try to pass a big bill to the next generation. The question is, how long can they get away with that?”
Smetters and his team estimate U.S. federal debt cannot rationally exceed about 210% of GDP. Above that level, he argues, there is no feasible broad‑based tax on labor income that can cover the interest bill at the returns investors will demand. That figure is an “outer bound,” not a forecast: In his words, it is “really the upper limit,” not a target that markets will calmly finance.
The more immediate concern is timing. Under what PWBM labels “historical” excess health care cost growth—the pace at which health spending per person has tended to outrun the broader economy—the U.S. is likely to hit that outer bound within about 20 years, with a one‑in‑four chance of hitting it in just 14. In the model’s median scenario, the “closure year”—the last point at which policymakers can still restore sustainability with a feasible tax—is as early as 2045 if health care costs grow quickly, and 2051 under more optimistic assumptions.
“The assumption is that the financial markets are being set in a way where they keep believing that Congress will eventually get its act together up until the point where it’s mathematically impossible for that to be true anymore,” Smetters said. “Sometimes people ask me, ‘You know, when could financial markets unravel?’ And the answer is, well, that could happen today, it could happen tomorrow, it could happen whenever they stop believing that Congress will eventually get its act together.”
Those dates line up uncomfortably well with the gradual fading of the baby boomer generation from positions of economic and political power. Asked whether it is a coincidence his 20‑year horizon roughly overlaps with the last years of baby boomer dominance in Congress and the C‑suite, Smetters was cautious but open to the framing.
He connected the budget choices to a broader psychology of ownership. In the Social Security and retirement space, he says, Americans routinely treat government‑funded benefits as if they were purely private property—even when taxpayers have put up most of the cash.
“We always stretch out what ownership is,” he told Fortune. “We like to think: ‘Yeah, If the government put in 90% and I put in 10%, I still want access to the entire account because I need to replace my roof and I have a good reason [for needing the funds].”
That mindset shapes the debate over Social Security, he added, where the main trust fund that pays retired workers’ benefits is projected to run dry in the early 2030s. Smetters noted his team was earlier than official forecasters in calling the “crossover date” when benefits would exceed revenues, and their depletion date—around 2032 for the main old‑age fund—has since been confirmed by the Social Security Trustees and the Congressional Budget Office.
Once the trust fund is exhausted, he estimated, the program can pay only about 83% of scheduled benefits, and that fraction erodes further over time. But he doubts that deadline will force timely action.
“The last time we fixed Social Security in 1983, we waited very close for bad things to happen,” he said. “Based on past experience, we’ve waited pretty long … to take action.”
In the current political debate, that looming Social Security shortfall has collided with a parade of more exotic ideas, from Trump Accounts for newborns to proposals for some kind of “AI dividend” that would redirect tech profits back to the public.
Smetters was skeptical.
“People are excited about AI and think it’s going to lead to all this economic growth. People are just misunderstanding it,” he said. “Even if it does lead to more growth than we’re projecting, spending is going to go up with it. It’s not true that AI will simply increase the tax base without increasing spending.” His biggest concern, he added, is how many of us are “really misguided in our understanding of future progress, future growth.”
Behind the scenes, Smetters has pushed a less flashy but more radical idea: Shut down the costly tax deduction for 401(k) and 403(b) contributions, which he estimates cost roughly $1.3 trillion to $1.4 trillion in forgone revenue over 10 years in earlier work, and reroute that money into non‑contributory retirement accounts for low‑income workers linked to the earned income tax credit. Crucially, he said, people would not be allowed to deposit their own money in those accounts at all, precisely to avoid the political pressure for early withdrawals that has undermined past efforts to nudge workers into saving more.
The psychology that Smetters describes isn’t new; the great comedian George Carlin captured it decades ago with the line Jon Stewart calls one of his most profound: “My shit is stuff; your stuff is shit.” It also recalls the paradoxical protest sign from a Republican voter about a federal benefit: “Keep your government hands off my Medicare!”
Smetters’ version is if the government funds 90% of your retirement account and you put in 10%, you still feel entitled to “the entire account” because, as he put it, “that’s all mine. It’s not yours.”
If the numbers and the politics sound abstract, Smetters insisted the consequences are not. When countries bump up against their fiscal limits, he said, the damage goes far beyond the bond market.
“You get this radical reordering when a country is overwhelmed with debt,” he said, pointing to episodes ranging from Germany’s collapse in the early 1930s to modern crises in Argentina. Fiscal crack‑ups, he argues, make voters more willing to gamble on strongmen or untested extremes on the left or right.
He said he keeps returning to Britain’s short‑lived Liz Truss government as a cautionary tale, referring to the prime minister whose unserious financial plan saw her ejected from office in less time than it took a head of lettuce to wilt, as the British press savagely noted.
“I think we’re actually going to see financial markets try to discipline us long before we hit that limit,” he said of the U.S. debt path. “We could easily have our Liz Truss moment in the United States within the next five, 10 years.”
The technical PWBM paper that underpins his concerns emphasizes the same point in more formal language, using a classic framework from economists Harold Cole and Timothy Kehoe: Even well before a country reaches its mathematical solvency limit, there is a “crisis zone” at intermediate debt levels where a shift in investor expectations alone can trigger a self‑fulfilling run. In that zone, markets don’t wait for the last dollar of capacity to be used up before demanding higher interest rates—or refusing to refinance government debt at all.
“What people don’t get is that when you have these financial collapses, it’s not just finance,” Smetters said. The problem the U.K. faces now, he said, is that they already have very high taxes so their “fiscal space” is quite limited in terms of what they can do now.
“That’s the problem with the baby boomer generation,” he added. “It’s going to be really hard to change benefits over time.” Sometimes when you have giant fiscal problems that keep going unsolved, year after year, “they can lead to really incredible changes in society that can be very disruptive, beyond just economics.”
此内容由惯性聚合(RSS阅读器)自动聚合整理,仅供阅读参考。 原文来自 — 版权归原作者所有。