


For four decades, the formula was simple: keep labor costs low, borrow cheap, return cash to shareholders. It worked spectacularly as corporate profit margins reached record highs, the S&P 500 compounded at historic rates, and the investor class got very rich.
But that formula is now broken. According to Goldman Sachs’ global strategy team, what’s replacing it will reshape every asset class, every sector, and every assumption baked into modern portfolio theory.
In a sweeping new research paper published Tuesday—Global Strategy Paper No. 76: The Post Modern Cycle, Navigating the Capex Boom—Goldman’s chief global equity strategist, Peter Oppenheimer, argued along with his team that the world has entered a structurally different investment era. It will be defined, he predicted, not by cheap capital and capital-light growth, but by rising real interest rates, geopolitical fragmentation and a synchronized surge in capital spending unseen since the postwar era.
Oppenheimer’s note was principally focused, fitting for a global strategist, on how equity returns will be reshaped in a new regime. But underneath lies another question for the middle-class professional, familiar to anyone who has watched their paycheck stagnate while their 401(k) soared: where does the money go?
For most of the past 40 years, the answer was: not to workers.
To understand where we are, Goldman starts with where we’ve been. The firm’s analysts divide the post-WWII era into three distinct economic regimes, each with its own logic of wealth distribution.
The Traditional Cycle, roughly pre-1980, was volatile and inflationary. Investors demanded high dividend yields just to tolerate equity risk. Returns were lumpy, macro variables swung wildly, and no single asset class dominated.
The Modern Cycle, from roughly 1982 to the pandemic, was something else entirely. The Volcker shock had beaten inflation into submission. Reagan and Thatcher were dismantling the postwar labour settlement—deregulating industries, busting unions, privatizing state assets, cutting corporate taxes from highs above 50% to the 20s. And then, in the 1990s, globalisation arrived in full force.
The arithmetic was straightforward. Between 1990 and 2009, the share of labour compensation in national income fell in 26 out of 30 advanced economies, with the median labour share declining from 66.1% to 61.7%, according to OECD data cited in the report. World trade grew at twice the pace of global GDP between 1995 and 2010. Manufacturing jobs migrated to lower-cost regions. Wages in the West stagnated as profit margins at home soared.
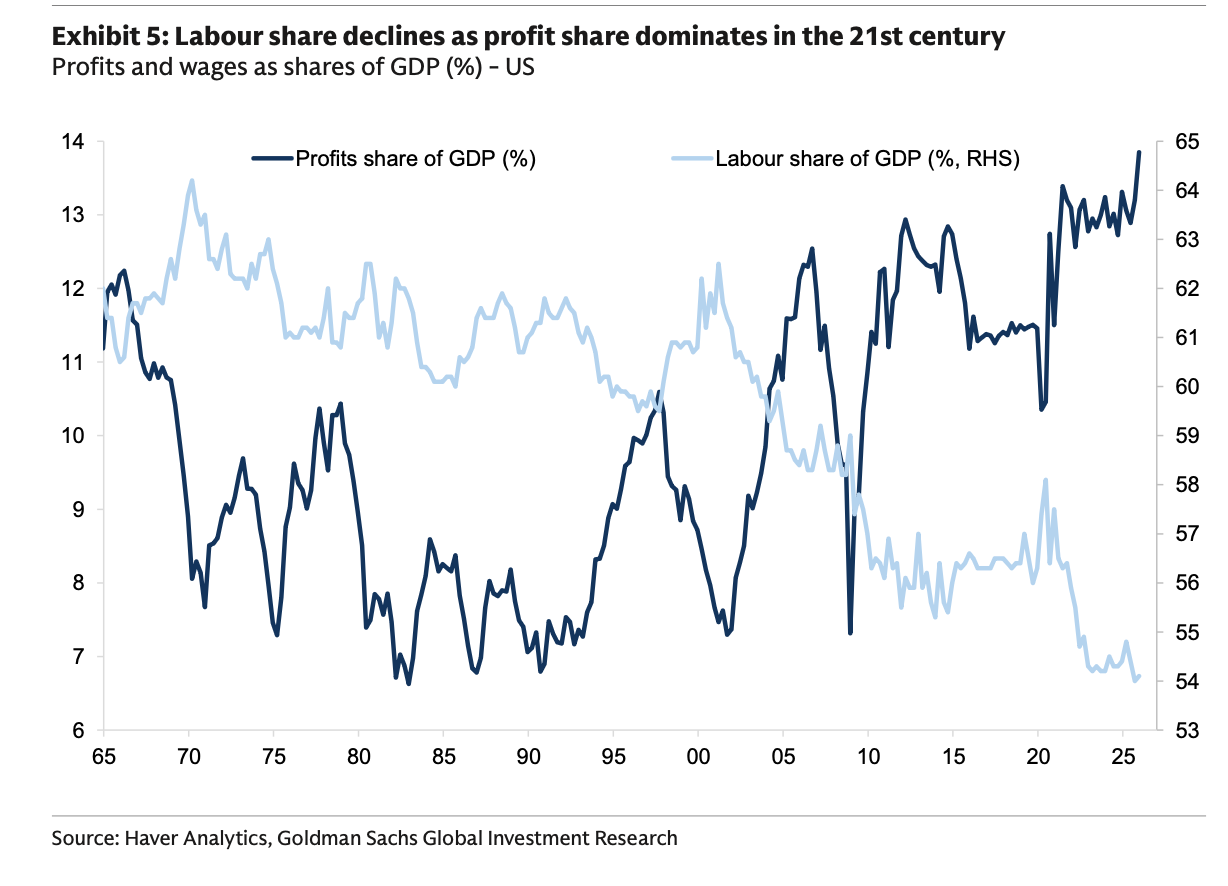
Your raise, in the bluntest terms, went offshore.
Then came 2008, and everything changed, except for shareholders.
The Global Financial Crisis was catastrophic for the real economy. The recovery that followed was, by Goldman’s own data, the weakest since 1950. And yet equity markets staged one of their strongest recoveries on record, entirely disconnected from underlying economic growth. The S&P 500 rose more than 400% between March 2009 and 2022. Wages, adjusted for inflation, barely moved.
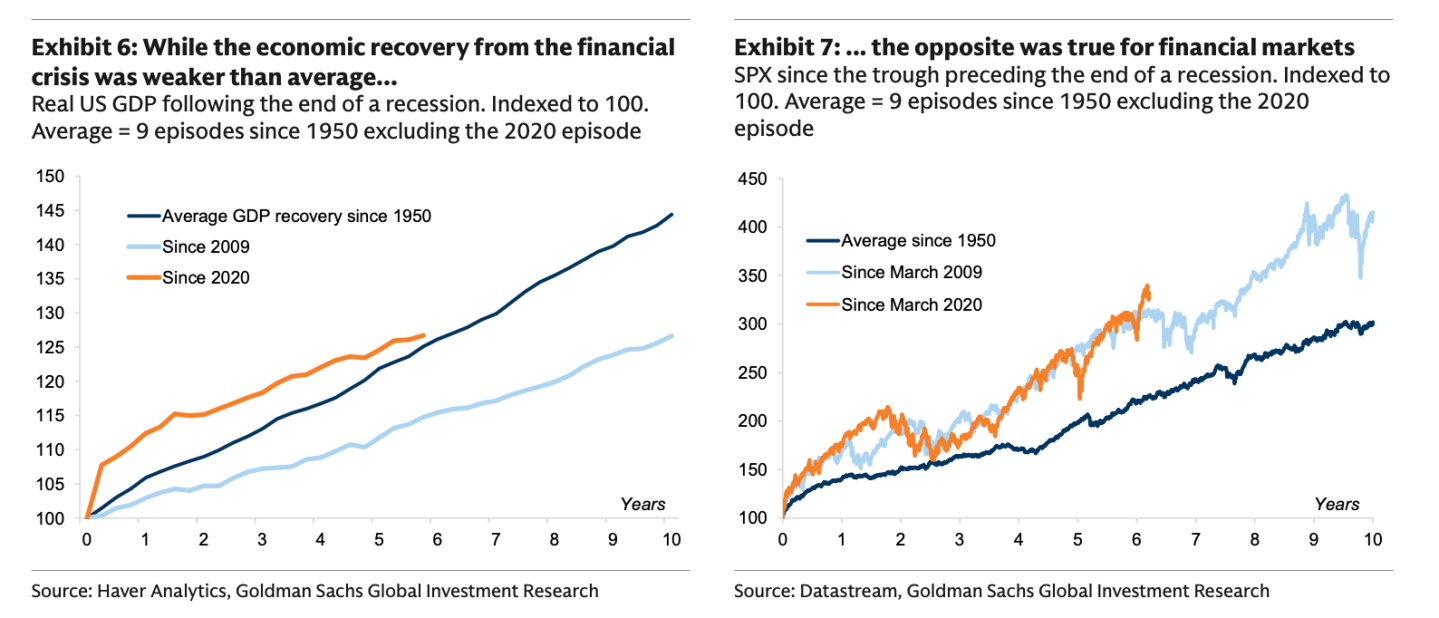
The mechanism was the buyback. With interest rates pinned near zero by the Federal Reserve, companies could borrow almost for free. Rather than invest that capital in new factories, new workers, or new supply chains, most chose to return it to shareholders through stock repurchases. The tech sector—which had front-loaded its infrastructure spending during the dot-com boom and was now harvesting the returns—was particularly aggressive, generating soaring returns on equity that rewarded investors while keeping headcount lean.
“The best asset returns were seen in long-duration growth areas of the market,” Goldman’s strategists wrote, “while ‘old economy’, real assets and value lagged behind.”
The S&P 500 technology sector returned more than 1,000% in the decade following the financial crisis. US manufacturing employment never recovered its pre-crisis levels. The top 1% of Americans now own 50% of all corporate stock and mutual funds.
Your raise, in the zero-rate era, went to a buyback. But something broke that model around 2022, Oppenheimer argued, and it didn’t break gently.
Supply chain disruption from the pandemic triggered the first serious inflation in a generation. Interest rates rose faster than at any point since the Volcker era. And then, almost simultaneously, two other forces arrived: the geopolitical order that had governed global trade for 80 years began to crack, and a technology called the large language model began to consume capital at a rate that startled even the companies deploying it.
The numbers Goldman cites are staggering. The top five hyperscalers—Amazon, Meta, Google, Microsoft, and Oracle—are expected to spend approximately $755 billion on capital expenditures in 2026, up 84% from 2024. Consensus estimates for 2027 put that figure at roughly $920 billion. S&P 500 companies reported year-over-year capex growth of +38% in Q1 2026, compared to just +1% for buybacks—an almost exact inversion of the dynamic that defined the previous decade and a half.
“For the first time in many decades,” the Goldman analysts write, “the demand for capital is rising.” This is not a Goldman-only position. Apollo Global Management Chief Economist Torsten Slok calls it “the industrial renaissance,” while the Trump administration calls it a “manufacturing renaissance.”
Oppenheimer finds the demand of this postmodern era is not going to workers, at least not primarily. It is going to data centers, semiconductor fabs, power grids and fibre networks, as the physical infrastructure of artificial intelligence requires extraordinary amounts of capital and relatively few people to build and maintain it. Nvidia’s market capitalization per employee remains one of the highest in corporate history. The AI boom has created 19 new billionaires worth a combined $59 billion in the past year, per Bloomberg. From ChatGPT’s launch through March, the top 20% of households saw equity holdings surge by $29.8 trillion—a 154% increase—while the bottom 80% gained a combined $4.2 trillion. As of the close of 2025, 33% of total U.S. household wealth was in stocks—higher than the dot-com peak in Q1 2000.
Your raise, in the AI era, is going to a data center.
Goldman’s paper is directed at investors, not workers, and its prescriptions reflect that orientation. The strategists recommend building exposure to what they call “capex beneficiaries”—a basket of roughly 50 global companies whose revenue growth is most tightly correlated with the global investment cycle. The list spans AI infrastructure, power and energy security, defense contractors, and capital-intensive industrials: ASML, Lam Research, Schneider Electric, Broadcom, Vistra. The basket is up roughly 25% year-to-date.
This is not, the Goldman team is careful to note, simply a bet on tech. The most important implication of their postmodern thesis is a broadening of the opportunity set away from the concentrated US-technology-growth trade that defined the previous cycle. For the first time in 15 years, old economy sectors—industrials, energy, defense, real assets—are outperforming on a sustained basis. Gold, emerging markets, and the Japanese equity market have led global returns in 2025 and into 2026. The median stock in each major region is, for the first time in years, contributing meaningfully to index returns rather than being carried by a handful of mega-caps.
Oppenheimer’s team is among the most sophisticated macro analysts on Wall Street, and their framework is genuinely illuminating. But the paper, by design, addresses the investor. It does not ask what the postmodern cycle means for the person whose raise funded 40 years of shareholder supremacy.
That question is not abstract. The structural shift Goldman documents—from disinflation and globalization to reflation and regionalization, from capital-light to capital-intensive, from buybacks to capex—could, in theory, benefit workers. Infrastructure spending creates jobs. Defense ramp-ups employ engineers, welders, and machinists. A less globalized supply chain means more domestic manufacturing.
But the distribution of those gains depends on policy choices—on tax structure, on union density, on antitrust enforcement, on immigration—that Goldman’s paper does not model. What it does document, with considerable rigor, is that we are living through a transition as significant as the one that began in 1982. That transition made the investor class extraordinarily wealthy. Whether this one does the same—and for whom—is the defining economic question of the decade.
The data center is being built. Who owns it is still being decided.
For this story, Fortune journalists used generative AI as a research tool. An editor verified the accuracy of the information before publishing.
此内容由惯性聚合(RSS阅读器)自动聚合整理,仅供阅读参考。 原文来自 — 版权归原作者所有。