







| Updated:
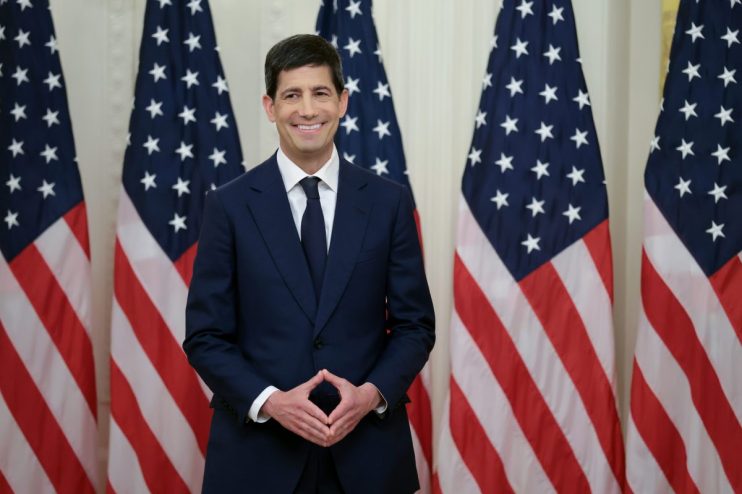
Kevin Warsh wants to take us back to a world where the semi-annual Humphrey-Hawkins testimony of the Fed Chair to Congress is effectively the moment where the Monetary Wizard of Oz steps out from behind the curtain to signal the direction for interest rates, says Helen Thomas
“I don’t view the Chairman, in his testimony or in his announcement of projections, as the press spokesman for the FOMC”. So said Kevin Warsh in the FOMC (Federal Open Market Committee) meeting of 30-31st January 2007; 19 years later he can finally put this position into practice. On Wednesday he will hold his first press conference as the new Chair of the US Federal Reserve and one of his first changes is likely to be a reduction in the length and frequency of these post-meeting media briefings. After all, under Alan Greenspan there were no press conferences at all. Ben Bernanke introduced them quarterly before Jerome Powell added one to every meeting, such that any FOMC date could be considered “live” for a move on interest rates.
This won’t be the only change under the Warsh Fed. The so-called “dot plot” which shows where each FOMC member thinks interest rates should be over the next few years is almost certainly about to disappear. Warsh has always been sceptical over the increasing move by central banks towards more transparency, arguing in a review he did for the Bank of England in 2014 that “All communication… is not created equal”. He narrowed down his criticism to the dot plot in his confirmation hearing earlier this year, warning “The Fed tells the whole world what their dots are going to be, what their forecasts are going to be. Then they hold on to those forecasts longer than they should”. He argued that policymakers become psychologically attached to published forecasts and that policy would improve if decisions were made with more deliberation at the meeting itself rather than being telegraphed months in advance. At the very least this suggests that this week we won’t see a Kevin Warsh dot included in a chart that is about to be made redundant.
Far from hearing from the 19 different FOMC members, both voting and non-voting, Warsh wants to return the power of the Fed back to the position of Chair. Back in 2007 he called this “the ‘benevolent leader’ model”. This is not the unilateral decision making of a benevolent dictator but nor is it simply representing a consensus of the committee average. It would be somewhere between the two, where “very much alongside his views, he would present our views. His presentation of our views is useful in making certain that a lot of attention is focused on them… in some ways we might well be delegating to him the ability to draw a central tendency and make appropriate conclusions”. This would be quite a radical departure from the devolutionary drumbeat of the last decade, where individual Fed speakers have held weight in their own right. Some members have always been more equal than others but there is no doubt that the median forecast became a kind of ghostly figure in its own right. Now, Warsh wants to take us back to a world where the semi-annual Humphrey-Hawkins testimony of the Fed Chair to Congress is effectively the moment where the Monetary Wizard of Oz steps out from behind the curtain to signal the direction for interest rates.
This gnomic approach was rejected in the wake of the financial crisis. When monetary policy had to move into unconventional territory at the zero lower bound for interest rates then central banks had to use new tools, such as forward guidance, to push on a string as hard as possible. Slaying the deflationary demon of doom was a central banker’s worst nightmare; failure to do so would render the institution impotent and devoid of credibility. And so they tried all sorts of new tricks from QE to Yield Curve Control but also using communication to make commitments to keep interest rates lower for longer. But in a world of more normal levels of interest rates and inflation, central banks don’t need to massage basis points onto low and flat yield curves in order to squeeze another drop from tapped-out monetary policy. Restoring the veil to the process would give Kevin Warsh more flexibility along with more bang for his buck when he does decide to act on interest rates.
It also gives Warsh more political breathing room. Fewer speeches and less communication means less opportunities for his political patron, Donald Trump, to regret making him Fed Chair in the first place. If Warsh can return power to his personal position rather than making it diffuse across FOMC members then he can surprise markets when he wants, giving him a trump card to deal with any Trump criticism.
The irony is that after two decades spent pulling back the curtain on the Fed’s inner workings, Warsh’s revolution may be to draw it closed again. The dot plot, the endless speeches and the ritual parsing of every policymaker’s remarks were all designed to make monetary policy more predictable. Warsh appears to believe they have instead made it more constrained. If so, Wednesday’s press conference may be remembered not simply as the start of a new Fed chairmanship, but as the beginning of the end of the great transparency experiment in central banking. The real test will not be whether markets know less about what the Fed is thinking, but whether they trust it more when it finally speaks.
Helen Thomas is founder and CEO of Blonde Money