









| Updated:
Municipal bonds could create genuine local economic autonomy. But they require infrastructural change to work, writes Tim Focas
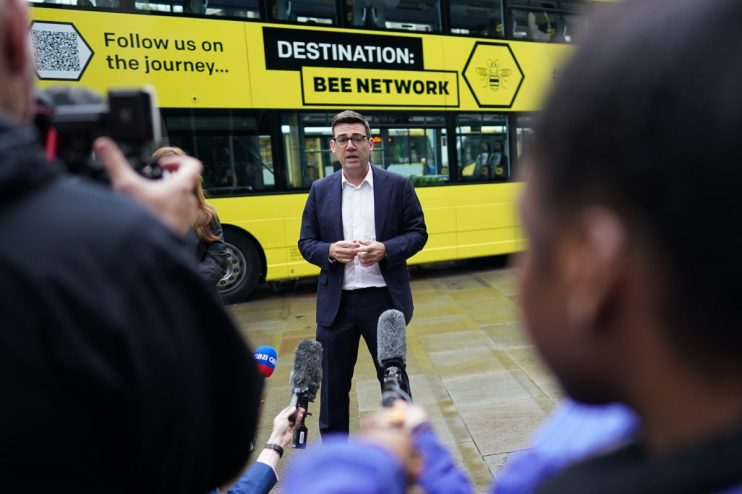
It is hard to think of a UK politician that has banged the English devolution drum harder than Andy Burnham. The Labour leadership front runner has become the poster child for what happens when local leaders are given the autonomy to shape their own economic destiny. But let’s be absolutely clear, from George Osborne’s Northan Powerhouse to BoJo’s levelling up agenda, all devolution initiatives over the past two decades have had a reliance on Westminster to hand over the money.
It is therefore unsurprising that there is growing appetite for next stage of devolution which would allow mayors to issue municipal bonds to raise capital directly from institutional investors. Yes, we already have the very catchy UK municipal bond agency (UKMBA) that was created back way back during Cameron and Osborne’s time. But this only helps councils finance small investments and, due to its inability to convince local authorities to raise money from the markets since being created in 2014, is now closed for any new debt issuances.
So for all Burnham’s positivity about his track record, every major local infrastructure project still needs treasury officials in London to give the green light to funding. But why is this the case? After all, why shouldn’t ambitious local councillors borrow to invest in the roads, railways, housing and AI data centre infrastructure needed to unlock growth?
Well, it is not so much that local borrowing is inherently bad. After all, look at what it has done for places much further afield like Mississippi in the US, which has projected GDP growth of 1.5 per cent this year, building upon just under 2 per cent growth in 2025.
Investors reward strong economies
The problem is more that debt investors, just like they do with nation states, reward strong economies with lower interest rates and punish weaker ones with higher borrowing costs. That creates a serious challenge to the argument that municipal bonds alone will help “level up” Britain. Take London as a prime case in point. With its massive tax base and global financial centre status, the City would almost certainly be able to borrow more and at lower rates than almost any other part of the country. Investors would be able to rest easy at night knowing that London’s economy is comfortably able to generate the money needed to service debt.
Now compare that with a struggling post-industrial town like Bradford facing weak growth and high unemployment. The market would demand a much higher return to compensate for the greater perceived risk. Consequently, the places already best positioned to attract investment would gain access to the cheapest capital in order to grow faster. Whereas those most in need of investment would face sky high borrowing costs. What begins as a policy designed to decentralise power could end up reinforcing precisely the regional inequalities it is supposed to solve.
Now this is not an argument against municipal bonds, but it is a case against introducing them without a credible fiscal structure. A proper municipal bond model, not like the failing UKMBA, would shift responsibility to local leaders and introduce market discipline into local government finance.
Fiscal discipline must also be devolved
But this can only work if fiscal discipline is also devolved and, most importantly, central government is fully confident in the financial expertise residing at a local level. Every authority needs will need City skill set while operating under clear and transparent rules. Debt should be linked to investment rather than day to day spending. Also, borrowing limits should be tied to revenues and financial reporting has to be monitored constantly. Most importantly, there should be no ambiguity about whether the treasury will come to the rescue if a local authority gets into trouble. Without those safeguards, investors will assume government guarantees exist.
The lesson from the so called success story that is Manchester is not that every mayor should be handed an open cheque book. It is that local leaders perform best when given meaningful powers within a fiscal framework of accountability. Municipal bonds could become one of the most important economic reforms this country has seen since Gordon Brown handed interest rate powers over to the Bank of England. They could help break the unhealthy obsession with Whitehall micromanagement and create genuine local economic autonomy. However, if ministers want a genuine municipal bond revolution, they must first build a rigorous set of fiscal rules that makes it viable for the long term unlike the UKMBA which has seemingly ground to a shuddering halt. Otherwise, the bond market will do what bond markets always do. They will reward strength, punish weakness and make existing inequalities between the North and South even harder to overcome.
Tim Focas is head of capital markets at Aspectus Group