


March 6, 2026
By Lloyd Arnold, Data Center Analyst, BloombergNEF
A massive buildout of data center capacity is underway. BloombergNEF has tracked 22.8 gigawatts of IT capacity (or compute capacity) currently under construction globally. This is likely to come online in the next three years, and is more than a third of the size of the existing market. As challenges emerge in existing data center hubs, developers are looking to new geographies for the next phase of growth.
1. Energy and land are the most important factors in data center development
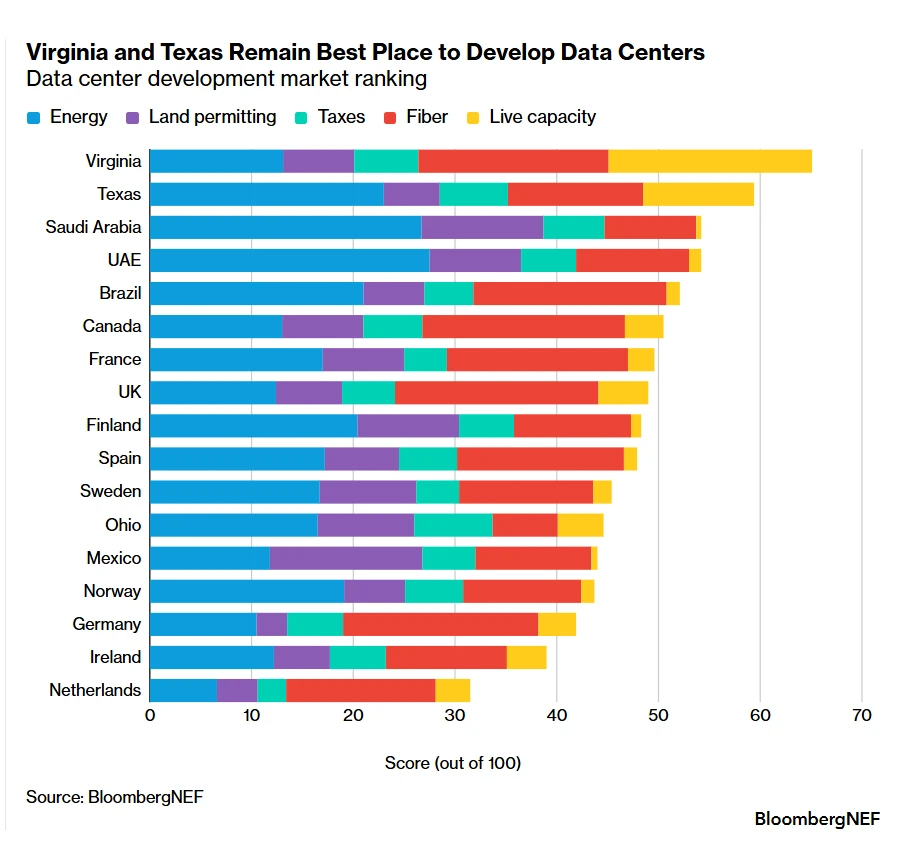
Through conversations with data center developers, BNEF developed a framework to assess the how friendly a market is for new data centers. Energy availability and land permitting emerged as the most important factors, together making up 58% of a markets overall score. Tax policy, fiber connectivity and existing data center capacity rounded out the scoring system, which consists of 43 metrics per market.
2. US is the market leader, and will likely stay at top position
The US is the most important data center market in the world, representing 51% of current live IT capacity (29.9 gigawatts) and 72% of capacity under construction. The country has significant historical importance as a data center market, and it is experiencing outsized gains from increasing AI demand due to the concentration of AI companies on its shores. Virginia and Texas both have more live data center capacity than most national markets, and scored as the top two markets in BNEF’s recent market ranking.
There are challenges in both the top US markets, as their power grids come under growing strain and public attitudes shift. Community opposition to data center projects is growing, and several high profile projects have been stalled, such as the Digital Gateway development in Prince William County, Virginia. Despite this, they remain highly desirable – over 66GW of data center IT capacity is planned across the two states.
3. Middle East is high-risk, high-reward for data center developers
Saudi Arabia and the United Arab Emirates came in at third and fourth in BNEF’s ranking, lifted by strong scores on energy availability and land permitting. Power in the region is cheap, and installations are growing. Both governments are also very supportive of developing data centers in the markets, and construction permits can be obtained quickly.
BNEF’s assessment did not include geopolitical risk, but this could affect future development in the region. Export controls on advanced chips were introduced by the Biden administration, and then partially lifted by the Trump administration but could be re-introduced. There are also questions about the willingness of American technology companies to operate in the market – AI firm Anthropic has indicated that it will not use data center capacity in the market.
4. Europe is increasingly two-track
Historically, the European data center market has been centered around “FLAP-D” – the metropolitan areas around Frankfurt, London, Amsterdam, Paris and Dublin. These cities are hubs of the technology and finance sectors, both of which drove early demand for compute, and they have also developed into important fiber hubs. However, grid congestion, high power prices, long interconnection queues and lack of available land now serve as major headwinds in these regions and, to varying extents, in their national markets.
As challenges mount in traditional hubs, early stage capacity is increasingly shifting to the Nordics, and to Spain. These markets offer a similar pitch: lots of land, cheap and clean energy as well as and generally, more supportive attitudes to data center development. This is demonstrated when we look at our average scores for Europe’s second tier markets against those for FLAP-D. The former achieved significantly stronger scores on energy and land permitting.
Related Content
The latest from BloombergNEF delivered to your inbox
Sign up for BNEF’s free newsletter.